DataM resources that are widely useful for your reference. We have curated special links for you to browse through

AI infrastructure demand is accelerating, but data center growth now depends on power access, financing, water resilience, data sovereignty and high-density design. This weekly intelligence review examines the developments shaping five strategic markets.
September 28, 2026

the latest developments influencing the global data-center industry, from hyperscale campus construction and AI-cloud investment to grid access, water management, planning constraints, high-density cooling and emerging regional capacity hubs.
September 24, 2026

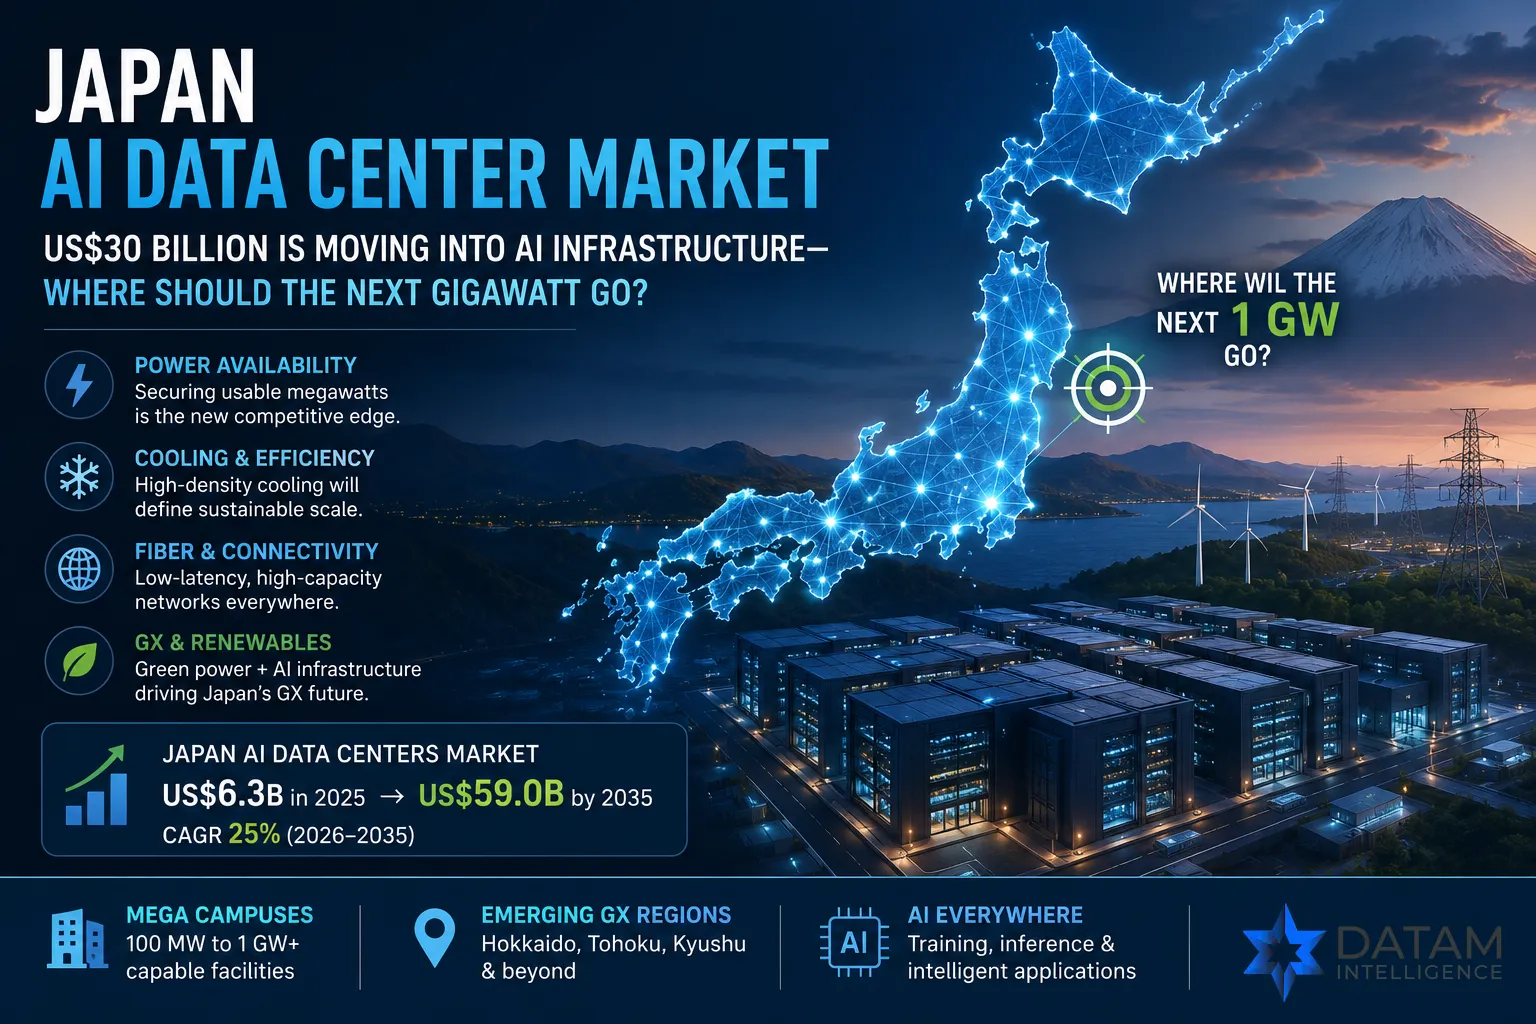
Blackstone’s US$30 billion plan is putting Japan’s AI infrastructure under the spotlight. The bigger question is where Japan can actually support the next gigawatt of AI data center capacity across Tokyo, Osaka, Hokkaido and emerging GX regions.
August 27, 2026

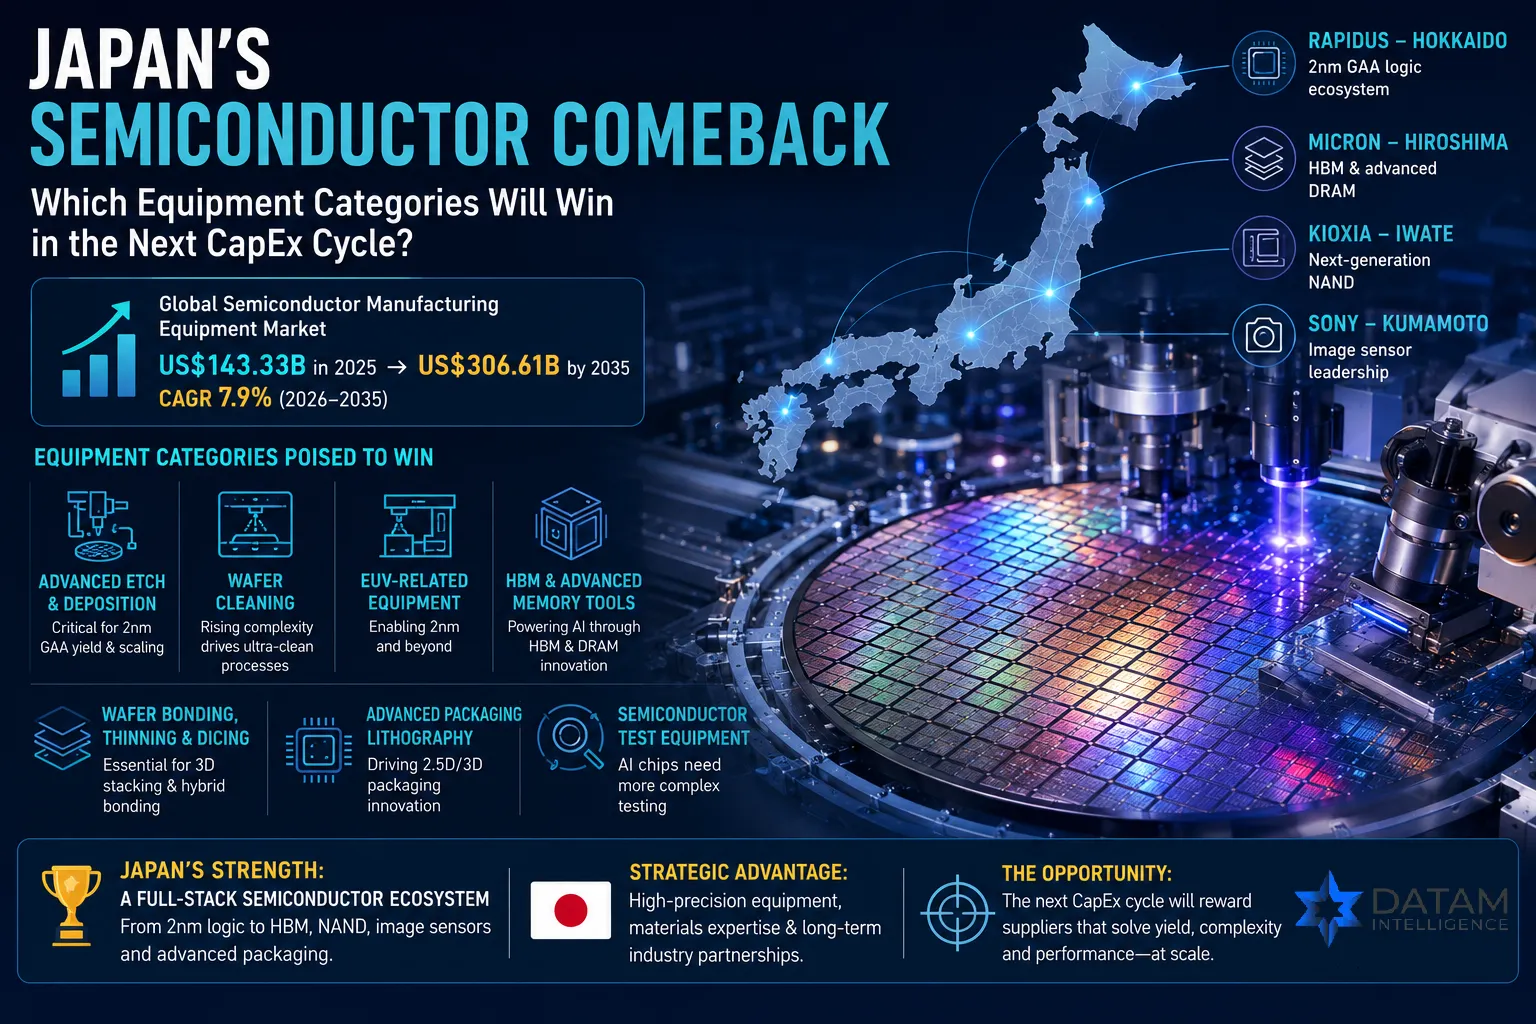
Japan is rebuilding semiconductor manufacturing across Hokkaido, Hiroshima, Iwate and Kumamoto, but the next equipment cycle will not reward every tool category equally. Rapidus, Micron, Kioxia and new advanced packaging programs are pushing spending toward 2nm process tools, HBM equipment, wafer bonding, test, cleaning and precision processing.
August 27, 2026

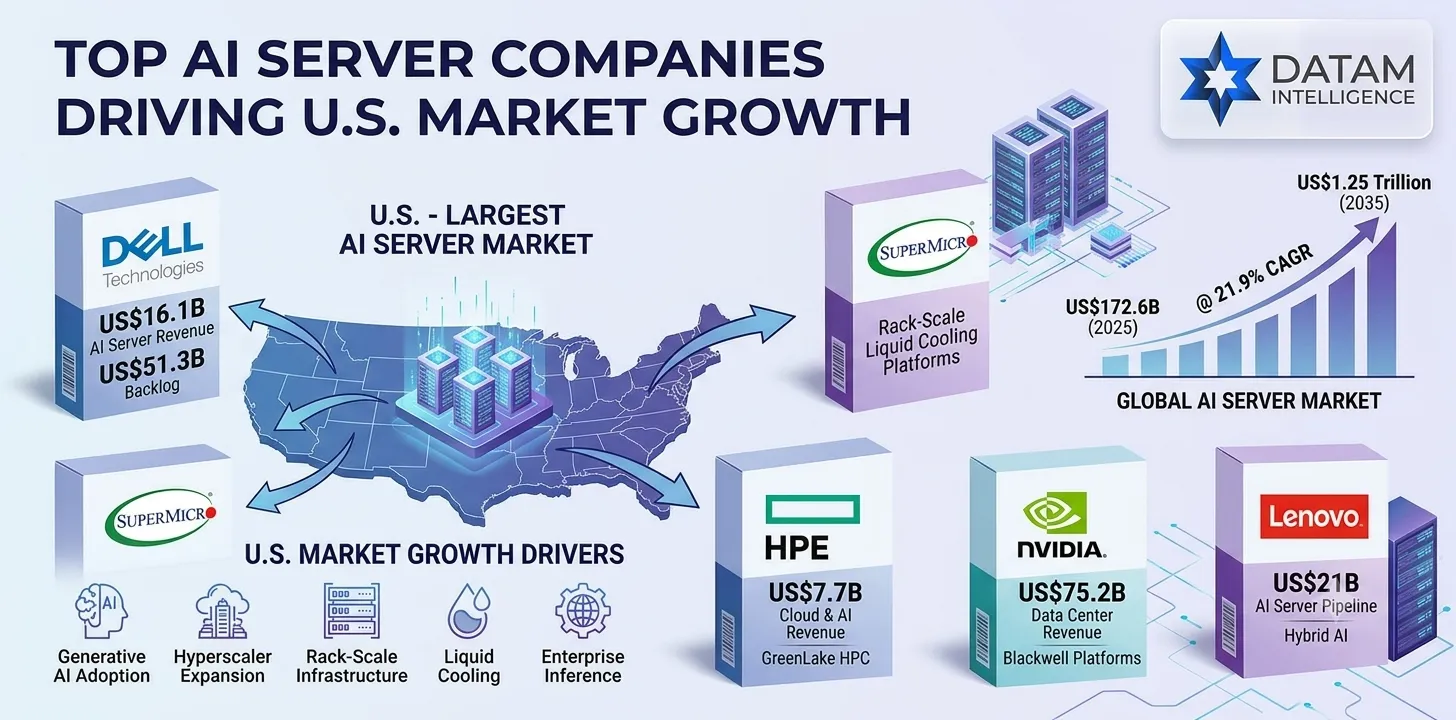
The top AI server companies driving U.S. market growth include Dell Technologies, Super Micro Computer, Hewlett Packard Enterprise, NVIDIA, Lenovo, IBM, Cisco and AMD. These companies are benefiting from growing demand for GPU-accelerated computing, generative AI infrastructure, enterprise AI and hyperscale data centers.
August 25, 2026

Global investment in AI infrastructure is accelerating as hyperscalers, financial institutions, and technology companies commit unprecedented capital to data centers, power systems, and advanced computing networks. The emerging financing ecosystem is becoming a critical enabler of AI growth, creating new opportunities across energy, semiconductors, cloud computing, and digital infrastructure.
August 18, 2026