


Tungsten-Based Materials Market Size and Overview
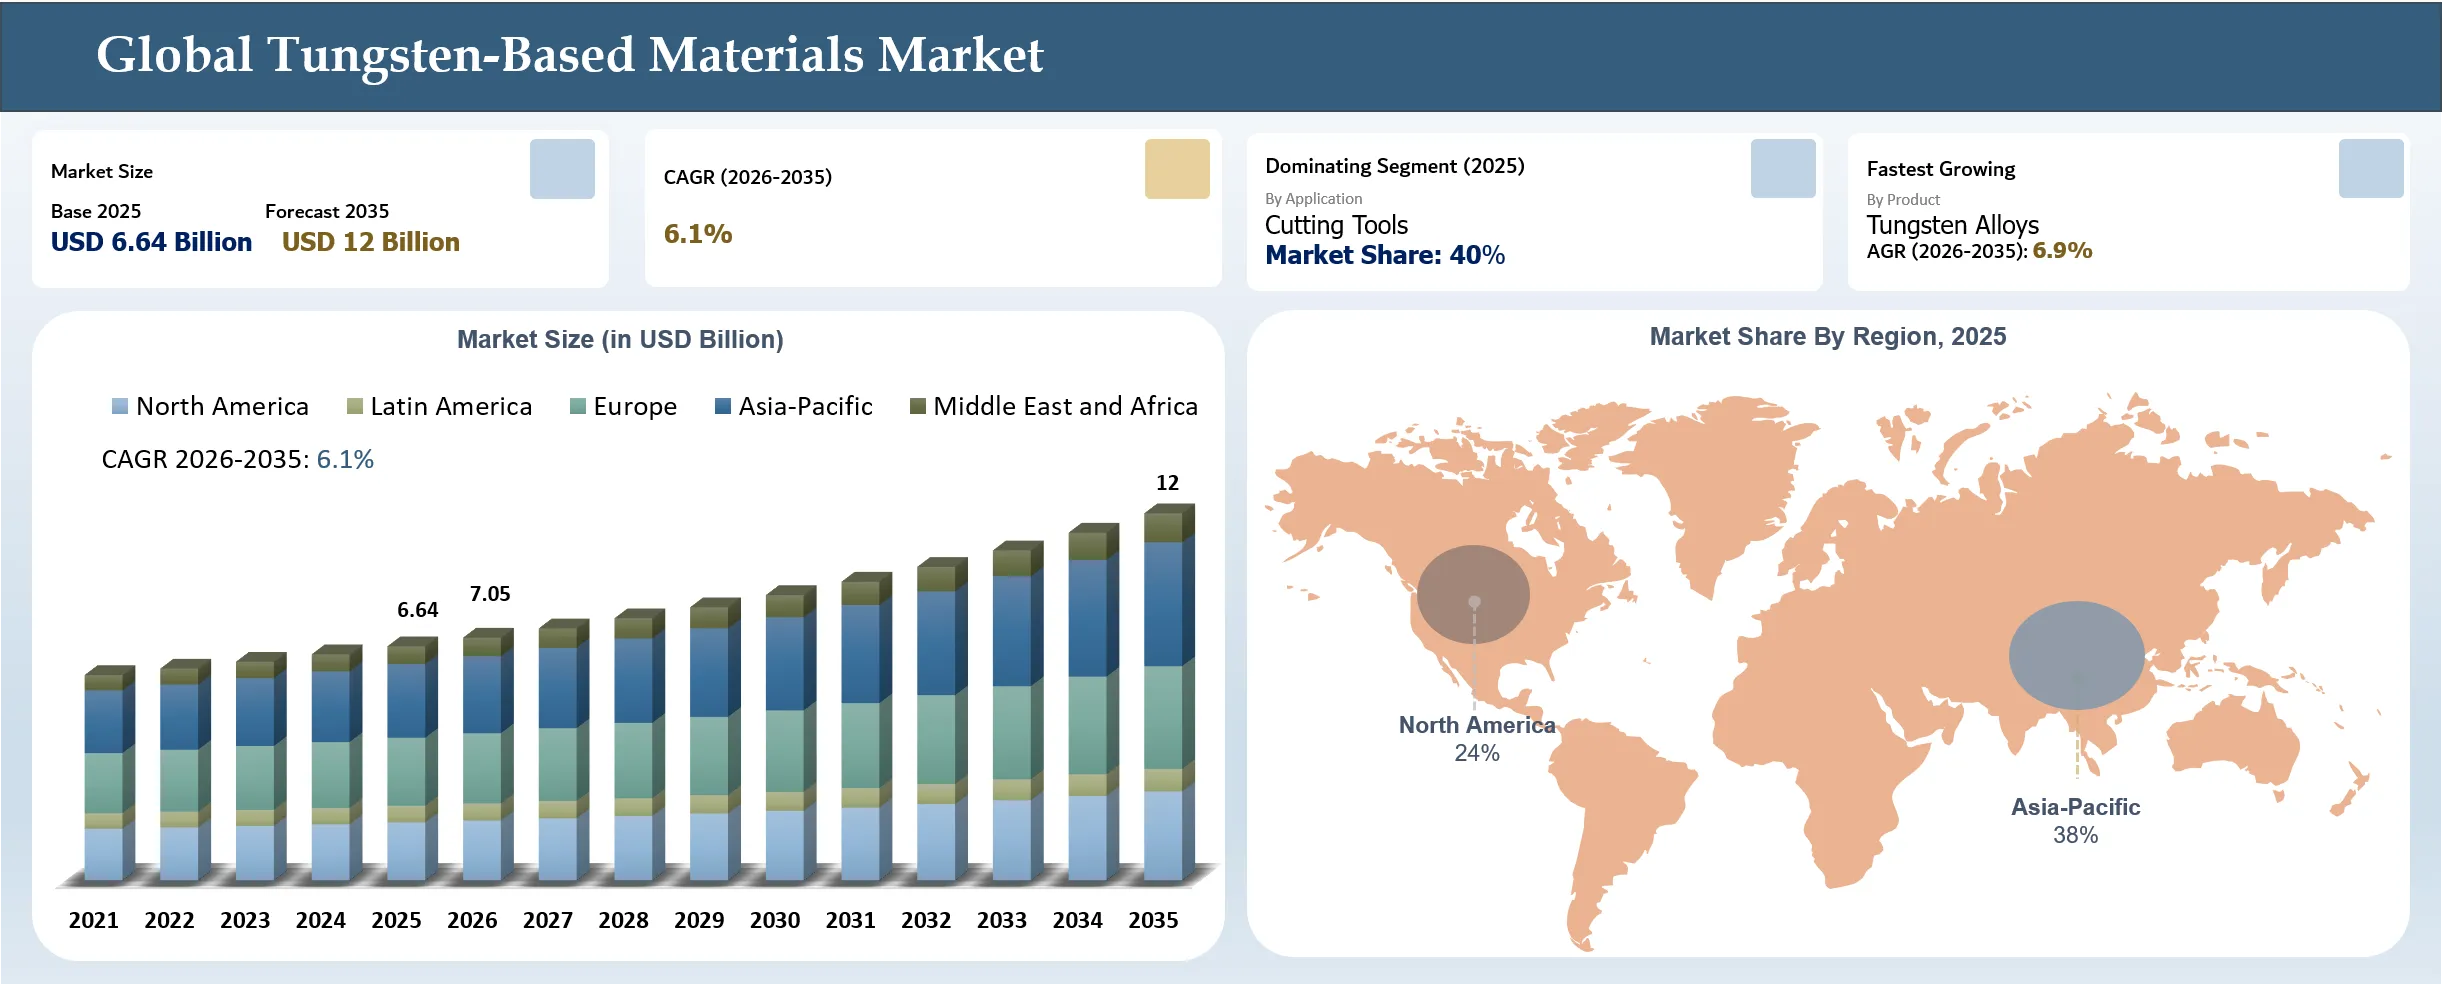
The global tungsten-based materials market reached USD 6.64 billion in 2025 and is expected to reach USD 12 billion by 2035, growing with a CAGR of 6.1% during the forecast period 2026-2035. The market is gaining momentum as tungsten-based materials become increasingly important in defense, aerospace, semiconductors, toolmaking, electronics, and manufacturing industries, where density, hardness, stability, and wear-resistant properties become key. In February 2026, according to USGS, China continued to be the dominant tungsten producer, and world tungsten prices soared during 2025 due to Chinese export regulations, which caused the Rotterdam price for 65% tungsten concentrate to soar from USD 266 to USD 551 per metric ton, and the APT price to increase from USD 331 to USD 675 per metric ton.
The company's Sangdong tungsten mine in South Korea started the operation of its first phase of production in March 2026, which was set up with an estimated capacity of 640,000 metric tons of ore annually, with 2,300 metric tons of tungsten concentrates expected annually. Phase 2, scheduled to start in 2027, will increase the processing capacity to 1.2 million metric tons of ore annually and tungsten production capacity to an estimated 4,600 metric tons, providing 40% of global tungsten needs outside China.
As demand for tungsten-based materials continues to expand across strategic and high-performance applications, increasing emphasis on supply security, geographic diversification, and the development of non-Chinese tungsten resources is expected to shape market dynamics through 2035. The combination of demand growth from advanced industries and ongoing investments in tungsten mining and processing capacity is likely to create new opportunities across the global tungsten-based materials value chain.
White-Space Opportunities for U.S. and Allied Tungsten Supply Chain Expansion and Advanced Materials Manufacturing
In September 2026, the U.S. Department of War committed USD 450 million to The Elmet Group to strengthen the domestic and allied tungsten supply chain, with the largest identified investment area being domestic tungsten manufacturing and processing infrastructure.
More than USD 165 million is planned for modernization and expansion of Elmet’s facilities in Maine, Michigan, and Ohio to increase production of tungsten heavy alloys and powders for defense and industrial applications, while approximately USD 150 million is allocated to the Springer Tungsten Complex in Nevada to restart the mine and mill and expand ammonium paratungstate (APT) conversion capacity through a joint venture with Blue Moon Metals and EQ Resources.
In addition, up to USD 150 million is planned for allied tungsten supply diversification through investments and partnerships involving the Mt. Carbine Mine in Australia and Barruecopardo Mine in Spain, creating additional opportunities across mining and international feedstock supply.
The investment is expected to create significant procurement and expansion opportunities across the tungsten-based materials value chain. The Elmet Group benefits through expanded tungsten heavy-alloy and powder manufacturing, domestic processing, refining, and supply-chain integration, while Blue Moon Metals benefits through redevelopment of the Springer mine and mill and the establishment of new APT processing capacity.
EQ Resources benefits through its role in the Springer joint venture, tungsten concentrate offtake, and processing integration, while its Mt. Carbine Mine provides an additional source of tungsten feedstock for the allied supply network. In mining and concentrate supply, Blue Moon Metals and EQ Resources can support upstream tungsten production and concentrate availability, while the Barruecopardo Mine in Spain provides another strategic source for diversified European tungsten supply.
Tungsten-Based Materials Market Key Takeaways
- The Asia-Pacific region led the global market in 2025, holding approximately 38% total market share. Regional leadership is sustained by China's raw processing power alongside downstream demand in Japan, South Korea, and Southeast Asia.
- Cutting tools formed the largest application segment in 2025, holding a 40% share of the global tungsten-based materials market. This sector was impacted when China reduced its annual tungsten mining quota by 6.5% and limited export permits to 15 companies in late 2025.
- Defense-sector demand for tungsten is expanding at roughly 8% annually, positioning it to potentially overtake automotive as the top end-user by the mid-2030s. By April 2026, Rotterdam APT prices exceeded USD 3,000 per metric ton, a 200%+ jump since early 2026.
- The U.S. Department of War allocated USD 450 million to The Elmet Group in September 2026 to reinforce allied tungsten supply chains. Over USD 165 million of this package is directed to facility expansions in Maine, Michigan, and Ohio.
Tungsten-Based Materials Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 6.64 Billion | |
| 2035 Projected Market Size | USD 12 Billion | |
| CAGR (2026-2035) | 6.1% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | Asia-Pacific | |
| By Product | Tungsten Carbide, Tungsten Alloys, Tungsten Chemicals, Tungsten Metal, Tungsten Powder, Others | |
| By Form | Powder, Rods, Sheets, Others | |
| By Application | Heaters, Filaments, Electrodes, Cutting Tools, Radiation Shielding, Others | |
| By End-User | Aerospace & Défense, Automotive & Transportation, Electronics & Electrical, Mining & Construction, Medical & Healthcare, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Tungsten-Based Materials Market BCG Matrix: Company Evaluation
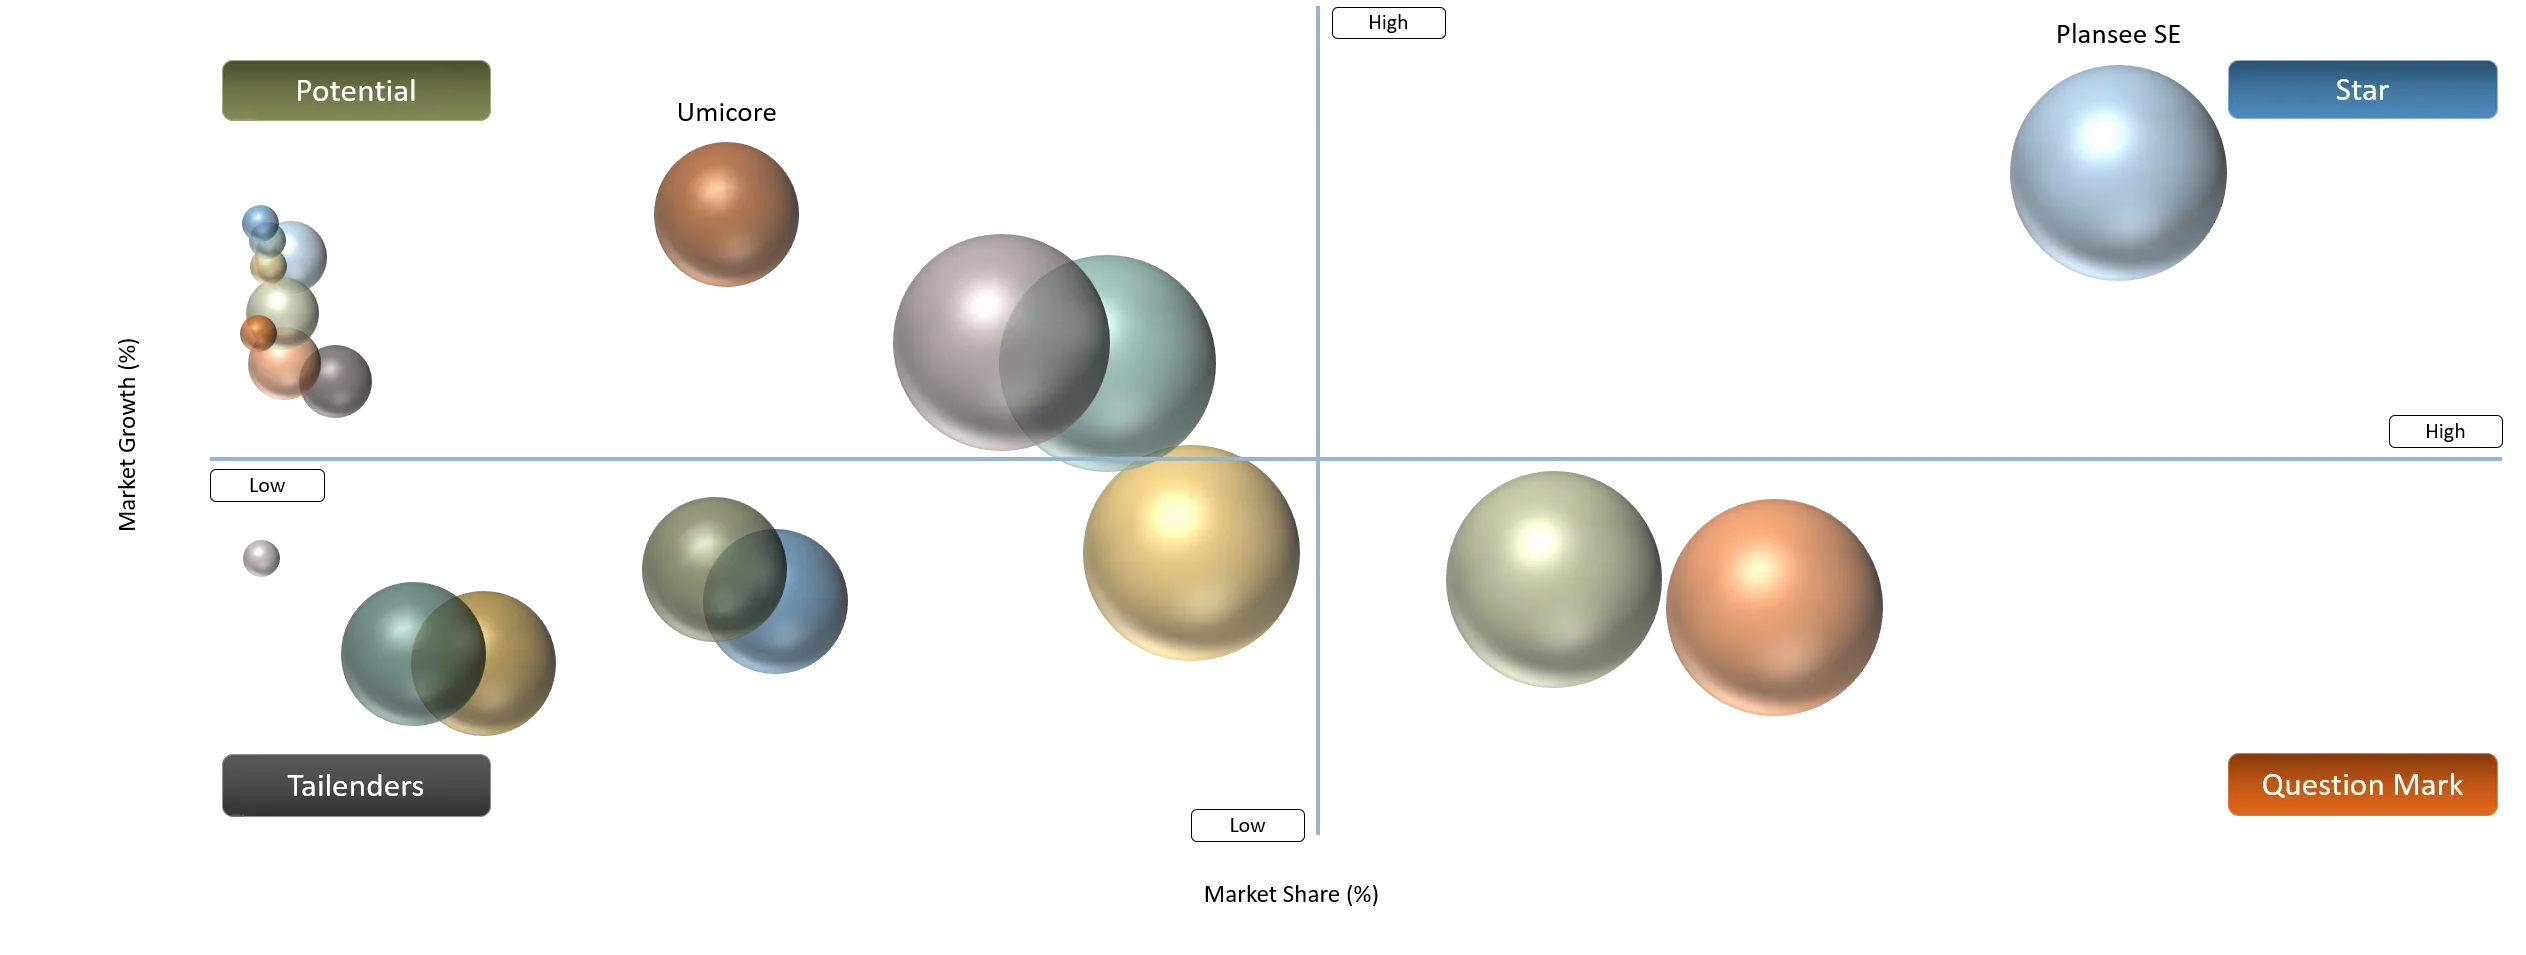
Stars include Plansee SE, H.C. Starck Tungsten GmbH, and Masan High-Tech Materials because of their strong positions across tungsten powders, tungsten carbide, refractory metals, and advanced tungsten-based components, combined with established production capabilities and exposure to high-growth applications such as semiconductors, aerospace, defense, electronics, and precision tooling. Question Marks include Buffalo Tungsten Inc., A.L.M.T. Corp, and Gesellschaft für Wolfram Industrie mbH, which have established capabilities in tungsten products and specialized materials but operate in a market where larger integrated producers have stronger global reach and broader product portfolios.
The Potential category includes Umicore, ATI (Allegheny Technologies Incorporated), and BETEK GmbH & Co. KG, which benefit from growing demand for tungsten-containing materials, wear-resistant products, specialty alloys, and advanced industrial components but have comparatively more diversified portfolios beyond tungsten-based materials. Tailenders include Nippon Tungsten Co., Ltd., reflecting its comparatively specialized exposure to tungsten-related applications and smaller global footprint relative to the leading diversified tungsten-material producers.
Tungsten-Based Materials Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Rising defense and aerospace demand is increasing the use of tungsten-based materials. | 24% | High – Defense & aerospace, particularly North America, Europe and Asia-Pacific | Armor-piercing systems, aircraft ballast/counterweights, missile and defense components, high-temperature aerospace components, radiation shielding | Defense procurement and national stockpiling are increasing demand for tungsten heavy alloys, tungsten carbide and high-performance tungsten materials while encouraging non-Chinese supply-chain development. |
Growing semiconductor and electronics manufacturing is driving demand for tungsten materials used in high-performance and high-temperature applications. | 21% | High – Asia-Pacific, especially China, Taiwan, South Korea and Japan | Semiconductor contacts/vias, sputtering targets, electrodes, heat-resistant components, electronic interconnects and advanced chip manufacturing | Semiconductor miniaturization and higher-temperature processing increase the need for high-purity tungsten and tungsten-based components. |
Expansion of tungsten carbide cutting and wear-resistant tools is supporting consumption across machining, mining, construction, and industrial manufacturing. | 27% | Very High – Mining, construction, machining and industrial manufacturing globally | Cutting inserts, drills, milling tools, mining bits, drilling tools, wear parts and industrial tooling | Tungsten carbide remains one of the most established high-volume applications because its hardness and wear resistance extend tool life in demanding operations. |
Increasing investment in critical-mineral supply-chain security is accelerating domestic tungsten mining, refining, recycling, and material production outside China. | 28% | High – North America and allied supply chains; expanding in Europe and other resource regions | Tungsten mining, APT/powder production, recycling, tungsten carbide production, heavy alloys and strategic stockpiling | Supply-chain diversification is shifting investment toward domestic and allied tungsten production and recycling. |
Rising defense and aerospace demand is increasing the use of tungsten-based materials
The expansion of defense procurement and aerospace activities has created greater need for tungsten-based materials due to the properties of tungsten, which include extremely high density, hardness, abrasion resistance, and high-temperature capability, making it ideal for use in armor-piercing rounds, ballast, missiles, aerospace equipment, and high-temperature applications. In April 2025, as per the European Commission, tungsten is a major defense metal used in ammunition, high-strength applications, and supersonic and hypersonic aircraft, whereas the FY2026 defense budget of the U.S. Department of Defense has requested continued funding for missile and ammunition systems, such as 534 AMRAAMs, 139 SM-6 missiles, 238 LRASMs, and 57 Tomahawks.
Defense applications are becoming a major growth engine for tungsten demand as rising military procurement and stockpile replenishment increase the need for high-performance, dense, and heat-resistant materials. In April 2026, according to the Reuters reported that defense-sector tungsten demand is growing at about 8% annually, and if this trend continues, defense could overtake automotive as the largest tungsten-consuming sector by the mid-2030s. The same report noted that APT prices in Rotterdam had exceeded USD 3,000 per metric ton, representing an increase of more than 200% since the beginning of 2026, reflecting the combined impact of tightening Chinese export controls and surging military demand.
Tungsten-Based Materials Market Segment Analysis
The global tungsten-based materials market is segmented based on product, form, application, end-user, and region.
Tightening Tungsten Supply and Rising Raw-Material Costs Supporting Cutting Tool Demand
The cutting tools segment dominates the application of the tungsten-based materials market, with a market share of 40% in 2025. The segment gains advantages because of the wide usage of tungsten carbide in heavy-duty machining, drilling, milling, turning, and wear-resistant tools, as the hardness and heat resistance of the material allow for an extended life of tools. In June 2025, according to Kennametal, tungsten carbide is the key material used by the company for metal-cutting and extremely tough wear applications and is used in milling, hole making, turning, threading, and toolmaking across transportation, aerospace, energy, and general engineering industries.
The growing importance of tungsten-based cutting tools is being emphasized through reduced availability of the raw materials and increased industry demands as well. In January 2026, according to Reuters, tungsten is extensively employed in manufacturing cutting tools and wear parts in the industries of manufacturing, mining, and construction, as well as in aerospace, defense, industrial gas turbines, and electronics. The prices for ammonium paratungstate (APT) touched a record level of USD 1,125 to 1,150 per metric ton in China and USD 1,100 per metric ton in Rotterdam. Reuters further said that the tungsten mining quota in China was decreased by 6.5% annually in 2025, whereas only 15 Chinese companies were permitted to export tungsten in December 2025.
Tungsten-Based Materials Market Geographical Penetration
Rapid Expansion of Battery Material Manufacturing and Integrated Supply Chains Strengthens Asia-Pacific's Market Leadership
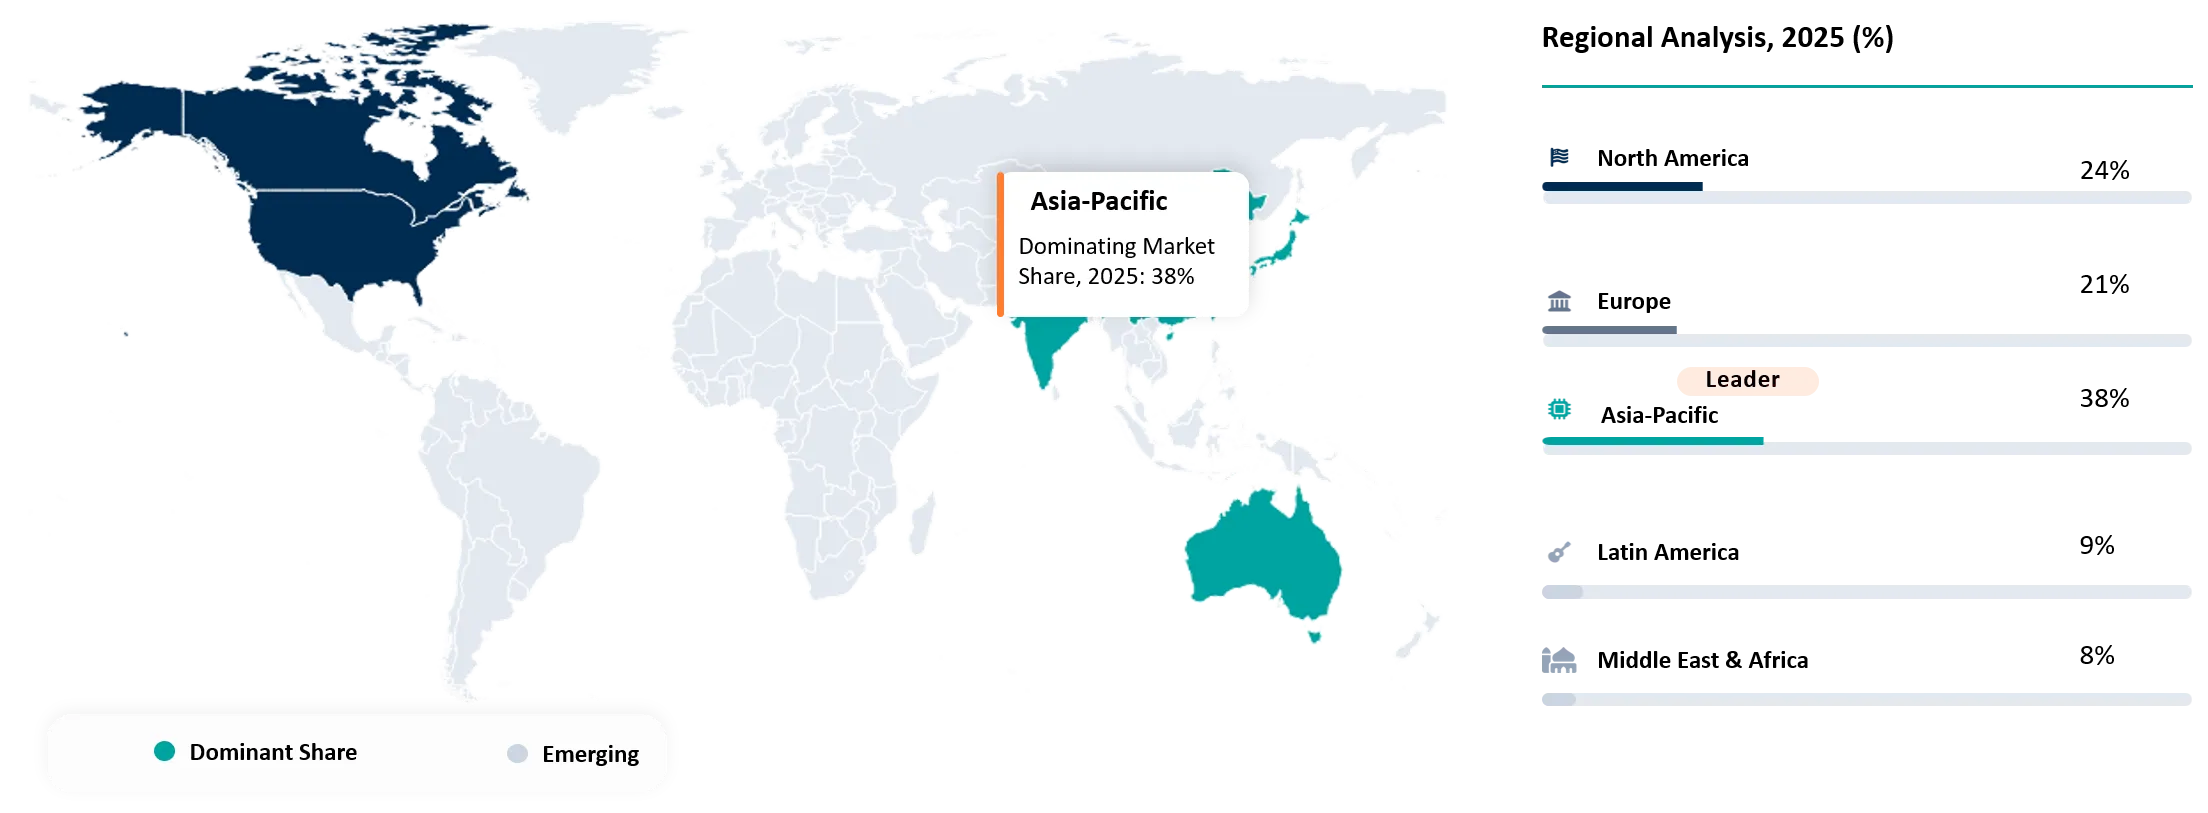
The Asia-Pacific region dominates the tungsten-based materials market, accounting for approximately 38% of the global market in 2025, supported by its highly concentrated tungsten mining, processing, manufacturing, and downstream industrial base. The region benefits particularly from China’s dominant position in global tungsten production, alongside strong demand from electronics, automotive, mining, construction, and advanced manufacturing industries across China, Japan, South Korea, and Southeast Asia.
The acquisition strengthens Asia-Pacific’s tungsten-based materials manufacturing and recycling capabilities. In March 2026, Hyperion Materials & Technologies, a U.S.-based advanced materials company, announced an agreement to acquire Electronica Tungsten Ltd., an India-based tungsten carbide manufacturer and an industrial and engineering conglomerate. Electronica Tungsten operates four manufacturing facilities and produces tungsten carbide powders, wear parts, sintered blanks, and ready-to-press powders, while also processing tungsten ore concentrates and recycling hard and soft tungsten scrap.
China Tungsten-Based Materials Market Trends
China holds a dominant position in the Asia-Pacific tungsten-based materials market because of its exceptionally large tungsten mining base, processing facilities, and downstream manufacturing facilities in the country. The country backs the manufacturing of tungsten concentrates, powder, tungsten carbide, alloys, and other added-value products utilized in a wide range of industries.
China’s tungsten resource consolidation is strengthening domestic supply security for downstream tungsten-based materials. In August 2026, Xiamen Tungsten Co., Ltd., a China-based tungsten and non-ferrous metals producer, announced plans to invest approximately RMB 593 million (USD 88.37 million) to acquire a 30.17% stake in Jiangxi Jutong Industrial Co., Ltd., a China-based mining and mineral-processing company involved in the Dahutang tungsten project in Jiangxi Province. The transaction provides Xiamen Tungsten with greater access to the Dahutang tungsten mine, which holds approximately 1.38 million tonnes of tungsten resources, strengthening its domestic raw-material supply for downstream tungsten products and materials.
Japan Tungsten-Based Materials Market Outlook
Japan is one of the major countries in the Asia-Pacific tungsten-based materials market due to its state-of-the-art manufacturing base, its precision engineering skills, and its demand for high-quality materials in electronics, automobiles, industrial machinery, and cutting tools. Japan’s exposure to developments in the tungsten supply chain is significant since the nation depends heavily on tungsten imports.
Japan is strengthening its domestic tungsten supply chain through recycling and localized intermediate-material production. In September 2026, Mitsubishi Materials Corporation, a Japan-based non-ferrous metals and advanced materials manufacturer, announced plans to invest approximately JPY 8 billion (about USD 52 million) to expand tungsten recycling capacity at its subsidiary Japan New Metals Co., Ltd., a Japan-based tungsten materials and recycling company. The project at the Akita plant in Japan is supported by a JPY 2 billion (USD 12.9 million) subsidy from Japan’s Ministry of Economy, Trade and Industry (METI) and is expected to double ammonium paratungstate (APT) production capacity to 2,400 tonnes per year, strengthening domestic tungsten recycling and the supply of tungsten powder and tungsten carbide materials.
North America’s Strategic Supply-Chain Expansion and Defense Demand Strengthening Tungsten-Based Materials Market
North America is a major region in the tungsten-based materials market, accounting for approximately 24% of the global market in 2025, supported by strong demand from aerospace and defense, advanced manufacturing, electronics, energy, and industrial applications. The region is increasingly strengthening its position through domestic tungsten processing and allied sourcing initiatives as manufacturers seek to reduce exposure to concentrated Asian supply.
The U.S. is accelerating domestic tungsten mining and processing to strengthen critical-material supply-chain resilience. In September 2026, Blue Moon Metals Inc., a Canada-based mining and metals development company, The Elmet Group, a U.S.-based advanced materials and precision-engineered components manufacturer, and EQ Resources Limited, an Australia-based tungsten mining and processing company, announced a USD 150 - 175 million investment in the Springer Tungsten Complex in Nevada, U.S. The investment includes a USD 75 million capital injection into a joint venture to develop an APT plant, targeting 4,000 tonnes of APT capacity annually, while the mine and mill are expected to return to production in Q4 2027 and the APT plant in H2 2028.
U.S. Tungsten-Based Materials Market Trends
The U.S. is the dominant country in the North American tungsten-based materials market, supported by strong demand from aerospace and defense, precision manufacturing, electronics, energy, and industrial tooling. The country is increasingly focused on building a domestic tungsten ecosystem as reliance on overseas supply creates strategic risks for critical applications.
The U.S. is strengthening its domestic tungsten oxide supply through strategic reserves and expanded processing capacity. In May 2026, Plansee Group, an Austria-based advanced materials and powder-metallurgy company, and Manhattan Five Partners, a U.S.-based infrastructure and strategic-asset investment firm, announced a collaboration to establish a strategic tungsten oxide reserve in the United States. Plansee plans to expand tungsten oxide production at its Global Tungsten & Powders (GTP) facility in Towanda, Pennsylvania, to approximately 12,000 tonnes per year, with initial deliveries expected in 2026; a significant share will support U.S. government, defense, and critical-industry demand.
Tungsten-Based Materials Market Competitive Landscape
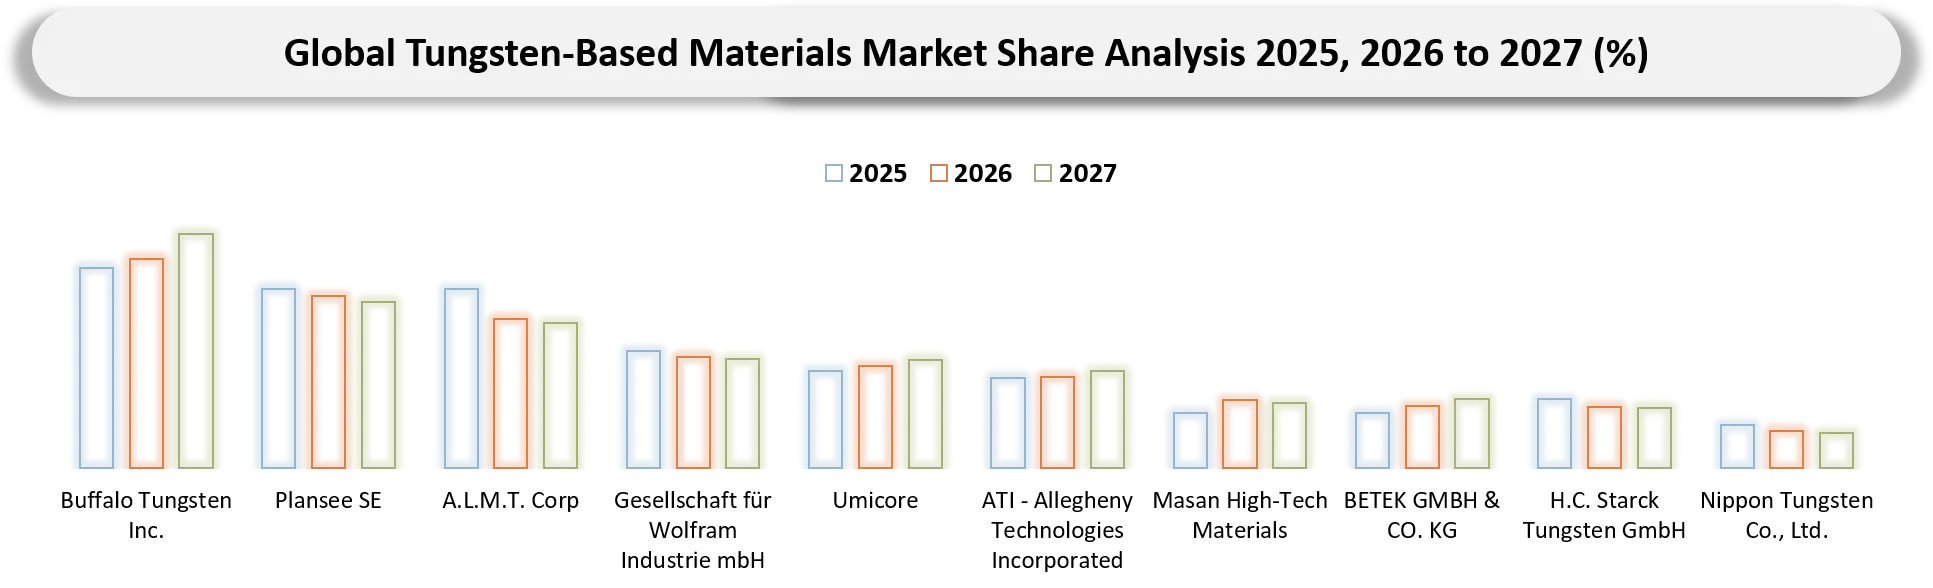
- The tungsten-based materials market is characterized by three major participant groups: integrated tungsten producers and processors, advanced tungsten-material and powder-metallurgy specialists, and downstream tungsten-carbide or tooling manufacturers. Masan High-Tech Materials, Plansee SE, and H.C. Starck Tungsten GmbH are positioned across tungsten refining, powders, chemicals, recycling, and advanced materials, while A.L.M.T. Corp., Gesellschaft für Wolfram Industrie, and Buffalo Tungsten specialize in high-purity tungsten products, powders, rods, wires, and fabricated materials. BETEK GmbH & Co. KG, Nippon Tungsten, and ATI strengthen the downstream landscape through carbide tooling, specialty tungsten products, and high-performance materials for aerospace and defense. The market remains highly fragmented, and company-level market shares are generally not publicly disclosed, making revenue and production indicators more appropriate for comparing competitive scale.
- Key players include Buffalo Tungsten Inc. (United States), Plansee SE (Austria), A.L.M.T. Corp. (Japan), Gesellschaft für Wolfram Industrie mbH (Germany), Umicore (Belgium), ATI – Allegheny Technologies Incorporated (United States), Masan High-Tech Materials (Vietnam), BETEK GmbH & Co. KG (Germany), H.C. Starck Tungsten GmbH (Germany), and Nippon Tungsten Co., Ltd. (Japan).
Key Developments
- August 2026: Hiroshima University, a Japan-based national research university, and researchers from Mitsubishi Materials Hardmetal Corporation, a Japan-based tungsten carbide and hard-materials manufacturer, demonstrated a hot-wire laser additive-manufacturing method for producing tungsten carbide–cobalt (WC–Co) cemented carbide.
- June 2026: Tivan Limited, an Australia-based critical-minerals exploration and development company, agreed key terms for a joint venture to advance its Molyhil Tungsten-Molybdenum Project in Australia’s Northern Territory with Sumitomo Corporation, a Japan-based general trading and investment company, and ETFS Capital, an Australia-based investment company.
- September 2026: Almonty Industries Inc., a U.S.-based tungsten mining and processing company, entered into a strategic partnership with the Government of Rwanda, a national government entity, to develop and process tungsten in Rwanda.
- October 2025: China Minmetals Corporation, a China-based state-owned metals and mining group, and China Tungsten & Hightech Materials Co., Ltd., a China-based tungsten and advanced hard-materials producer, held a tungsten industry-chain collaborative development conference in Zhuzhou, Hunan.
- January 2026: AMERMIN, a U.S.-based critical-minerals recycling and refining company, received a USD 11.5 million U.S. Department of Energy (DOE) grant to scale its critical-mineral processing operations.
- March 2026: Iris Acquisition Corp II, a Cayman Islands-based special purpose acquisition company (SPAC), signed a non-binding letter of intent with American Tungsten & Antimony Ltd. (AT4), an Australia-based critical-minerals exploration and development company, to form Freedom Metals Corporation, a U.S.-focused antimony and tungsten platform.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organizations procuring tungsten-based materials increasingly prioritize suppliers that can provide consistent-quality tungsten metal, tungsten carbide, powders, alloys, and chemicals with the purity, particle size, hardness, density, and dimensional specifications required for demanding industrial applications.
- The procurement decision is increasingly influenced by supply-chain security, availability of non-Chinese sources, production capacity, and long-term supply agreements, particularly as export restrictions and geopolitical risks increase concerns over tungsten availability.
- Buyers evaluate suppliers based on material quality and performance, including hardness, wear resistance, thermal stability, density, corrosion resistance, purity, consistency between batches, and the ability of tungsten-based materials to perform under high-temperature and high-stress operating conditions.
Why Choose DataM?
- Technological Innovations: Explores advancements in tungsten-based materials, including high-performance tungsten alloys, tungsten carbide, high-purity powders, refractory tungsten products, advanced composites, and additive manufacturing technologies, highlighting their role in aerospace, defense, semiconductors, electronics, energy, and precision manufacturing.
- Product Performance & Market Positioning: Evaluates tungsten-based materials according to hardness, density, thermal stability, wear resistance, purity, strength, machinability, and dimensional precision, highlighting how leading suppliers differentiate their products for cutting tools, radiation shielding, aerospace components, electronics, and industrial applications.
- Real-World Evidence: Highlights the adoption of tungsten carbide in cutting and drilling tools, tungsten heavy alloys in defense and aerospace systems, high-purity tungsten in semiconductor manufacturing, and tungsten materials in medical radiation shielding, demonstrating their contribution to durability, thermal performance, precision, and operational reliability.
- Market Updates & Industry Changes: Tracks developments in tungsten mining, refining, powder and carbide production, recycling, supply-chain localization, export controls, and critical-mineral investments across Asia-Pacific, North America, and Europe, providing insight into changes in global material availability and procurement strategies.
- Competitive Strategies: Analyzes how leading companies strengthen their positions through vertical integration, new mining and processing capacity, recycling, advanced material development, strategic partnerships, and expansion into high-value applications such as defense, aerospace, semiconductors, automotive, and advanced tooling.
- Pricing & Market Access: Examines tungsten price movements and their impact on procurement decisions, while assessing cost differences across tungsten metal, carbide, powders, alloys, and specialty products, together with supplier availability, geographic sourcing, long-term contracts, recycling channels, and downstream distribution networks.
- Market Entry & Expansion: Identifies opportunities created by non-Chinese supply-chain development, critical-mineral policies, tungsten recycling, semiconductor demand, defense procurement, advanced manufacturing, and high-performance cutting tools, while outlining strategies such as localized production, secure raw-material sourcing, technology differentiation, and strategic partnerships for global expansion.
Target Audience 2026
- Tungsten & Tungsten Carbide Manufacturers
- Mining & Raw Material Suppliers
- Cutting Tool & Industrial Tool Manufacturers
- Aerospace & Defense Companies
- Semiconductor & Electronics Manufacturers
- Automotive & Transportation Manufacturers
- Medical & Healthcare Equipment Manufacturers



























































