Refrigerant Market Size and Overview
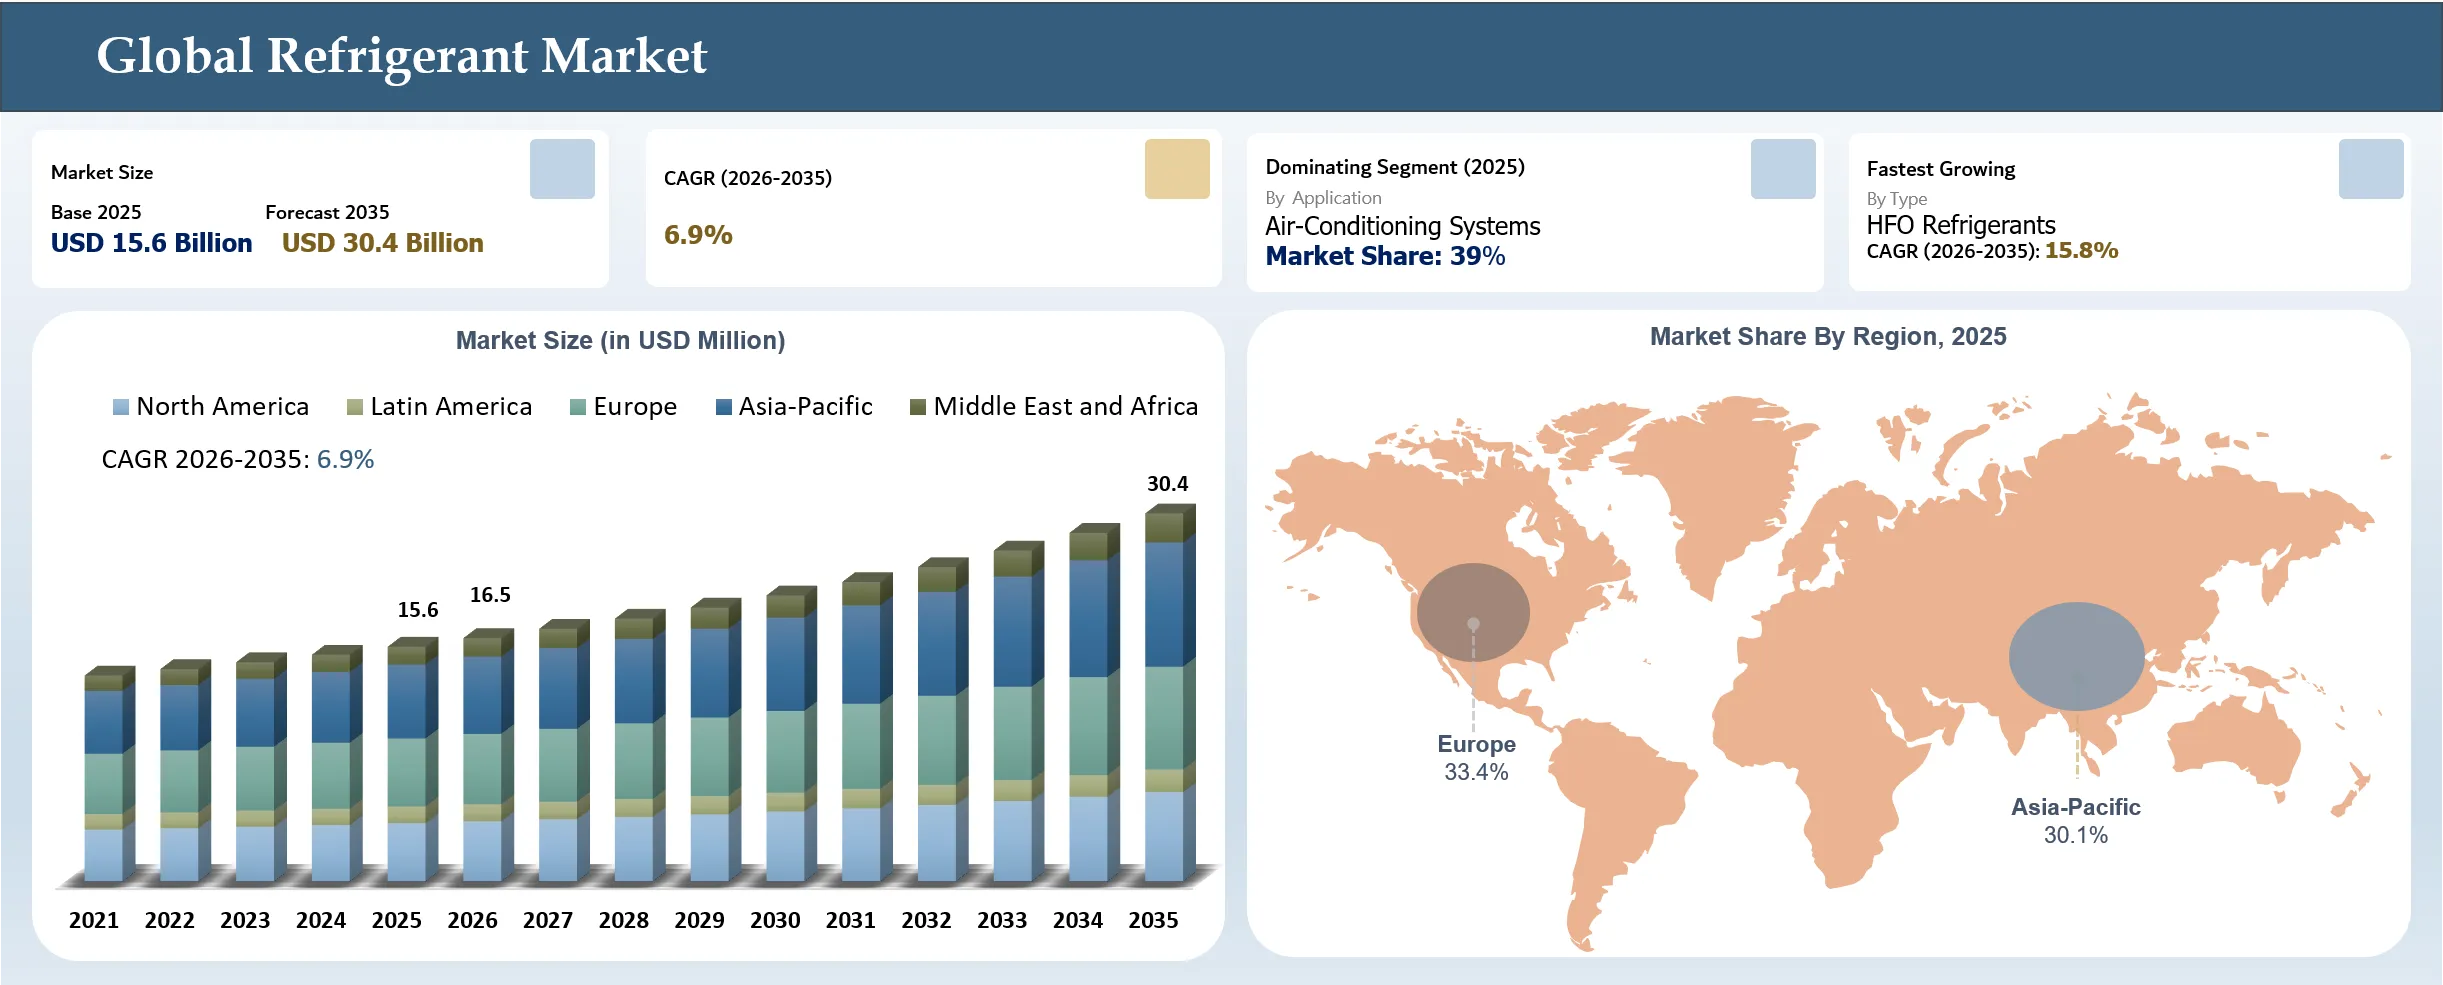
The refrigerant market is projected to reach USD 30.4 million by 2035 from USD 15.6 million in 2025, at a CAGR of 6.9%. The refrigerant market is driven by the replacement of high-global-warming-potential (GWP) refrigerants, rising demand for air conditioning and refrigeration, expansion of cold-chain infrastructure, and technological advances in low-GWP refrigerants. Regulations targeting hydrofluorocarbons (HFCs) are encouraging manufacturers and equipment operators to shift toward lower-GWP refrigerants, including ydrofluoroolefins (HFOs), hydrocarbons and carbon dioxide. In October 2026, Arkema launched Forane 516A, a low-GWP HFO refrigerant blend replacing R-134a, with a GWP below 150 for HVAC, refrigeration, data center cooling, and heat pump applications.
Refrigerant Market Key Takeaways
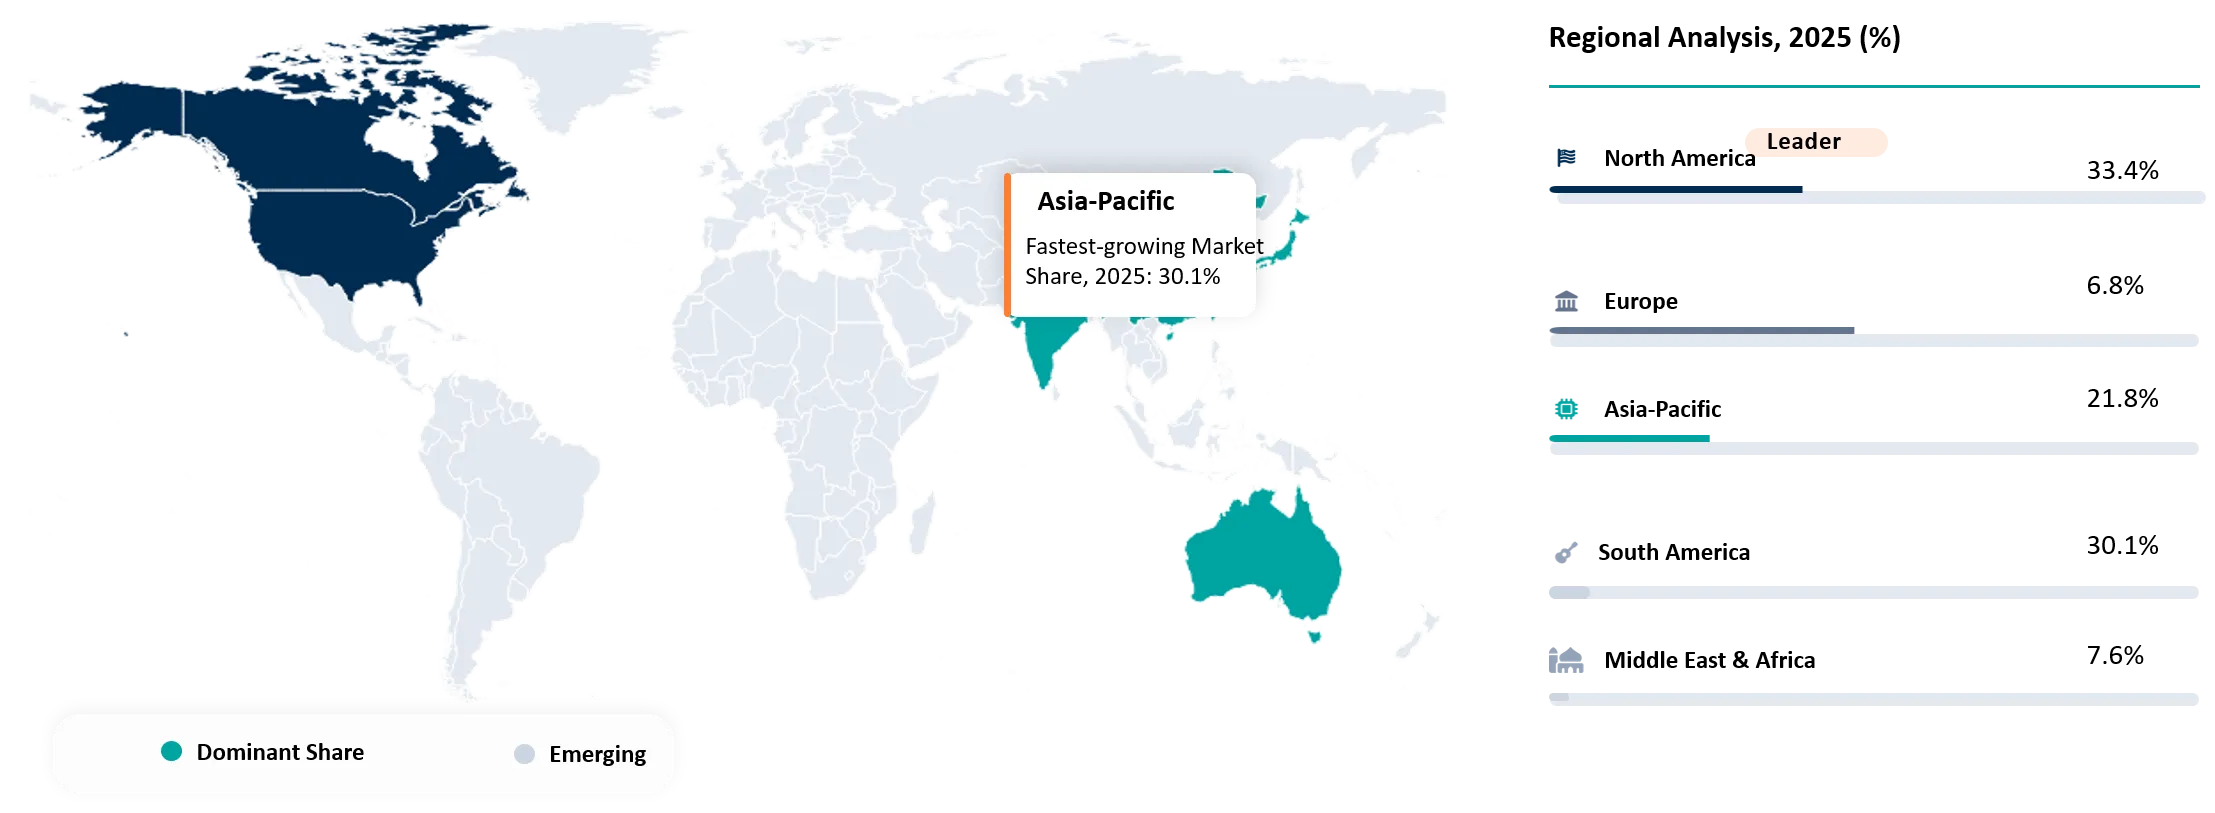
- North America accounted for 33.4% of the global refrigerant market in 2025, supported by demand for air-conditioning systems, regulatory transitions toward lower-GWP refrigerants, and expanding cooling requirements.
- Air-conditioning systems represented the dominant application segment, with a 39% market share in 2025, driven by residential and commercial cooling demand.
- HFO refrigerants are projected to be the fastest-growing type segment, with a 15.8% CAGR from 2026 to 2035, supported by the shift toward refrigerants with lower global-warming potential.
- In October 2025, Vertiv expanded its North American data-center cooling portfolio with low-GWP refrigerant options. Its CoolPhase Perimeter systems use R-454B, while CoolPhase Row and Wall systems use R-32, supporting regulatory compliance and demand for lower-GWP cooling solutions.
Refrigerant Market Trends & Disruptions Impacting Customers
The global refrigerant market is moving from refrigerants with high global warming potential (GWP) towards those with lower GWP owing to increasingly stringent regulations, schedules for phasing down of HFCs, and the need for efficient cooling systems. Suppliers are developing a range of refrigerants like R-32, R-454B, and R-290 for air conditioners, refrigerators, chillers, and heat pumps. The shift calls for redesigning systems and handling procedures to cope with new refrigerant characteristics.
The transition is impacting consumers of refrigerants manufacturers, who include HVAC systems manufacturers, refrigeration systems manufacturers, automobile manufacturers, contractors, and servicing organizations. Regulations, cost variability in refrigerants, shortage of supply, and equipment compatibility issues affect costs of purchasing, research and development, installation, and servicing. Consumers have to evaluate availability of refrigerants, their classification in terms of flammability, training of technicians, and re-design of equipment.
Refrigerant Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) |
| Regulatory Phase-Down of High-GWP Refrigerants and Adoption of Low-GWP Alternatives | 35% |
| Growing Demand for Air Conditioning and Heat Pump Systems | 30% |
| Expansion of Cold-Chain Infrastructure and Commercial Refrigeration | 20% |
Growing Demand for Refrigerants in Commercial Refrigeration Applications
Increases in food processing, supermarkets, transportation of perishable foods, pharmaceuticals, and temperature-controlled transport have led to increased demand for reliable refrigeration. This creates demand for refrigerants in use in commercial display units, industrial chillers, cold rooms, and refrigerated transport.
According to the European Commission, the refrigerants being increasingly adopted in commercial refrigeration, which include supermarket and independent coolers, are R-744 (carbon dioxide), R-290 (propane), and R-600a (isobutane).
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) |
| Stringent HFC Quota Restrictions and Rising Refrigerant Costs | 35% |
| High Costs of Transition to Low-GWP Refrigerants | 30% |
| Safety Concerns Associated with Flammable Alternative Refrigerants | 20% |
Stringent HFC Quota Restrictions and Rising Refrigerant Costs
The European Union's F-gas Regulation (EU) 2024/573 reduces the amount of hydrofluorocarbons (HFCs) allowable on the European market through a quota system, with a target of reaching a phase-out to zero by 2050. The scarcity of HFCs and the increased prices result in higher costs when it comes to purchasing and maintenance of refrigerant providers, equipment manufacturers and end-users, leading to reduced demand for HFCs and increased costs of operating existing cooling units.
According to the EU quota system, the importers and producers of HFCs placed on the market should have enough quota. Additionally, the importers of refrigeration and air-conditioning equipment pre-charged with HFCs should have quota authorization as well.
Opportunity Impact Analysis
| Opportunity | Market Growth Impact (%) |
| Rising Cooling Demand and Transition to Eco-Friendly Refrigerants in Emerging Markets | 35% |
| Increasing Adoption of Natural and Ultra-Low-GWP Refrigerants | 25% |
Rising Cooling Demand and Transition to Eco-Friendly Refrigerants in Emerging Markets
Rising cooling demand in emerging markets like India offers strong growth potential for the global refrigerant industry. With AC adoption increasing 10–15% annually, driven by heatwaves and rising incomes, demand is set to grow eightfold in 20 years. This trend is straining power grids and driving up high-GWP HFC emissions. Furthermore, India has ratified the Kigali Amendment in an effort to limit the use of HFCs and has launched the India Cooling Action Plan (ICAP), which is aimed at reducing the demand for refrigerants by 25-30%. This makes India emerging market in this transition to eco-friendly cooling technologies.
Challenge Impact Analysis
| Challenge | Market Growth Impact (%) |
| Regulatory Differences Across Countries and Compliance Complexity | 30% |
| Technical Compatibility of Low-GWP Refrigerants with Existing Equipment | 25% |
Regulatory Differences Across Countries and Compliance Complexity
Different regulatory environments in different countries give rise to challenges in manufacturing of products and managing supply chains for refrigerants and air-conditioners. For instance, the US EPA introduced a GWP threshold for residential and light commercial air-conditioning units set at 700 from January 2025, and in the EU, equipment-based refrigerants are regulated through Regulation 2024/573 with different implementation dates. Manufacturers serving both markets must coordinate refrigerant selection, equipment compliance and inventory planning to meet the applicable regional requirements.
Refrigerant Market: Commercial Use Cases Across Industries
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
CHEMOURS
| Uses its Opteon refrigerant portfolio in commercial refrigeration, cold-chain transportation, air conditioning and industrial cooling. In August 2026, Chemours launched Opteon ZE (R-1234ze(E)) and Opteon 515B (R-515B) for stationary chillers serving data centers and commercial buildings. | Provides lower-GWP refrigerant options for high-capacity cooling, supports regulatory transitions and addresses increasing cooling requirements in data centers and commercial facilities. |
| ARKEMA | Supplies Forane refrigerants for HVAC, refrigeration, heat pumps and industrial cooling. In October 2026, Arkema launched Forane 516A, a low-GWP HFO refrigerant blend designed to replace R-134a, with a GWP below 150 for HVAC, refrigeration, data center cooling and heat pump applications. | Offers a lower-GWP alternative to R-134a, supports compliance with refrigerant regulations and enables cooling-equipment manufacturers to address demand for lower-emission thermal management solutions. |
Market Ecosystem
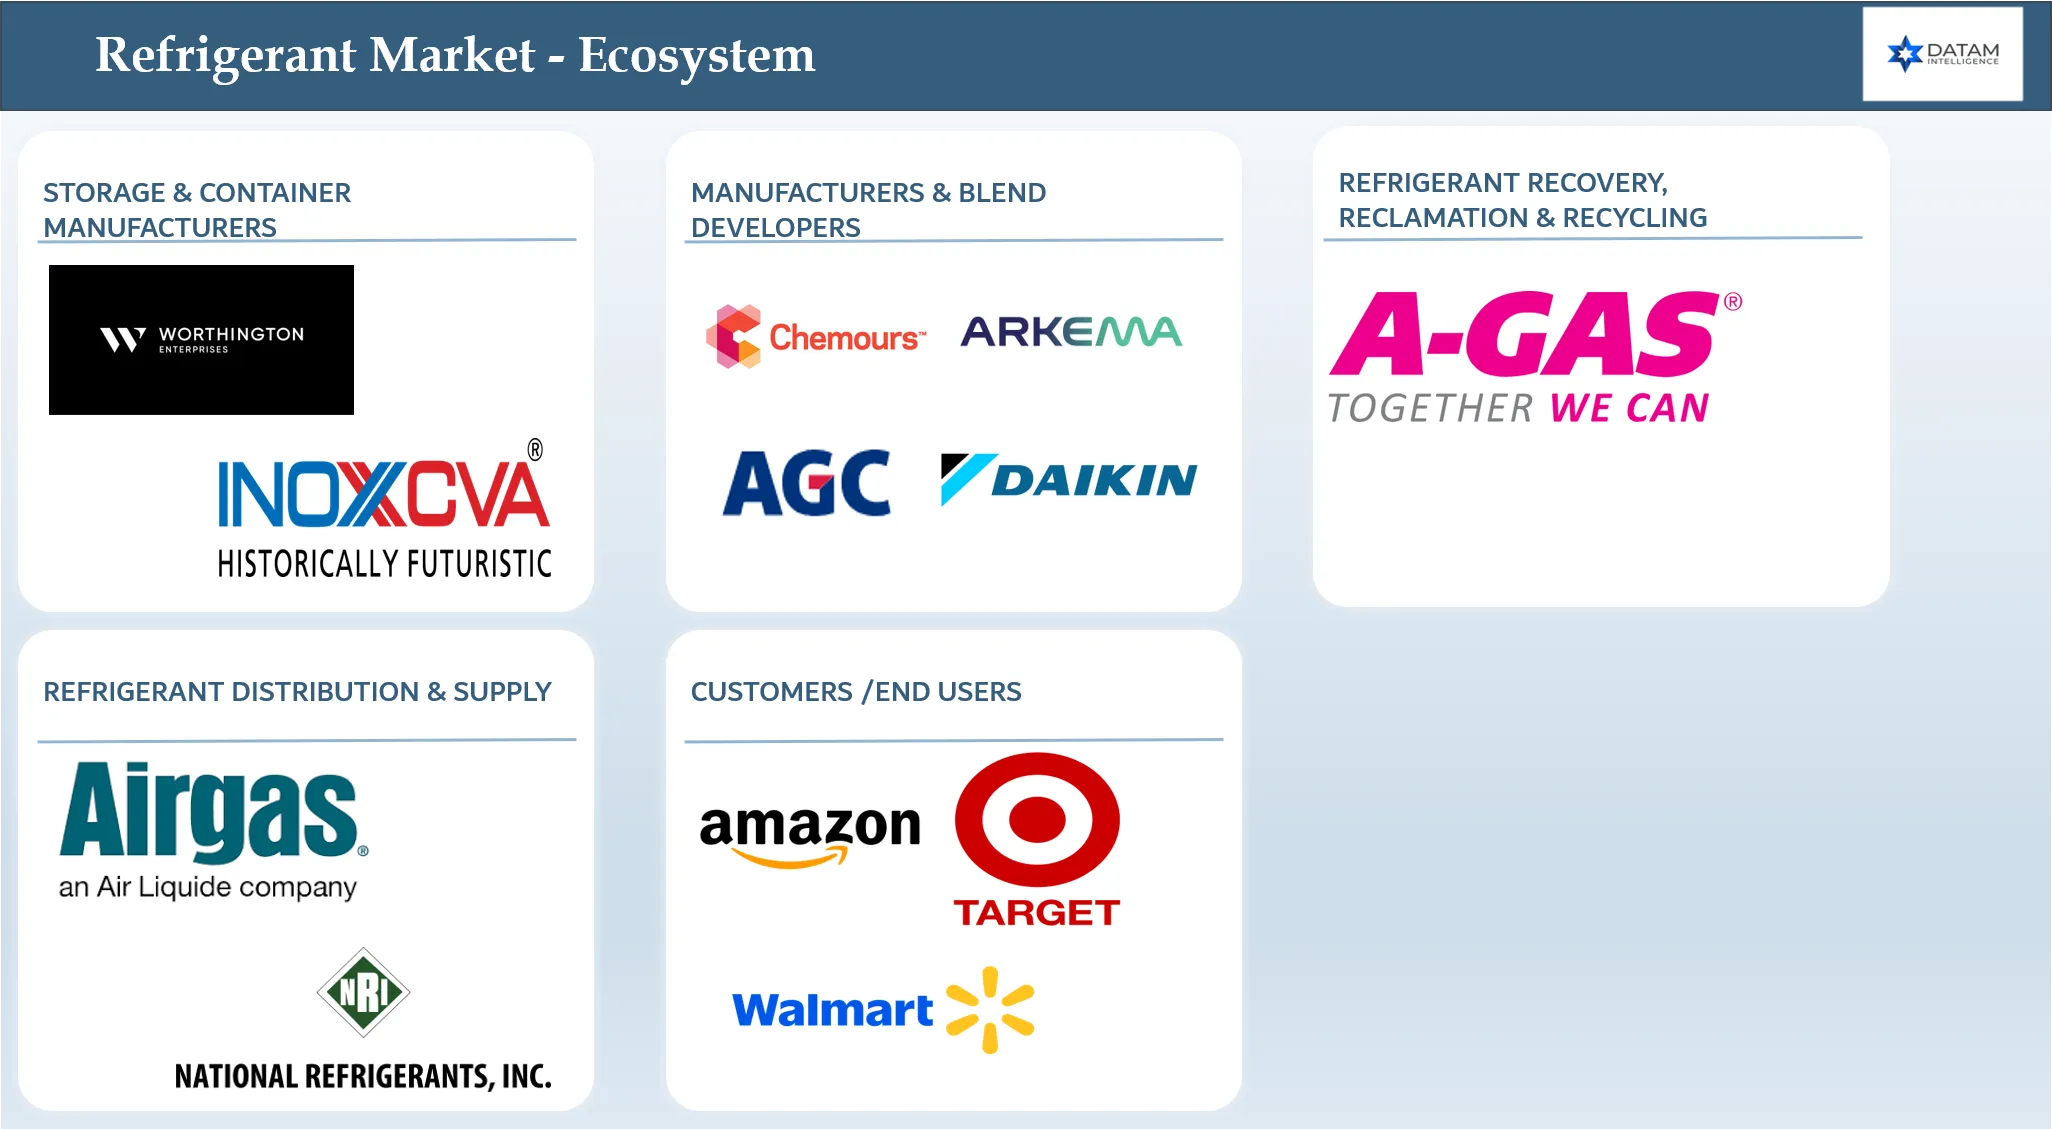
The global refrigerant market ecosystem connects refrigerant manufacturers, fluorochemical producers, cooling-equipment manufacturers, chemical distributors, refrigeration contractors, service providers, and end users across residential and commercial air conditioning, industrial refrigeration, cold-chain logistics, automotive thermal management, heat pumps, and data centers. Major manufacturers include Arkema Group, The Chemours Company, Daikin Industries, Ltd., Orbia Advance Corporation, SRF Limited, AGC Inc., and Dongyue Group.
Developments in products have been moving the ecosystem towards low GWP refrigerants and application-specific cooling. In March 2026, Daikin Industries, Ltd released their line of R-290 (Propane) Heat Pumps & Chillers ranging from 17 KW to 2,000 KW. The range include EWA(Y)K-CZ monoblocs and EWYK-QZ Heat Pumps with safety systems and low GWP refrigerant technology.
Refrigerant Market Segment Analysis
By Type
The refrigerant market, by type, is segmented into CFC, HCFC, HFC, HC, PFC, and HFO refrigerants. CFC and HCFC refrigerants are being phased out or restricted due to their ozone-depletion potential, while HFCs remain widely used but face phasedown measures because of their high global-warming potential. Hydrocarbons and HFOs are gaining use as lower-GWP alternatives in suitable cooling applications. Refrigerant selection depends on cooling performance, energy efficiency, safety requirements, and environmental regulations.
By Application
The refrigerant market, by application, is categorized into refrigeration systems, chillers, air-conditioning systems, mobile air-conditioning systems (MAC), heat pumps, and others. Refrigerants enable temperature control in food storage, commercial and industrial cooling, buildings, and vehicle cabins. Heat pumps and chillers also use refrigerants for space heating, water heating, and data-center cooling. Demand across these applications is influenced by rising cooling needs, cold-chain expansion, and the adoption of energy-efficient heating and cooling equipment.
Refrigerant Market Geographical Penetration
North America’s Shift Toward Low-GWP Refrigerants and Increased Supply Availability
North America dominates the refrigerant market owing to the reduction in HFCs with a higher GWP HFCs, growing need for efficient air conditioners and heat pumps, and increasing cooling needs in commercial buildings and data centers. The move towards more environmentally friendly refrigerants, driven by regulations in the U.S and Canada, is increasing the uptake of refrigerants like R-454B, R-32, and natural refrigerants.
The increase in demand for low GWP refrigerants and the requirement to sustain a constant supply have influenced the North American refrigerant market. In May 2025, Carrier Global Corporation announced measures to increase the availability of R-454B despite its temporary shortages by increasing its supply, shifting it to distributors and also recruiting more refrigerant packagers. The company also increased the pre-charge of the refrigerant in most of their residential ducted split systems to enable 30-foot line sets instead of 15 feet.
Furthermore, in April 2025, Mitsubishi Electric Trane HVAC US LLC launched its line of residential and light commercial heat pump and air conditioning products that utilize R-454B refrigerant, which is around 78% less GWP than R-410A. The new line of products comprises ducted and ductless units, multi-zone units, among others.
Refrigerant Market BCG Matrix: Company Evaluation
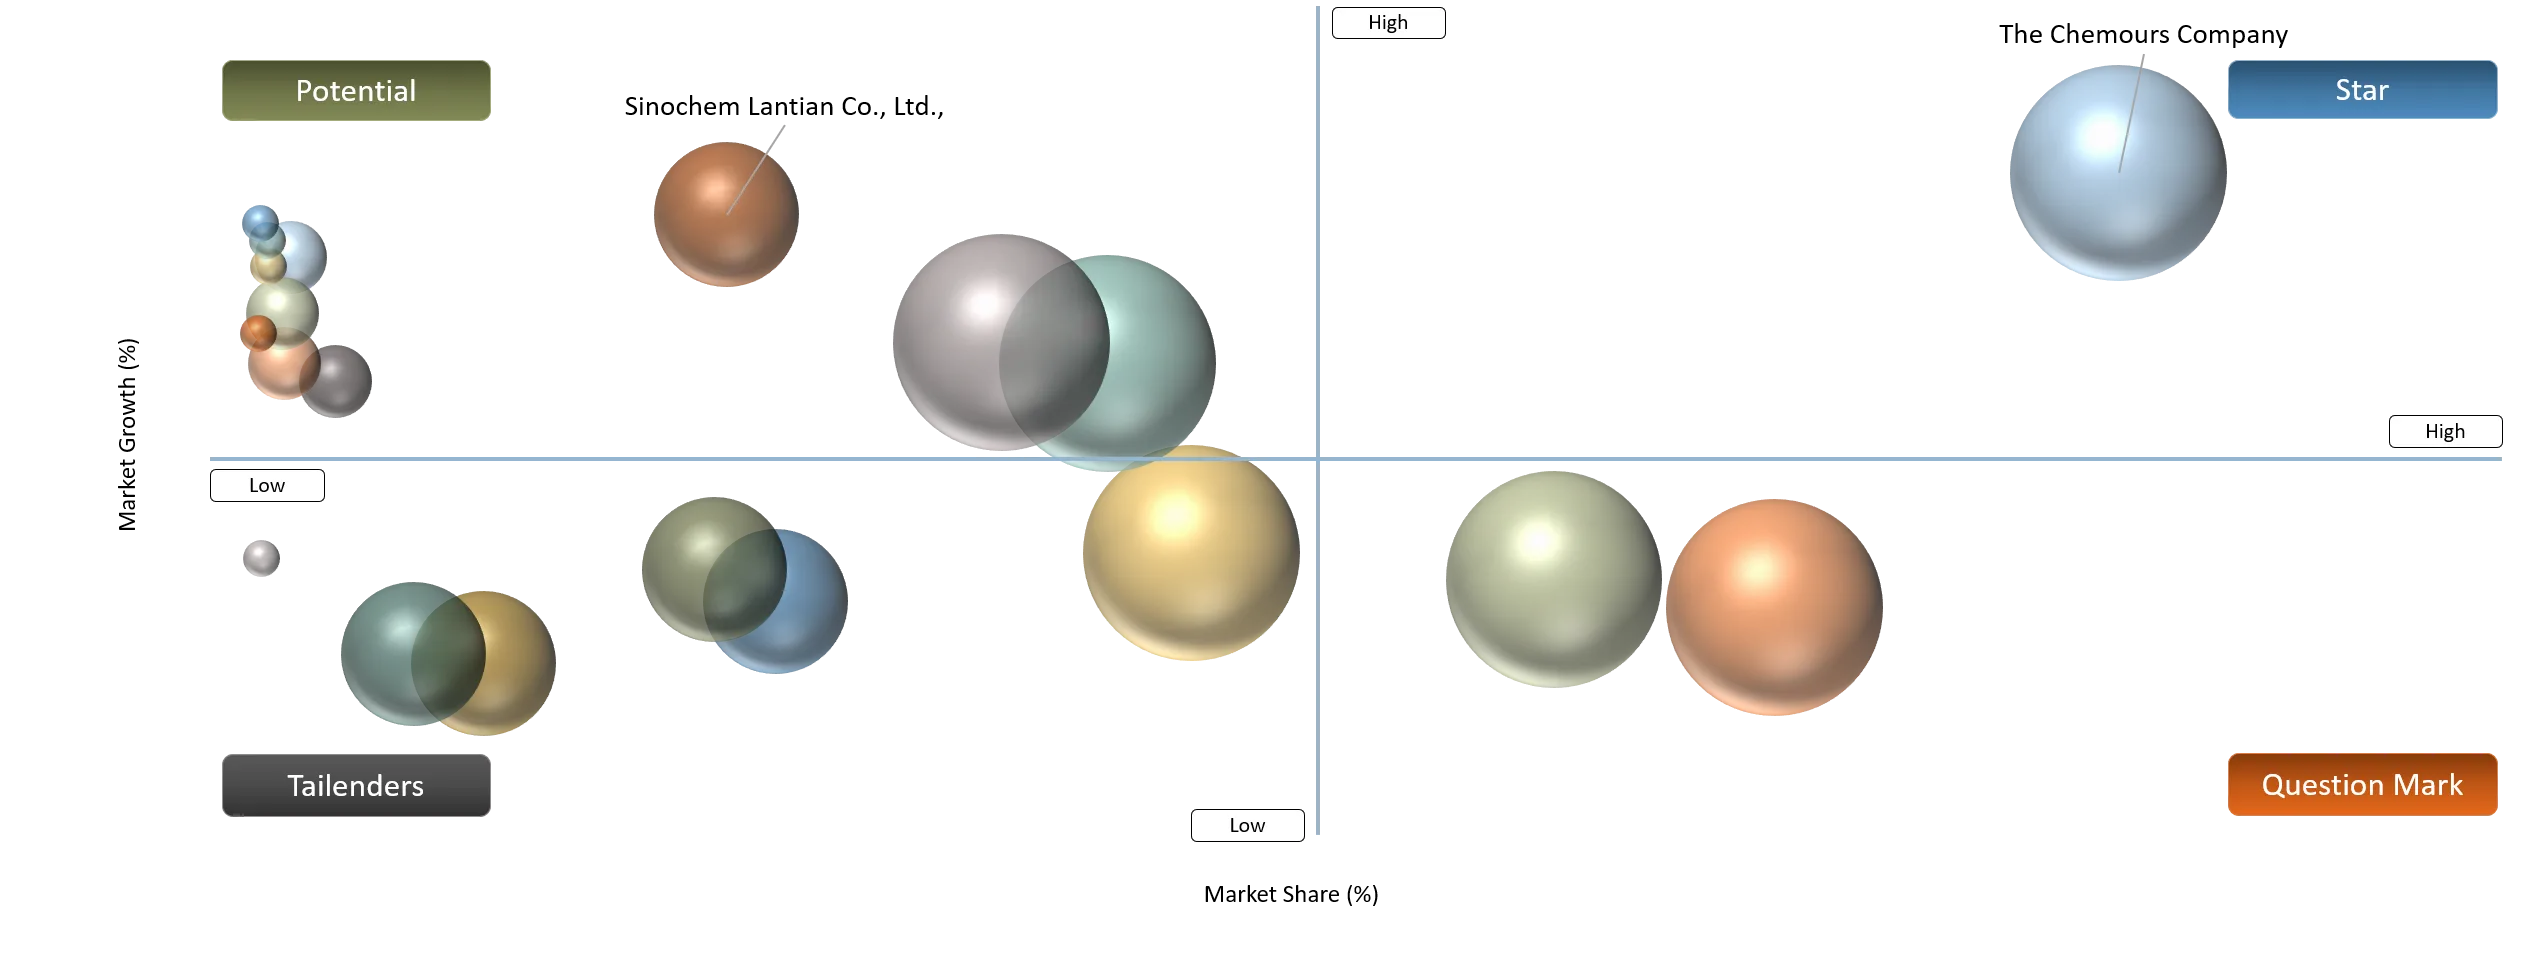
The refrigerant market includes established multinational producers such as The Chemours Company, Solstice Advanced Materials Inc., and Daikin Industries, Ltd., which offer broad refrigerant portfolios and lower-GWP alternatives. Arkema Group, Orbia Advance Corporation, and AGC Inc. maintain established fluorochemical and refrigerant businesses, while Gujarat Fluorochemicals Limited (GFL) strengthens the Indian manufacturer segment with R-22, R-32, R-125, and R-410A products. Sinochem Lantian, Shandong Dongyue Refrigerants, and SRF Limited also contribute through refrigerant manufacturing and fluorochemical capabilities. These BCG placements remain qualitative because comparable refrigerant-specific market-share and growth data are limited.
Refrigerant Market Competitive Landscape
Key Market Players
- Arkema Group
- Daikin Industries, Ltd.
- The Chemours Company
- Orbia Advance Corporation S.A.B. de C.V.
- SINOCHEM LANTIAN CO., LTD. (SINOCHEM GROUP CO., LTD.)
- Shandong Dongyue Refrigerants Co., Ltd. (DONGYUE GROUP)
- Gujarat Fluorochemicals Limited (GFL)
- Solstice Advanced Materials Inc.
- AGC Chemicals Americas (AGC Inc.)
- SRF Limited
Refrigerant Market Scope
| Metrics | Details |
| 2025 Market Size | USD 15.6 Billion |
| 2035 Projected Market Size | USD 30.4 Billion |
| CAGR (2026-2035) | 6.9% |
| Years Considered | 2025 - 2035 |
| Base Year | 2025 |
| Forecast Period | 2025 - 2035 |
| Units Considered | Value (USD Million) |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth |
| Segments Covered | By Type CFC Refrigerants HCFC Refrigerants HFC Refrigerants HC Refrigerants PFC Refrigerants HFO Refrigerant Others By Application Refrigeration Systems Chillers Air-Conditioning Systems Mac (Mobile Air Conditioning System) Heat Pumps Others |
| Region Covered | North America, Europe, Asia-Pacific, Latin America, Middle East and Africa |
Refrigerant Market: Target Audience and Strategic Intelligence Requirements
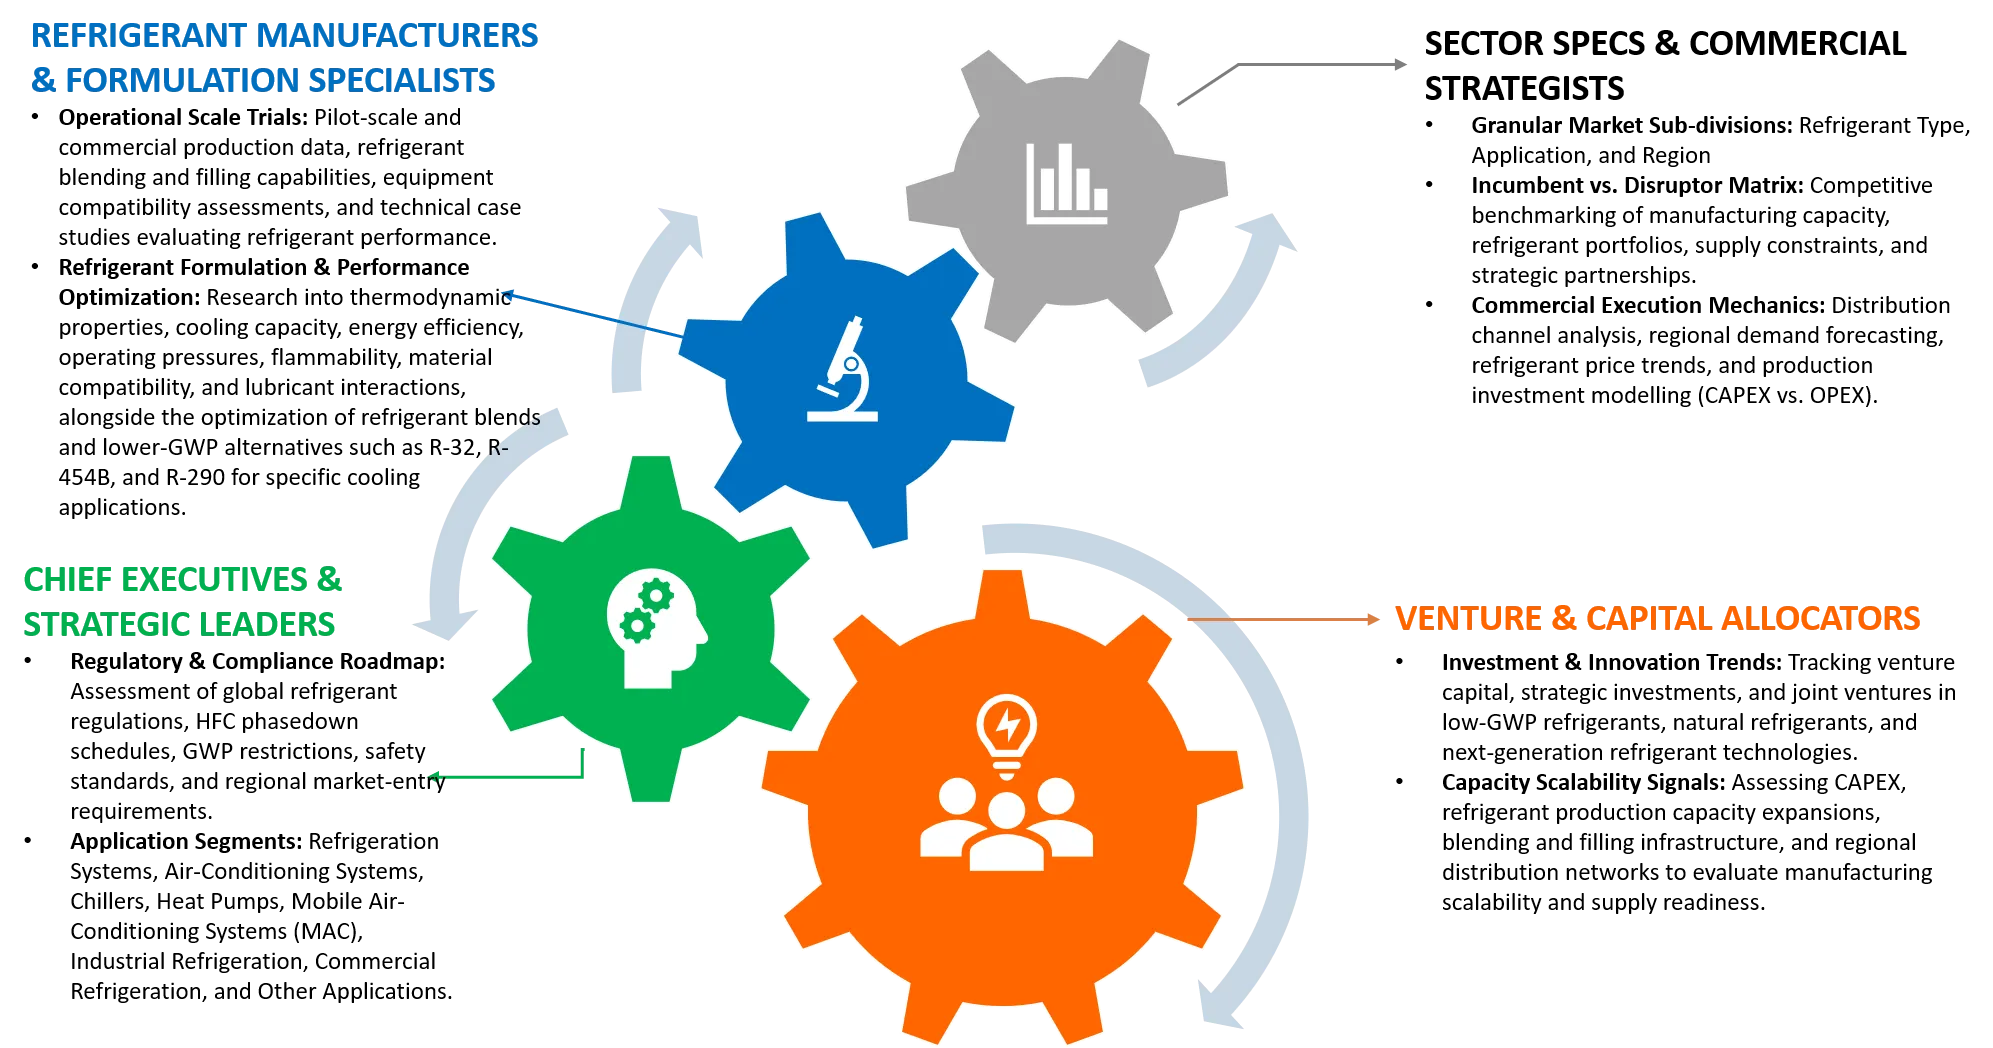
Addressing Client Priorities Through Customized Refrigerant Research
CLIENT REQUIREMENT | RESEARCH CUSTOMIZATION PROVIDED | STRATEGIC VALUE TO CLIENTS |
| Evaluating Global Refrigerant Demand Patterns | Analyzed refrigerant demand across North America, Europe, Asia Pacific, and emerging markets, covering CFC, HCFC, HFC, hydrocarbon, PFC, and HFO refrigerants used in air conditioning, refrigeration, chillers, heat pumps, mobile air conditioning, and industrial cooling. | Enabled clients to align refrigerant portfolios with regional demand, cooling requirements, environmental regulations, HFC phasedown schedules, and the transition toward lower-GWP alternatives. |
| Assessing Refrigerant Regulations and Technology Transitions | Examined regional restrictions, phaseout and phasedown timelines, refrigerant GWP limits, and the adoption of alternatives such as R-32, R-454B, R-290, and other lower-GWP refrigerants across key applications. | Helped clients anticipate regulatory changes, prioritize compliant refrigerant technologies, plan product transitions, and identify growth opportunities in sustainable cooling solutions. |
Key Developments
- October 2026: RF Limited secured regulatory approvals for its planned hydrofluoroolefin (HFO) manufacturing project in Gopalpur, Odisha, with commissioning targeted for the fourth quarter of FY2028. The project includes a planned annual HFO production capacity of 20,000 tonnes and aims to expand domestic manufacturing of next-generation, lower-GWP refrigerants.
- August 2026: Chemours launched Opteon ZE (R-1234ze(E)) and Opteon 515B (R-515B) for stationary chillers used in data centers, commercial buildings, and HVAC applications. The low-GWP refrigerants offer cooling performance for AI-driven data centers, with GWPs of approximately 1 and 293, respectively, and are available in selected markets.
- May 2024: Chemours discontinued U.S. sales of Freon R-404A and R-507 to support regulatory HFC phasedown requirements. The company recommended lower-GWP alternatives, including Opteon XP40 (R-449A) for existing equipment and XL40 (R-454A) and XL20 (R-454C) for new systems.
- October 2026: Arkema announced the commercial availability of Forane 516A, a low-GWP HFO refrigerant blend designed as a replacement for R-134a. With a GWP below 150, A2L safety classification, and zero temperature glide, the refrigerant targets residential and commercial cooling, chillers, commercial refrigeration, data center cooling, and high-temperature heat pumps.