


Polypropylene Battery Separator Market Size and Overview
The global polypropylene battery separator market reached USD 6.53 billion in 2025 and is expected to reach USD 28.31 billion by 2035, growing with a CAGR of 15.8% during the forecast period 2026-2035. The market is being propelled by increasing deployment of lithium-ion batteries across electric vehicles, energy storage systems, and portable devices, wherein polypropylene separators offer electrode insulation, ion mobility, mechanical strength, and dimensional stability. According to Google Patents, the technological advancement indicates an interest in developing thinner, stronger, and heat-resistant PP separator films, as commercial research has shifted its focus from conventional 15 to 25 μm separator films to 7 to 9 μm films and 5 μm-range separator films. Lotte Chemical filed a patent for polypropylene-based materials with superior mechanical and heat resistance characteristics in 2025.
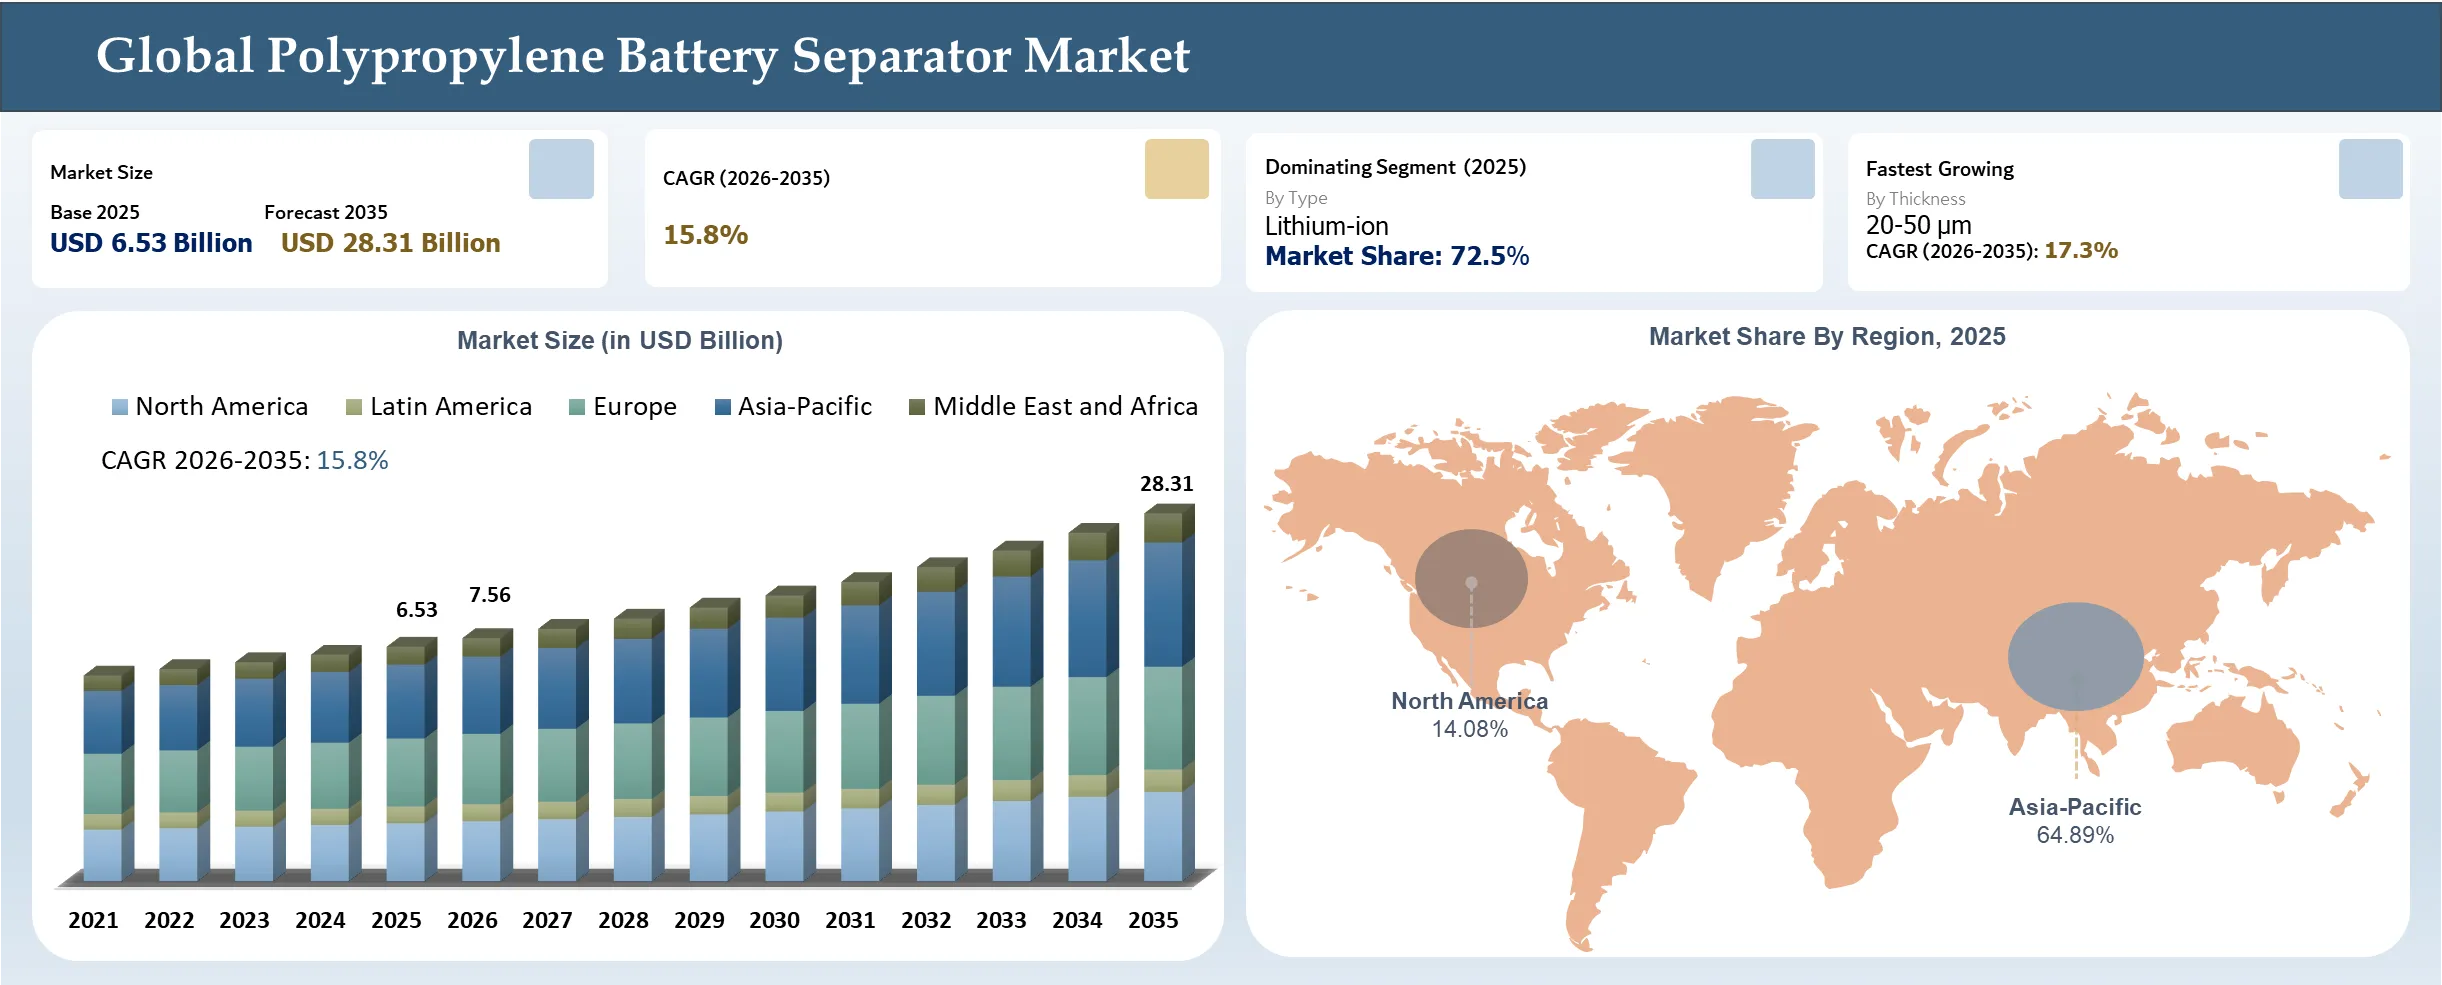
The latest advancements in this sector are geared towards multilayer PP/PE/PP systems, coated separators, pore design, and localized production of separators, which would help resolve the issues of safety and high-energy-density needs. The company Celgard manufactures monolayer PP membranes ranging from 5 μm to 25 μm and trilayer separators made of PP/PE/PP.
White-Space Opportunities for Domestic Lithium-Ion Battery Separator Manufacturing and Supply Chain Expansion
In September 2025, the U.S. Department of Energy (DOE) approved a USD 77.2 million initial disbursement from an up to USD 1.3 billion direct loan to ENTEK Lithium Separators LLC to finance a large-scale lithium-ion battery separator manufacturing facility in Terre Haute, Indiana. The highest investment area is battery separator manufacturing capacity, with the facility planned to produce approximately 1.4 billion m² of coated and uncoated separators after Phases 1 and 2, enough to supply around 1.4 million EVs.
Other investment areas include separator coating and processing, battery-material supply chains, EV battery manufacturing, energy-storage systems, data-centre power infrastructure, industrial utilities, and manufacturing workforce development.
The investment is expected to create significant procurement opportunities across the domestic lithium-ion battery separator value chain. ENTEK Lithium Separators LLC is the primary beneficiary through the development of its Terre Haute, Indiana separator manufacturing facility, while Clayco benefits from plant construction, engineering, and design-build activities.
Brückner Group benefits from supplying biaxial film-stretching equipment used in separator manufacturing, while equipment and process-technology suppliers can benefit from requirements for extrusion, microporous membrane production, separator coating, solvent recovery, automation, and material handling systems.
In the separator coating and materials area, suppliers of ceramic coatings, adhesives, coating equipment, and speciality separator materials can gain procurement opportunities as ENTEK expands coated separator production. In the construction and compliance-services area, Tribal One can benefit from construction administration, labour compliance, certified payroll, and apprenticeship-related activities.
Polypropylene Battery Separator Market Strategic Takeaways
- Asia-Pacific led the global market in 2025, accounting for a dominant 64.89% share. This leadership is supported by the concentration of EV manufacturing and lithium-ion battery supply chains in China, Japan, and South Korea.
- The lithium-ion battery segment dominated the market by capturing a 72.5% market share in 2025. Demand is primarily driven by applications across electric vehicles, consumer electronics, and energy storage systems.
- Fast-charging capabilities and rising energy density demands each contribute a 22% impact toward driving market growth. These dynamics push manufacturers to develop thinner separators with low resistance and high puncture strength.
- In September 2025, the U.S. DOE approved a USD 77.2 million initial disbursement from a USD 1.3 billion loan to ENTEK Lithium Separators LLC. The funds support a facility in Terre Haute, Indiana, designed to manufacture 1.4 billion m² of separators annually.
Polypropylene Battery Separator Market Industry Trends and Strategic Insight
- Ultra-thin PP separator development is becoming a core technology direction, as manufacturers focus on reducing separator thickness while preserving puncture resistance, dimensional stability, and reliable electrode isolation for higher-energy-density cells.
- Ceramic and functional surface coatings are shifting from optional enhancements toward performance-enabling technologies, particularly for improving PP wettability, thermal stability, dimensional retention, and resistance to dendrite-induced short circuits.
- Dry-process PP separator technology is receiving greater attention because it can support cost-efficient manufacturing while enabling controlled microporous structures and avoiding some of the solvent-intensive characteristics associated with wet processing.
- Sustainability is moving into separator technology development, with increasing attention to recovering PP from spent batteries and giving separator materials a second life instead of treating them solely as low-value battery waste.
- The market is moving toward performance-based separator differentiation, where suppliers compete on thermal safety, mechanical integrity, electrolyte compatibility, pore architecture, coating quality, and consistency rather than on PP film supply alone.
Polypropylene Battery Separator Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 6.53 Billion | |
| 2035 Projected Market Size | USD 28.31 Billion | |
| CAGR (2026-2035) | 15.8% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | North America | |
| By Thickness | Below 20 micrometres (µm), 20 µm to 50 µm, 50 µm to 100 µm, above 100 µm | |
| By Layer | Single-Layer, Multilayer, Microporous, Others | |
| By Type | Lithium-ion, Lead-Acid, Others | |
| By Technology | Dry, Wet | |
| By End User | Energy and Power, Electronics, Automotive, Telecommunications, Aerospace and Defence, Medical, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Polypropylene Battery Separator Market Disruption Analysis
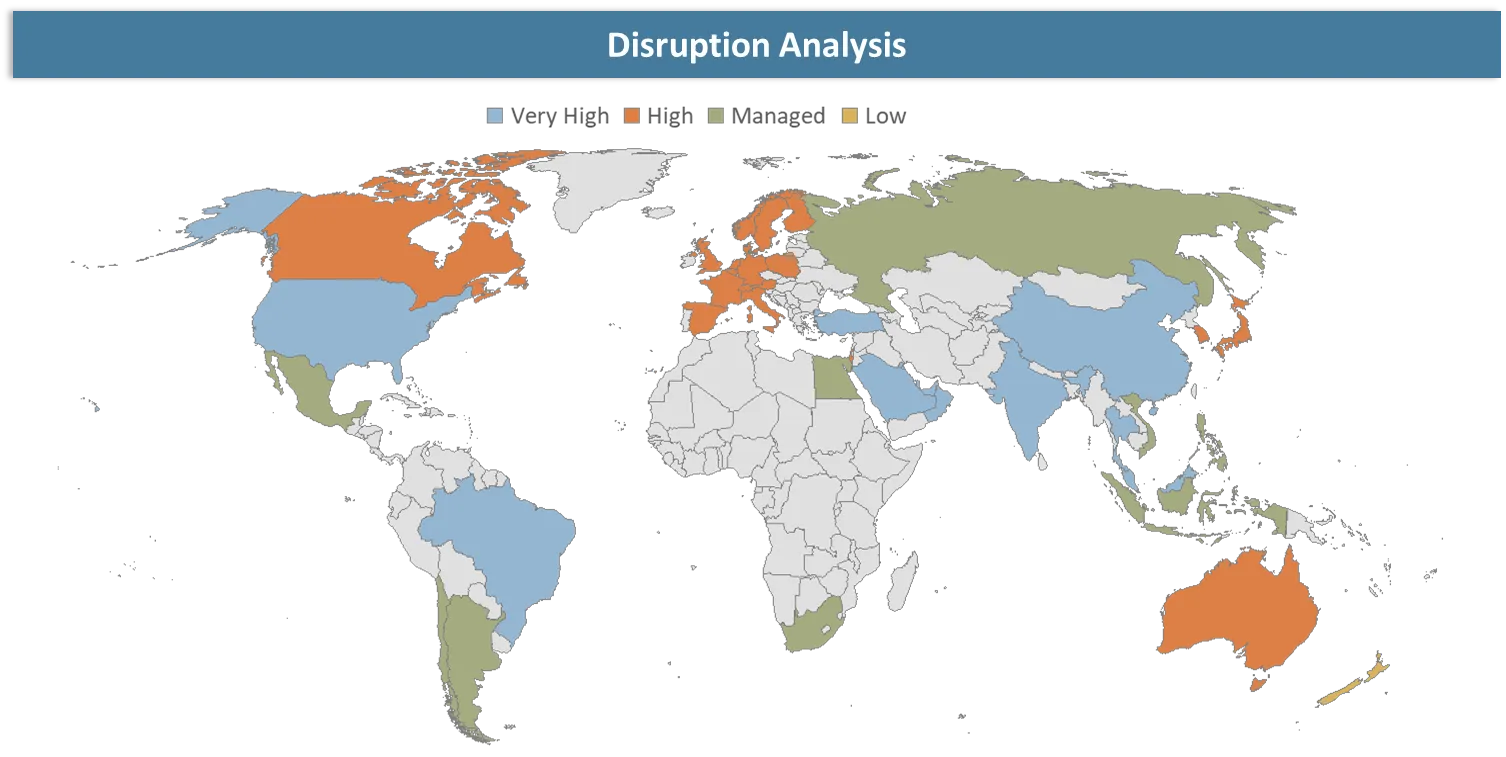
Shift Toward Multilayer, Ceramic-Coated, and Functionalized PP Separators Reshaping Battery Separator Technology
The disruption in the polypropylene battery separator market is being driven by the shift from conventional polypropylene-based separator films toward functionalized polyolefin and coated ceramic separator structures that provide enhanced properties such as thermal stability, electrolyte compatibility, adhesive strength, and cell longevity. In June 2026, SEMCORP reported that the company conducted battery cell trials for its new pure polyolefin and polyolefin/ceramic coated separator designs, with cells exhibiting 91% capacity retention even after 1,000 cycles and also meeting impact resistance and hot box safety criteria. The innovation highlights how separator providers are evolving their strategies by incorporating the PP/polyolefin base along with functional coatings.
The disruption is driving the development of high-speed intelligent manufacturing as well as expansion of regional capacity. In March 2026, SEMCORP's Yuxi plant finished commissioning all eight separator production lines in Phase I, thus establishing 800 million m²/year of production capacity out of a total project cost of RMB 2.4 billion. SEMCORP finished commissioning its first 7-meter ultra-wide online coating production line, thereby converting all 12 separator production lines in its Chongqing plant into an online coating production line.
Polypropylene Battery Separator Market BCG Matrix: Company Evaluation
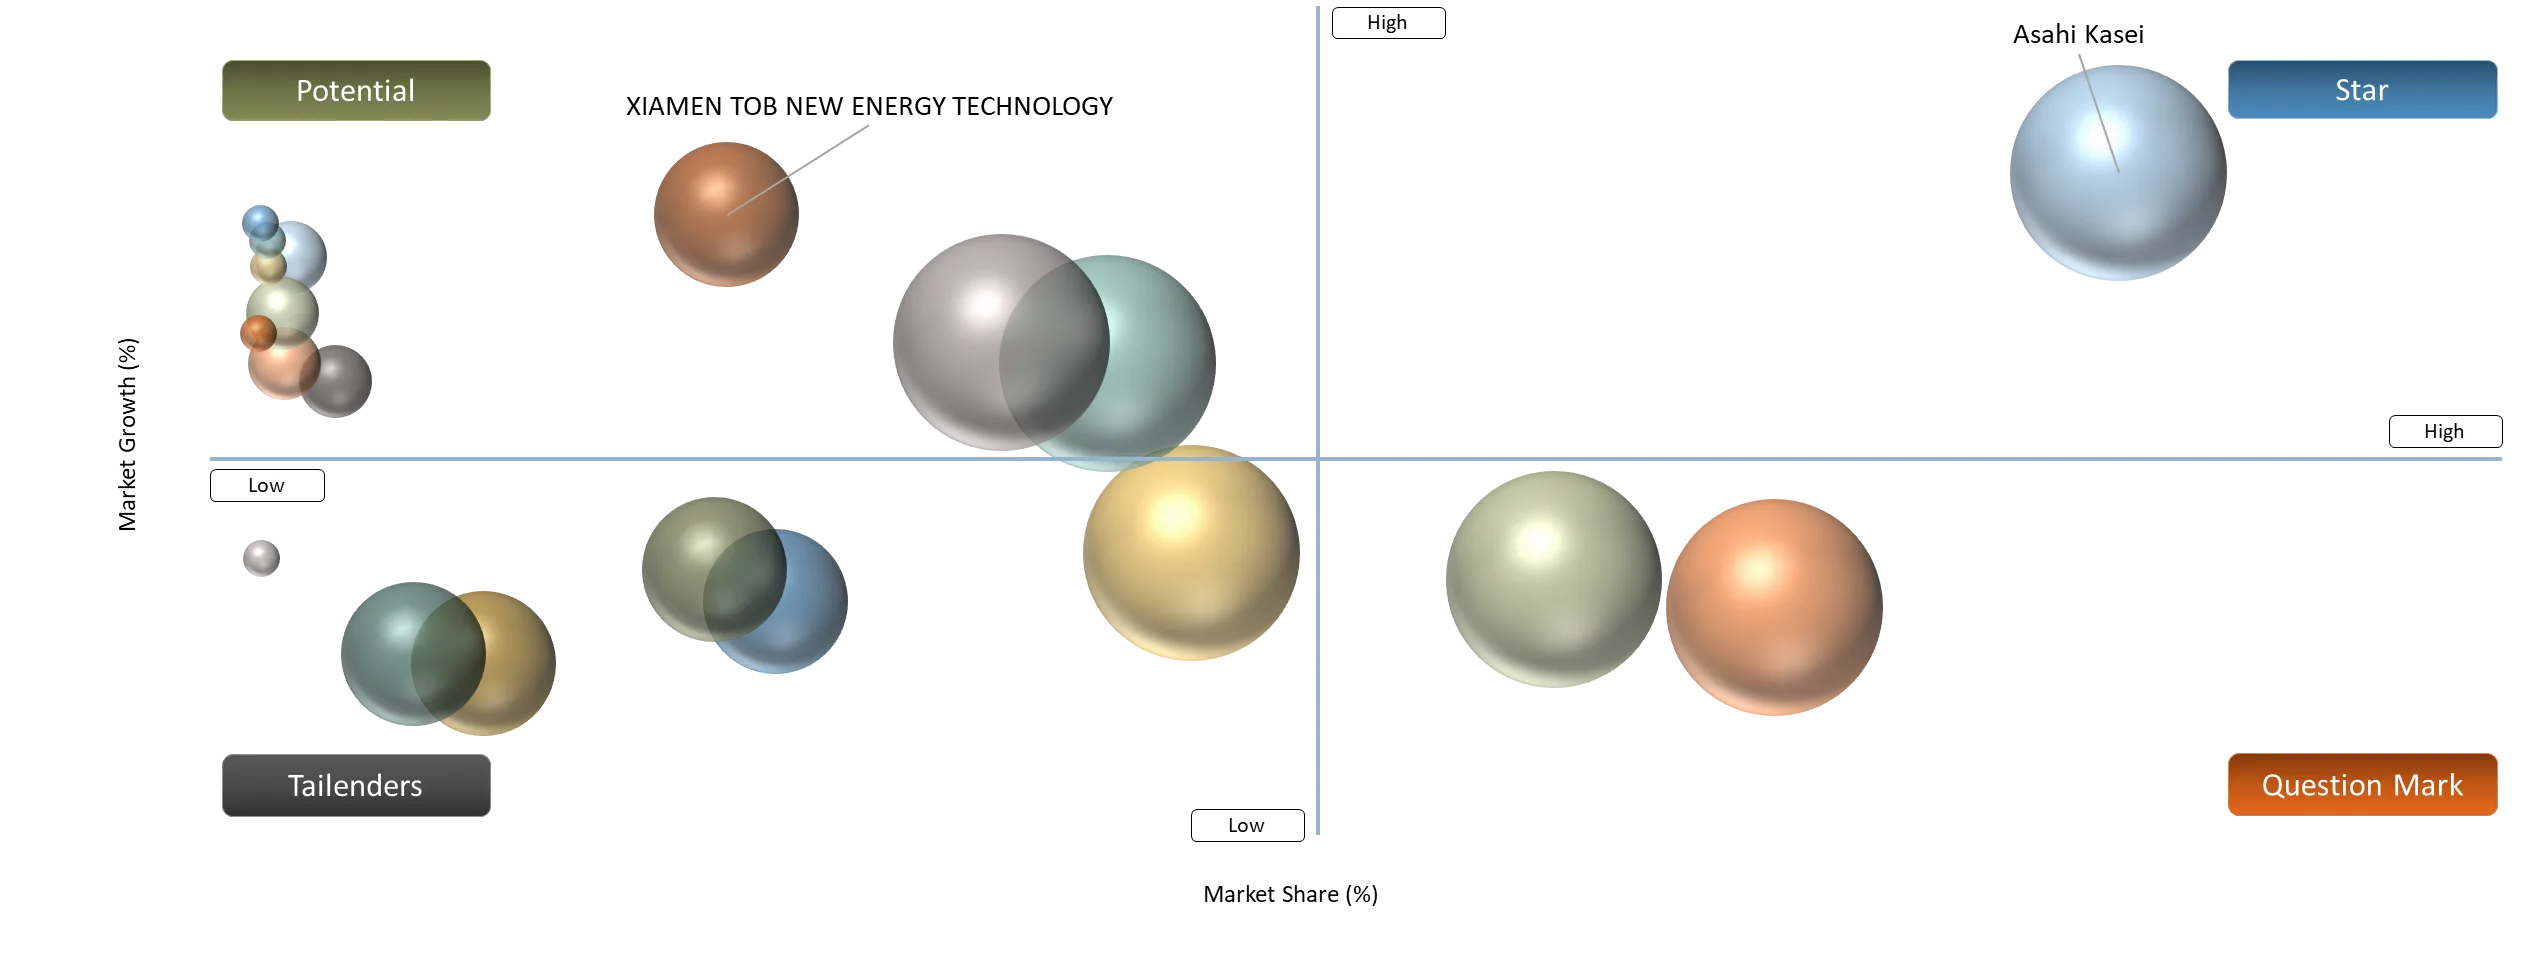
Stars include Asahi Kasei, Toray Industries, and Entek International because they have established separator technologies, large-scale manufacturing capabilities, and strong positions in lithium-ion battery separator supply. Question Marks include UBE Industries, W-Scope Industries, and Sumitomo Chemical, which possess established separator technologies and are expanding or upgrading their battery-material capabilities but face strong competition from larger global separator manufacturers.
Potential includes XIAMEN TOB NEW ENERGY TECHNOLOGY, Anhui Jinxi New Material Technology, and AOT Battery Technology, which benefit from expanding lithium-ion battery manufacturing and demand for separator materials and production technologies. Tailenders include Cambridge Energy Solutions Ltd., whose participation in the polypropylene battery-separator ecosystem is comparatively limited against established separator manufacturers.
Polypropylene Battery Separator Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Advances in polypropylene separator coatings and surface modification are driving improved fire resistance, electrolyte compatibility, and high-voltage battery performance. | 24% | High in EV batteries, high-energy-density cells, and advanced energy-storage systems | High-safety EV batteries and fast-charging/high-voltage lithium-ion cells | Accelerates the shift from conventional PP films toward ceramic-, polymer-, and multifunctional-coated separators, increasing demand for value-added separator technologies. |
Rising demand for lithium-ion batteries in electric vehicles and energy-storage systems is driving the need for polypropylene separators. | 32% | Very high in automotive batteries and grid/ESS applications | EV battery packs and stationary energy-storage systems | Expands separator consumption and encourages suppliers to establish localised production near major battery-cell manufacturing clusters. |
Growing demand for fast-charging batteries is increasing the need for high-performance polypropylene separators. | 22% | High in EVs, power batteries, and premium consumer-electronics cells | Fast-charging EV and high-power lithium-ion batteries | Raises requirements for controlled pore structures, low resistance, high electrolyte compatibility, and mechanical stability, favouring engineered PP separator grades over commodity films. |
Rising battery energy density is accelerating demand for thinner polypropylene separator films that maintain mechanical integrity and safe electrode separation. | 22% | High in high-energy-density EV cells, portable electronics, and advanced ESS | High-energy-density battery cells | Pushes separator manufacturers toward thinner, high-strength substrates and advanced coating architectures while maintaining puncture resistance and thermal safety. |
Advances in polypropylene separator coatings and surface modification are driving improved fire resistance, electrolyte compatibility, and high-voltage battery performance
The rapid development of polypropylene separator coatings and surface-modification technologies is accelerating demand for more advanced separators by solving the inherent issues related to traditional PP membranes in terms of thermal stability, electrolyte compatibility, and voltage. The trend involves a shift from regular PP separators to coated, polymer-functionalized, or multi-layer separators that offer better stability, better compatibility with the electrolyte, better resistance to heat, and prevention of internal shorts.
In parallel, advances in multifunctional ceramic modification of PP separators improve fire resistance and fast charging. In November 2025, according to the International Journal of Energy Research by Wiley, it was shown that functionalization of a PP separator with boehmite (AlOOH) coating reduced the thermal shrinkage to 7.9% at 150°C, while for the conventional Al₂O₃-coated separator it was 23.8% and for the uncoated separator it was 42.9%. Moreover, the functionalized separator demonstrated a discharge capacity of 261.1 mAh/g after 100 cycles with 1,000 mA/g and 80°C, indicating that surface functionalization can concurrently improve the thermal and ion-diffusion properties of separators under harsh conditions.
Polypropylene Battery Separator Market Segment Analysis
The global polypropylene battery separator market is segmented based on thickness, layer, type, technology, end user, and region.
Lithium-ion Batteries Driving Dominance of Polypropylene Battery Separator Demand
The lithium-ion segment dominates the polypropylene battery separator market, with a 72.5% market share in 2025, as a result of widespread use of polypropylene separators in rechargeable lithium-ion batteries used in electric vehicles, energy storage systems, consumer electronics, and others. The domination of lithium-ion technology is enhanced by the fact that lithium-ion batteries have the capability to deliver high energy density and rechargeable properties, allowing them to form the most prominent battery platform that requires the use of microporous separator material.
In parallel, accelerating EV deployment is strengthening demand for lithium-ion cells, and therefore polypropylene battery separators as well. According to the International Energy Agency (IEA), global electric-car sales grew 20% in 2025 to surpass 20 million units, which means that electric cars comprised one-fourth of all newly sold cars worldwide. The leader in terms of the number of EVs was China, where electric cars comprised 55%of all cars sold in the country, while Southeast Asia saw its EV sales almost double to reach nearly 20% of all car sales in the region. It should be added that according to the IEA, China made up more than 80% of the world’s lithium-ion cell production in 2025.
Polypropylene Battery Separator Market Geographical Penetration
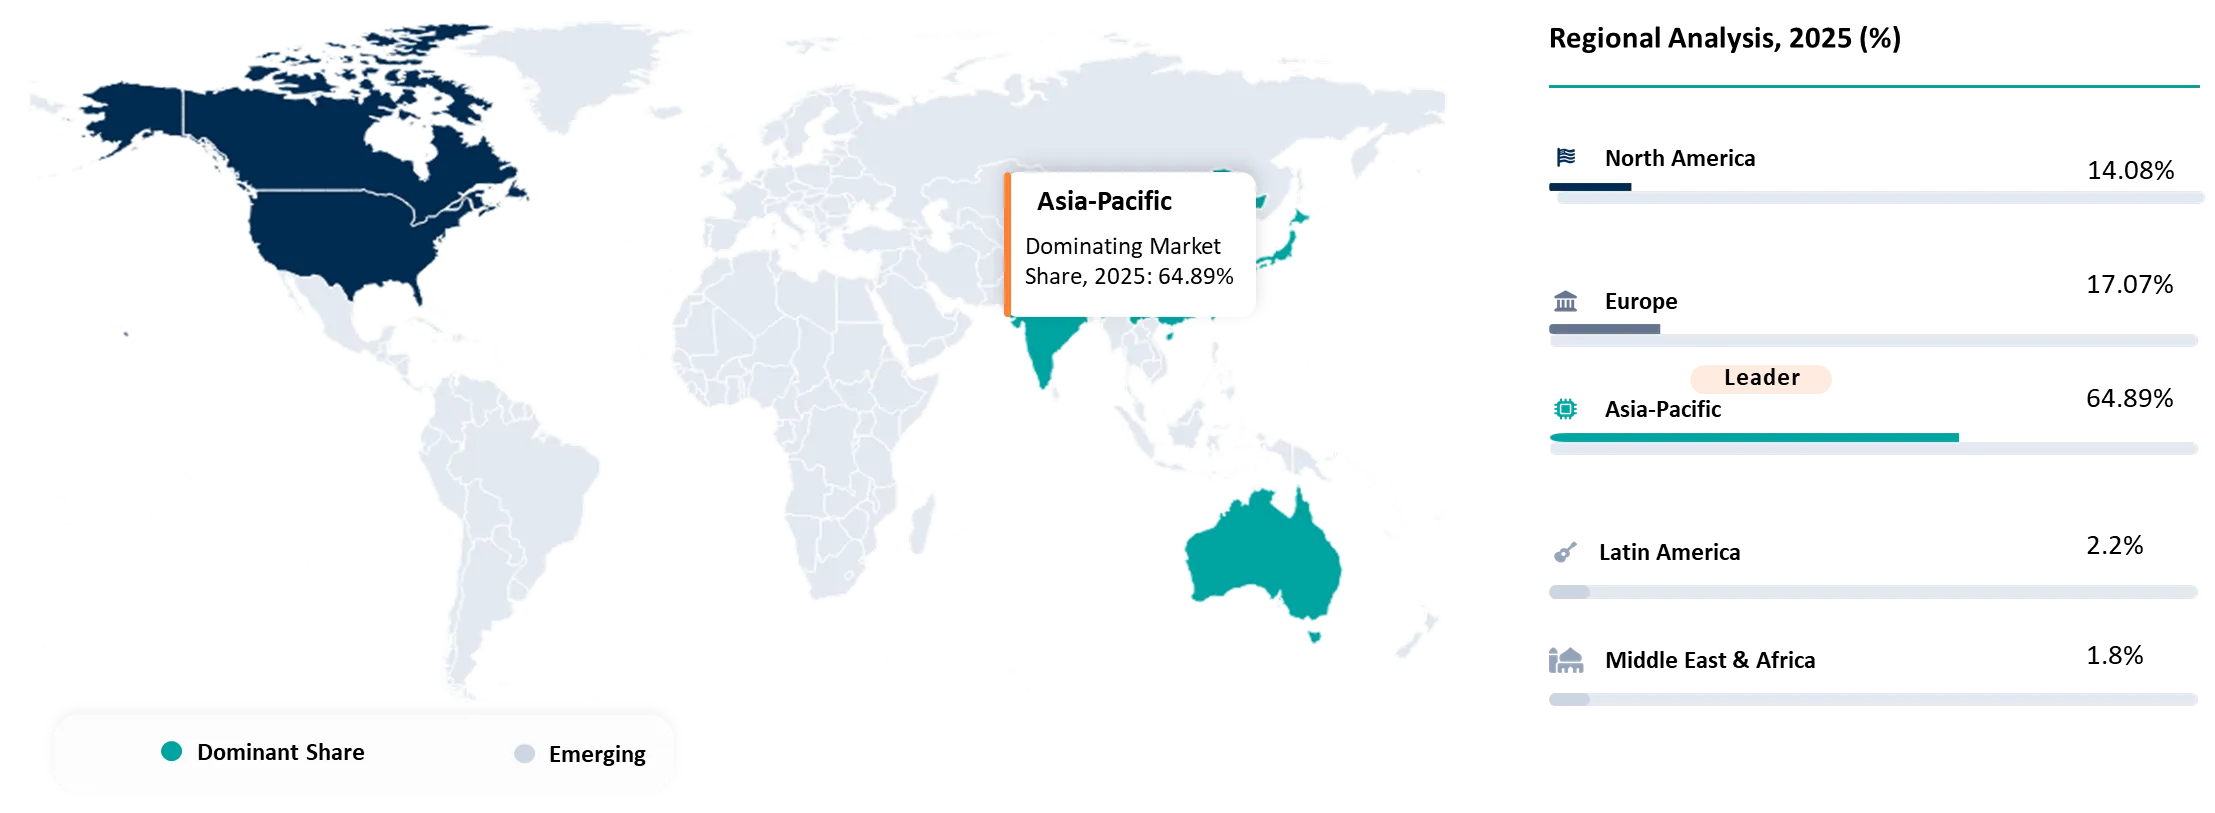
Rapid Battery Manufacturing Expansion and Separator Capacity Development in Asia-Pacific
The Asia-Pacific region dominates the polypropylene battery separator market, accounting for 64.89% of the market in 2025, supported by the region's concentration of lithium-ion battery manufacturing, electric-vehicle production, separator-film producers, and battery-material supply chains. China, Japan, and South Korea form the core of this ecosystem, enabling separator manufacturers to operate close to major cell producers and integrate PP separator technologies into rapidly expanding battery-production networks.
A strategic partnership between major separator and speciality-materials players is strengthening innovation in high-performance lithium-ion battery separator technologies. In December 2025, Arkema, a France-based speciality materials company, signed a strategic MoU with SEMCORP, a China-based lithium-ion battery separator manufacturer, to accelerate next-generation battery separator technologies and support SEMCORP’s international expansion. The partnership covers high-performance separator solutions for electric vehicles, energy-storage systems, and consumer electronics, with Arkema providing advanced materials and technical support, including Kynar PVDF and Incellion acrylic-based solutions for separator applications.
China Polypropylene Battery Separator Market Trends
China holds a dominant position in the Asia-Pacific polypropylene battery separator market because of its highly integrated lithium-ion battery ecosystem, extensive EV manufacturing base, and large-scale separator-film production capacity. The country combines battery-cell manufacturers, separator producers, coating specialists, cathode and anode suppliers, and EV manufacturers within a closely connected domestic supply chain, enabling rapid commercialization of polypropylene and other polyolefin separator technologies.
The partnership strengthens collaboration between advanced materials and battery-separator technology providers to accelerate next-generation lithium-ion battery innovation. In February 2026, Arkema, a France-based speciality materials company, signed a strategic MoU with Senior, a China-based lithium-ion battery separator technology company, to advance next-generation battery materials and separator technologies. The collaboration focuses on advanced adhesion, controlled deposition and coating, low-temperature cell assembly, and semi-solid battery manufacturing, with Senior operating R&D and manufacturing platforms across China, Southeast Asia, Europe, and the U.S.
Japan Polypropylene Battery Separator Market Outlook
Japan is a major player in the Asia-Pacific polypropylene battery separator market because of its established battery-materials ecosystem, advanced separator-film technology, and strong presence of manufacturers such as UBE MAXELL, Asahi Kasei, and Toray I. Japanese companies are increasingly focusing on high-performance separator technologies for automotive lithium-ion batteries, including dry-process and wet-process membranes, functional coatings, and improved thermal-safety characteristics.
The expansion of Japanese battery-material companies into the rapidly developing regional EV battery ecosystem. In July 2025, Asahi Kasei, a Japan-based diversified chemical and materials company, and Toyota Tsusho, a Japan-based trading and mobility-focused company, established a strategic partnership for automotive lithium-ion battery separators in North America. Under the agreement, Asahi Kasei’s U.S. subsidiary will supply Hipore wet-process separators from its Charlotte, North Carolina coating facility to Toyota Tsusho’s U.S. subsidiary from mid-2027, securing a preferential share of production capacity.
North America’s Expanding Position in the Polypropylene Battery Separator Market
North America is the fastest-growing region in the polypropylene battery separator market, accounting for 14.08% market share in 2025, supported by the region’s growing lithium-ion battery manufacturing ecosystem, expanding electric-vehicle production, and increasing deployment of energy-storage systems. The region is progressively developing a localised battery supply chain that includes cell manufacturing, battery materials, separator films, and coating technologies.
The company’s latest separator solutions focus on improving thermal safety, energy density, fast charging, and long-term battery performance. In October 2025, SEMCORP, a China-based lithium-ion battery separator manufacturer, showcased its next-generation flame-retardant separator at the 2025 North America Battery Show in Detroit, U.S. The new separator reduces coating base weight by more than 40% compared with alumina ceramic coatings and lowers moisture content by more than 20%, supporting improved energy density and battery cycle life. SEMCORP also presented a 5 μm ultra-thin high-strength separator film with puncture strength exceeding 560 gf, alongside a High-Safety, Fast-Charging, Long-Life, and High-Capacity separator product series.
U.S. Polypropylene Battery Separator Market Trends
The U.S. is dominating the North American polypropylene battery separator market due to its expanding domestic lithium-ion battery ecosystem, localisation of battery-component manufacturing, and increasing investment in EV and energy-storage supply chains. The country is developing an integrated battery manufacturing base that includes cell production, separator manufacturing, coating technologies, and battery-material processing.
The investment strengthens domestic U.S. battery-separator manufacturing capacity and supports the localisation of critical lithium-ion battery components. In September 2025, I Squared Capital, a U.S.-based global infrastructure investment manager, agreed to acquire a majority stake in ENTEK Technology Holdings, a U.S.-based battery separator manufacturer, through a USD 800 million investment. The investment supports construction of ENTEK’s Terre Haute, Indiana gigafactory, which is planned to produce 1.4 billion m² of wet-process lithium-ion battery separators annually in its first two phases and is designed to expand to 2.1 billion m².
Polypropylene Battery Separator Market Competitive Landscape
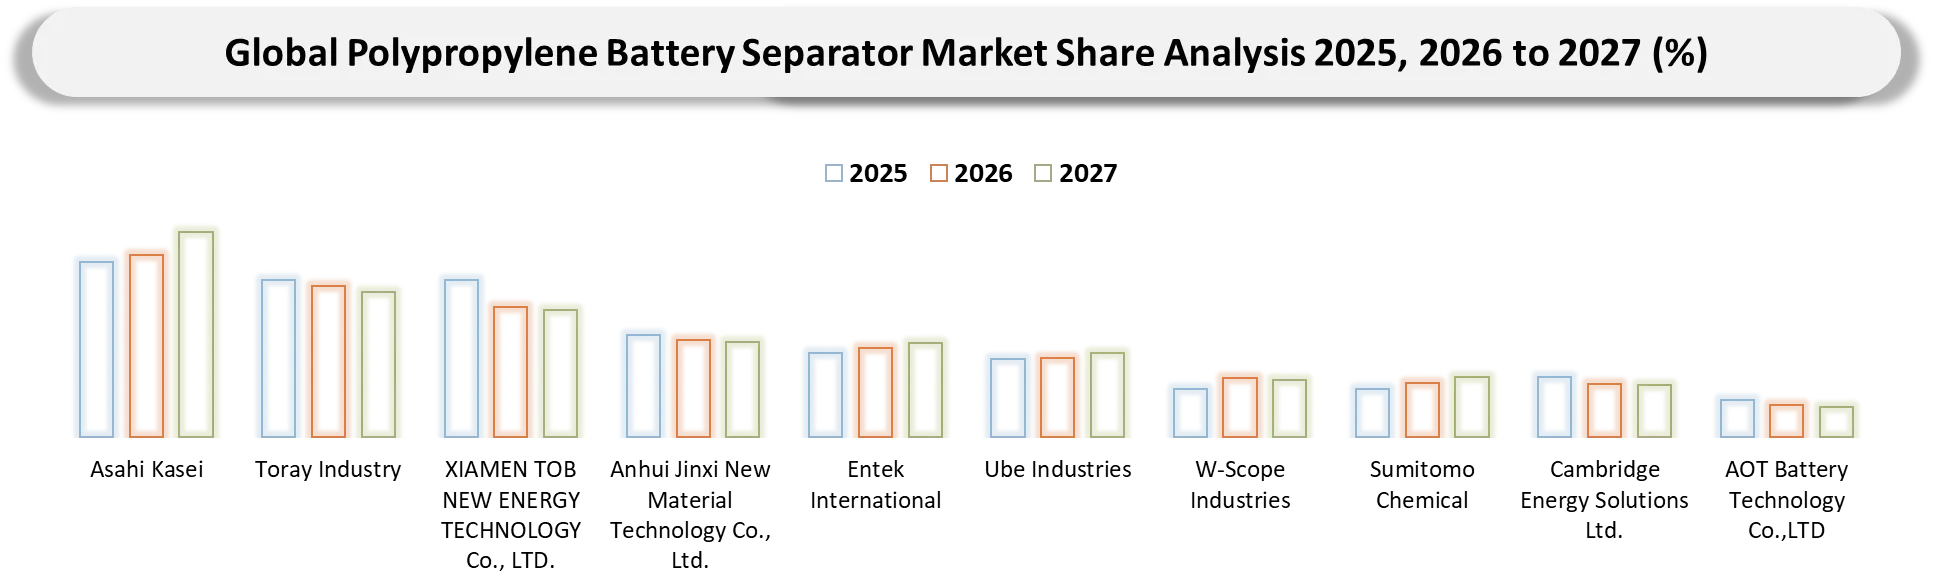
- The market is characterized by three key participant groups: integrated battery-material and separator manufacturers, specialised separator-film producers, and battery manufacturing equipment/material suppliers. Asahi Kasei, Toray Industries, UBE Industries, W-Scope, and Sumitomo Chemical represent established separator-material companies with wet- and/or dry-process technologies and strong relationships with lithium-ion battery manufacturers; Entek International focuses on polyolefin separator films and localized North American production; while Xiamen TOB New Energy Technology, Anhui Jinxi New Material Technology, Cambridge Energy Solutions, and AOT Battery Technology participate through separator-film materials, manufacturing technologies, or specialised battery-component solutions.
- Key players include Asahi Kasei (Japan), Toray Industries (Japan), Xiamen TOB New Energy Technology (China), Anhui Jinxi New Material Technology (China), Entek International (U.S.), UBE Industries (Japan), W-Scope Industries (Japan), Sumitomo Chemical (Japan), Cambridge Energy Solutions (U.K.), and AOT Battery Technology (China).
Key Developments
- August 2026: Asahi Kasei, a Japan-based and a diversified chemical and materials company, completed a new Hipore wet-process lithium-ion battery separator coating line at its existing Celgard facility in Charlotte, North Carolina, with commercial production scheduled for the second half of FY2026.
- August 2026: SK Innovation, a South Korea-based energy and chemicals company, announced plans to absorb SK IE Technology (SKIET), a South Korea-based lithium-ion battery separator manufacturer, to improve the profitability and competitiveness of its separator business.
- June 2026: Cangzhou Mingzhu Plastic Co., Ltd., a China-based plastics processing and lithium-ion battery separator manufacturer, completed the commissioning of its remaining production lines under two lithium-ion battery separator expansion projects.
- December 2025: Arkema, a France-based speciality materials company, signed a strategic MoU with SEMCORP, a China-based lithium-ion battery separator manufacturer, to accelerate next-generation separator technologies and support international expansion.
- May 2025: Recharge New Energy, a China-based battery-materials technology company, showcased its Active Functional Separator and SCS quasi/full solid-state electrolyte membrane at CIBF2025 in Shenzhen.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organisations procuring polypropylene battery separators increasingly prioritise suppliers capable of delivering consistent pore structure, controlled thickness, high mechanical strength, and reliable electrode insulation for high-volume lithium-ion battery production.
- The procurement decision is increasingly influenced by the shift toward higher-energy-density EV batteries, fast-charging cells, and large-scale energy-storage systems, requiring separators with stronger thermal stability, electrolyte compatibility, and resistance to internal short circuits.
- Buyers evaluate separator thickness uniformity, porosity, pore-size distribution, puncture strength, tensile strength, thermal shrinkage, electrolyte wettability, and ionic resistance when selecting separator suppliers.
Why Choose DataM?
- Technological Innovations: Explores advancements in polypropylene battery separator technologies, including ultra-thin microporous films, multilayer PP structures, ceramic-coated separators, functional surface modification, and dry- and wet-process technologies.
- High-Performance Product: Evaluates how different players differentiate separator products based on thickness, porosity, pore-size distribution, puncture strength, tensile strength, thermal shrinkage, electrolyte wettability, ionic resistance, and coating performance, identifying competitive positioning across EV, electronics, and energy-storage applications.
- Real-World Evidence: Highlights the deployment of polypropylene separators across electric vehicles, hybrid vehicles, consumer electronics, and stationary energy-storage systems, demonstrating their contribution to electrode isolation, lithium-ion transport, fast-charging capability, thermal safety, and long-cycle battery performance.
- Market Updates & Industry Changes: Tracks key developments including separator-film capacity expansions, coating-line additions, new multilayer and functionalized PP separator technologies, battery manufacturing investments, and supply-chain localisation across Asia-Pacific, North America, and Europe.
- Competitive Strategies: Capacity scaling, separator-thickness optimisation, coating and surface-modification technologies, dry/wet process development, strategic partnerships, and localised manufacturing to address growing requirements from EV and energy-storage battery manufacturers.
- Pricing & Market Access: Explains pricing variations based on film thickness, PP material grade, manufacturing process, coating architecture, multilayer configuration, customisation, production scale, and performance specifications, while assessing access through battery-cell manufacturers, EV producers, energy-storage companies, and battery-material supply chains.
- Market Entry & Expansion: Identifies growth opportunities driven by THIS, while outlining strategies such as high-strength thin-film development, advanced coating capabilities, regional production expansion, and partnerships with battery-cell manufacturers to strengthen global market access.
Target Audience 2026
- Polypropylene Battery Separator Manufacturers
- Lithium-Ion Battery Cell Manufacturers
- Electric Vehicle & Automotive Battery Manufacturers
- Battery Material & Component Suppliers
- Energy Storage System Manufacturers
- Battery Manufacturing Equipment Providers
- Research Institutes & Battery Technology Developers





























































