


Antibody-Drug Conjugates (ADC) Market Overview
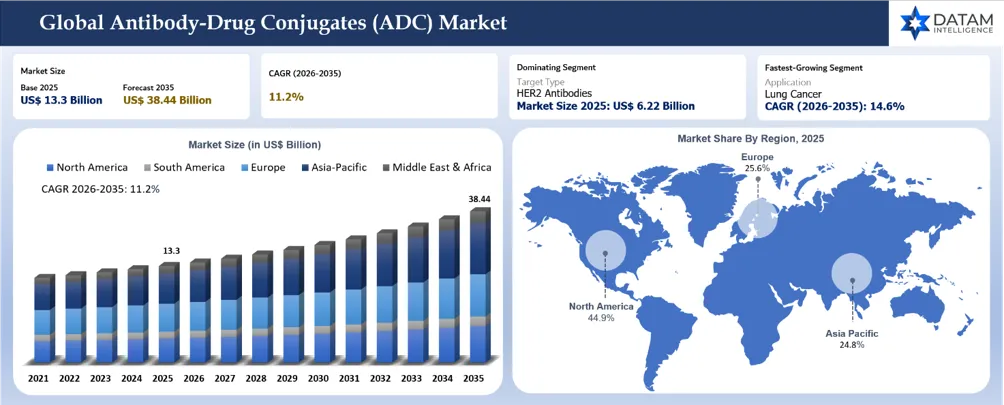
The global antibody-drug conjugates (ADC) market reached US$13.3 billion in 2025 and is expected to reach US$38.44 billion by 2035, growing with a CAGR of 11.2% during the forecast period 2026-2035.
Growth is being shaped by the expansion of ADCs into earlier treatment lines, increasing biomarker testing and broader recognition of low-antigen-expressing tumours. HER2-directed ADCs remain the market’s revenue foundation, led by Enhertu and Kadcyla across breast, gastric, lung and other HER2-expressing cancers. Commercial demand is also strengthening for Trop-2-, Nectin-4-, CD30-, CD79b- and FRα-directed therapies. However, interstitial lung disease, ocular toxicity, neuropathy, haematological adverse events and complex infusion-monitoring requirements can restrict patient eligibility and treatment continuity.
Next-generation ADC engineering represents the market’s principal growth vector. Greater linker stability, site-specific conjugation, optimized drug-to-antibody ratios and potent payloads are improving tumour selectivity and therapeutic performance. Competitive advantage will increasingly depend on target differentiation, response durability, activity in low-expression tumours, resistance management, combination potential and successful movement into first-line, neoadjuvant and adjuvant settings.
The next value-creation cycle will centre on B7-H3, HER3, Claudin 18.2, c-MET, BCMA and other emerging targets, alongside bispecific and dual-payload ADC architectures. Sustainable leadership will require scalable manufacturing, reliable companion diagnostics, effective toxicity management and strong global market-access execution. Companies integrating clinical development with biomarker strategies, real-world evidence and disciplined portfolio prioritization will be best positioned to reshape oncology treatment sequencing and capture premium value.
Antibody-Drug Conjugates (ADC) Market Key Takeaways
- Sustained Market Expansion Through 2035: The antibody-drug conjugates market reached US$13.3 billion in 2025 and is projected to reach US$38.44 billion by 2035, registering a CAGR of 11.2% during 2026-2035.
- HER2 Antibodies Maintain Market Leadership: The HER2 antibodies segment dominated the market with an estimated value of US$6.22 billion in 2025, supported by the commercial adoption and expanding indications of Enhertu and Kadcyla across HER2-expressing cancers.
- Lung Cancer Becomes the Fastest-Growing Application: The lung cancer segment is expected to grow at a CAGR of 14.6% during 2026–2035, driven by expanding clinical development of HER2-, Trop-2-, c-MET- and HER3-directed ADCs for biomarker-selected NSCLC populations.
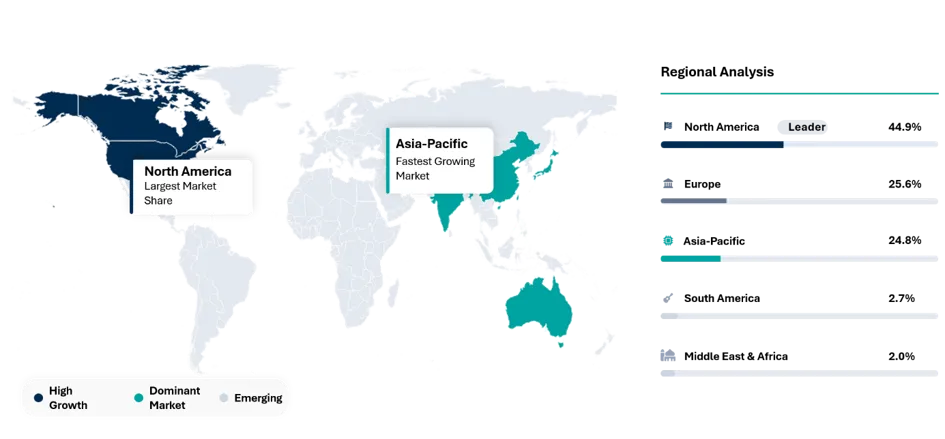
- North America Maintains Regional Dominance: North America accounted for approximately 44.9% of the market in 2025, equivalent to nearly US$5.97 billion, supported by early regulatory approvals, advanced biomarker testing, high oncology expenditure and broad access to approved ADCs.
- Next-Generation ADC Platforms Reshape Competition: Future leadership will depend on tumour-selective targets, stable linkers, differentiated payloads, site-specific conjugation and improved therapeutic windows. Companies demonstrating durable clinical benefit with lower pulmonary, ocular and haematological toxicity will be best positioned to capture market share.
Antibody-Drug Conjugates (ADC) Market Scope
| Metrics | Details | |
| 2025 Market Size | US$13.3 Billion | |
| 2035 Projected Market Size | US$38.44 Billion | |
| CAGR (2026-2035) | 11.2% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Product Type | Adcetris, Perjeta, Kadcyla, Enhertu, Padcev, Trodelvy, Polivy, Others | |
| By Target Type | CD30 Antibodies, HER2 Antibodies, CD22 Antibodies, Others | |
| By Technology Type | Linker Technology, Payload Technology, Others | |
| By Application | Breast Cancer, Blood Cancer, Skin Cancer, Lung Cancer, Ovary Cancer, Others | |
| By End-User | Hospitals, Cancer Centres, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Antibody-Drug Conjugates (ADC) Market White Space & Investment Opportunities
- Novel Target and Biomarker Discovery: Invest in identifying tumour-selective antigens beyond established HER2 and Trop-2 targets. B7-H3, HER3, Claudin 18.2, FRα, c-MET, CEACAM5 and ROR1 offer opportunities for biomarker-defined ADC development across underserved solid and haematological cancers.
- Improved Therapeutic Index: Develop ADCs with greater tumour selectivity, controlled drug-to-antibody ratios and reduced systemic payload exposure. Better linker stability and site-specific conjugation can expand dosing flexibility while limiting interstitial lung disease, ocular toxicity, neuropathy and haematological adverse events.
- Next-Generation Payloads: Advance payloads beyond conventional microtubule inhibitors and topoisomerase inhibitors. Immune stimulants, protein degraders, RNA-modulating agents and dual-mechanism payloads could address resistance and differentiate new ADC platforms within increasingly crowded target classes.
- Earlier-Line and Curative-Intent Treatment: Expand ADC development from heavily pretreated metastatic populations into first-line, neoadjuvant, adjuvant and maintenance settings. Investment should prioritize regimens capable of improving pathological response, eliminating residual disease and preventing recurrence.
- ADC Combination Strategies: Generate comparative evidence for combining ADCs with immune-checkpoint inhibitors, targeted therapies and DNA-damage response agents. Biomarker-led sequencing will be required to maximize efficacy while avoiding overlapping toxicity.
- Resistance Monitoring and Patient Selection: Invest in liquid biopsy, circulating tumour DNA and longitudinal antigen-expression testing to detect target loss, payload resistance and tumour heterogeneity. Dynamic diagnostics could support treatment switching and improve patient selection.
- Low-Antigen and Heterogeneous Tumours: Develop ADCs with optimized bystander effects, bispecific antibodies and dual-payload architectures capable of treating tumours with variable or low target expression.
- Manufacturing and Supply-Chain Scalability: Expand integrated antibody production, linker-payload synthesis, conjugation and fill-finish capacity. Standardized manufacturing and analytical controls can reduce production costs, shorten development timelines and improve commercial supply reliability.
- Geographic Access and Local Commercialization: Build regional clinical-development, diagnostic and manufacturing partnerships across Asia, South America , the Middle East and Africa. Flexible pricing and outcome-based reimbursement can improve access beyond established oncology markets.
Antibody-Drug Conjugates (ADC) Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Overall Survival and Durability of Response
- Progression-Free Survival and Disease-Control Rate
- Objective Response Rate and Complete Response Rate
- Effectiveness by Cancer Type, Disease Stage and Treatment Line
- Target-Antigen Expression Level and Tumour Heterogeneity
- Biomarker Eligibility, Including HER2, Trop-2, FRα, B7-H3, HER3, Claudin 18.2 and CD30
- Efficacy in Low-Antigen-Expressing and Previously Treated Tumours
- Activity in Chemotherapy-Resistant and ADC-Exposed Patients
- Linker Stability, Payload Potency and Bystander-Killing Effect
- Drug-to-Antibody Ratio and Tumour-Targeting Selectivity
- Safety, Tolerability and Long-Term Clinical Evidence
- Risk of Interstitial Lung Disease, Ocular Toxicity, Neuropathy and Haematological Adverse Events
- Route of Administration, Dosing Frequency and Treatment Burden
- Companion-Diagnostic and Antigen-Testing Requirements
- Hospital Monitoring and Adverse-Event Management Requirements
- Compatibility with Immunotherapies and Other Combination Regimens
- Improvement in Symptoms, Functional Status and Quality of Life
- Pricing, Reimbursement and Total Treatment Cost
- Guideline Positioning, Regulatory Approval and Physician Experience
- Manufacturing Reliability, Geographic Availability and Patient-Support Services
Global Antibody-Drug Conjugates (ADC) Market BCG Matrix: Company Evaluation
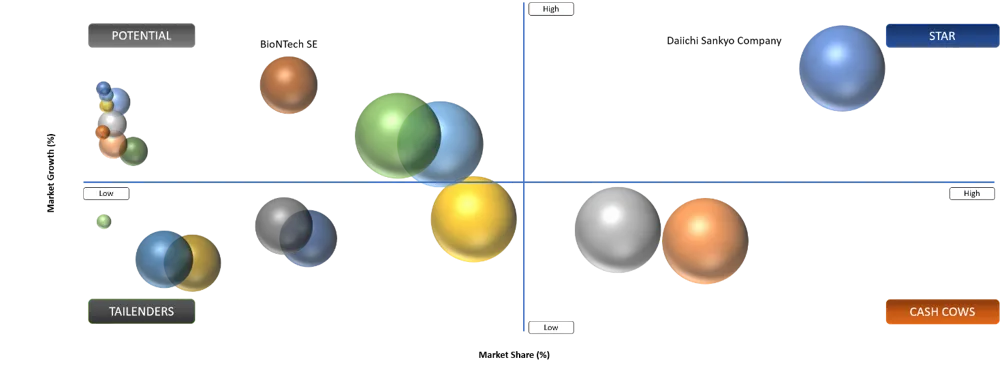
STAR
Daiichi Sankyo Company, Limited, AstraZeneca plc, Pfizer Inc., F. Hoffmann-La Roche Ltd, Gilead Sciences, Inc., AbbVie Inc. and Astellas Pharma Inc. are positioned in the Star category based on their approved ADC portfolios, global oncology commercialization capabilities, late-stage pipelines and influence on treatment sequencing. Daiichi Sankyo and AstraZeneca lead through Enhertu and Datroway, supported by the clinically validated DXd platform. Pfizer maintains a diversified portfolio comprising Adcetris, Padcev, Tivdak and Besponsa, while Roche competes through Kadcyla and Polivy. Gilead maintains a strong position through Trodelvy, AbbVie through Elahere and Emrelis, and Astellas through Padcev.
Sustaining Star positioning will depend on expanding ADCs into earlier treatment lines, securing tumour-agnostic indications and demonstrating superiority over chemotherapy and competing targeted therapies. Companies must also improve linker stability, payload selectivity, therapeutic index and resistance management. Global manufacturing capacity, companion-diagnostic availability, combination strategies and effective management of interstitial lung disease, ocular toxicity and haematological adverse events will increasingly determine commercial leadership.
POTENTIAL
BioNTech SE, Genmab A/S, RemeGen Co., Ltd., Sichuan Kelun-Biotech Biopharmaceutical Co., Ltd., Duality Biologics Co., Ltd., Innovent Biologics, Inc., Hansoh Pharmaceutical Group Company Limited, ADC Therapeutics SA and Sutro Biopharma, Inc. are positioned in the Potential category because of their expanding clinical pipelines, differentiated ADC platforms and growing licensing relationships with established pharmaceutical companies.
BioNTech and DualityBio are advancing multiple ADCs targeting HER2, HER3 and B7-H3, while Kelun-Biotech is developing sacituzumab tirumotecan and other next-generation candidates. RemeGen is expanding disitamab vedotin across HER2-expressing cancers, and Genmab is strengthening its portfolio through Tivdak and Rina-S. Innovent and Hansoh are progressing ADCs across Claudin 18.2, B7-H3 and other emerging targets, while ADC Therapeutics and Sutro contribute specialized payload and site-specific conjugation capabilities. Progression toward the Star category will depend on pivotal-trial success, regulatory approvals, differentiated safety, scalable manufacturing, global partnerships and successful commercialization beyond domestic markets.
Antibody-Drug Conjugates (ADC) Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Expansion of HER2-Directed ADCs into HER2-Low, HER2-Ultralow and Tumour-Agnostic Populations | 29.4% | High across North America, Europe and Japan; accelerating across China | Breast, gastric, lung and other HER2-expressing solid tumours | Expands addressable populations beyond conventionally defined HER2-positive cancers and enables ADC adoption across broader antigen-expression thresholds |
Movement of ADCs into First-Line, Neoadjuvant and Adjuvant Treatment Settings | 27.1% | Highest across mature oncology markets with established biomarker-testing infrastructure | Early-stage disease, first-line metastatic treatment and post-surgical residual disease | Increases eligible patient volumes, extends treatment duration and shifts ADCs from salvage therapies toward foundational oncology regimens |
Validation of New Targets and Next-Generation Linker-Payload Architectures | 24.3% | Strongest across the United States, China, Japan and European clinical-development hubs | B7-H3, HER3, FRα, Claudin 18.2, c-MET and other tumour-associated targets | Supports pipeline diversification, improves therapeutic differentiation and creates licensing opportunities for specialized ADC biotechnology companies |
Increasing ADC Combination with Immune-Checkpoint Inhibitors and Targeted Therapies | 19.2% | Concentrated in breast, lung, urothelial, ovarian and haematological oncology centres | ADC combinations with PD-1, PD-L1, PARP and other targeted agents | Improves response depth, addresses resistance and enables differentiated treatment positioning, although overlapping toxicities require careful clinical management |
Driver: Expansion of HER2-Directed ADCs into HER2-Low, HER2-Ultralow and Tumour-Agnostic Populations
HER2-directed ADCs are expanding the treatable population beyond cancers historically classified as HER2-positive. Improved immunohistochemistry, companion diagnostics and clinical evidence have established HER2-low and HER2-ultralow expression as therapeutically actionable categories, particularly in breast cancer. ADCs with potent payloads, cleavable linkers and bystander-killing activity can target malignant cells with limited HER2 expression while affecting adjacent heterogeneous tumour cells. This development increases eligible patient volumes and supports earlier biomarker testing across breast, gastric, lung and other solid tumours.
Tumour-agnostic approvals further reposition HER2 from an organ-specific marker to a cross-cancer therapeutic target. Pharmaceutical companies are consequently extending development programmes across colorectal, biliary tract, endometrial, cervical, ovarian and salivary-gland cancers. Commercial success will depend on standardized HER2 testing, consistent interpretation of low-expression results and careful management of interstitial lung disease. Companies capable of integrating broad clinical development, diagnostic partnerships and physician education will capture greater value as HER2-directed ADCs move into earlier treatment lines and increasingly replace conventional chemotherapy across biomarker-selected populations.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Dose-Limiting Interstitial Lung Disease, Ocular Toxicity and Haematological Adverse Events | 31.2% | Treatment eligibility, dosing continuity and pharmacovigilance | HER2-directed, FRα-directed and other payload-intensive ADC treatment | Restricts use among vulnerable patients, increases monitoring requirements and can result in dose interruption, reduction or permanent treatment discontinuation |
Antigen Heterogeneity, Target Loss and Payload-Mediated Treatment Resistance | 27.6% | Response durability and patient selection | Low-antigen, heterogeneous and previously ADC-treated tumours | Reduces therapeutic consistency, creates cross-resistance risks and limits sequential use of ADCs sharing similar targets or payload mechanisms |
Complex Linker-Payload Manufacturing and Constrained Commercial-Scale Conjugation Capacity | 23.4% | Production scalability, batch consistency and supply reliability | Commercial launches, geographic expansion and late-stage clinical programmes | Raises manufacturing costs, lengthens technology-transfer timelines and exposes companies to shortages in specialized linker, payload and conjugation capacity |
Fragmented Biomarker Thresholds and Limited Companion-Diagnostic Access | 17.8% | Patient identification, reimbursement and treatment adoption | HER2-low, HER2-ultralow, Trop-2, FRα, B7-H3 and Claudin 18.2-directed ADCs | Produces inconsistent eligibility decisions, slows clinical uptake and restricts adoption in markets lacking standardized pathology and molecular-testing infrastructure |
Restraint: Dose-Limiting Interstitial Lung Disease, Ocular Toxicity and Haematological Adverse Events
The commercial potential of ADCs is constrained by toxicities arising from target expression in healthy tissues, premature payload release and systemic exposure to highly potent cytotoxic agents. Interstitial lung disease remains a critical concern for selected HER2-directed and topoisomerase-based ADCs, while ocular toxicity, neutropenia, thrombocytopenia, anaemia and peripheral neuropathy affect other platforms. These adverse events can require intensive monitoring, dose interruption, dose reduction or permanent discontinuation, limiting treatment continuity and real-world effectiveness among older or clinically vulnerable patients.
Toxicity also influences regulatory requirements, physician confidence, reimbursement decisions and positioning against alternative therapies. Hospitals require multidisciplinary protocols involving oncologists, pulmonologists, ophthalmologists and laboratory teams, increasing care complexity and total treatment costs. Developers must therefore prioritize tumour-selective antibodies, stable linkers, optimized drug-to-antibody ratios and payloads with wider therapeutic windows. Competitive differentiation will increasingly depend on demonstrating that improved efficacy does not create disproportionate safety burdens. Companies providing clear monitoring algorithms, predictive biomarkers and effective adverse-event mitigation strategies will be better positioned to support earlier-line adoption and combination therapy.
Antibody-Drug Conjugates (ADC) Market Geographical Penetration
U.S. Antibody-Drug Conjugates (ADC) Market Landscape
The U.S. antibody-drug conjugates market is moving from late-line oncology use toward earlier, biomarker-selected treatment. As of April 2025, the FDA had approved 14 ADCs across solid and haematological malignancies, establishing a broad commercial base spanning HER2, Trop-2, CD30, CD79b, Nectin-4 and FRα. The January 2025 approval of Datroway for previously treated HR-positive, HER2-negative metastatic breast cancer and the May approval of Emrelis for c-MET-high non-small cell lung cancer expanded target diversity. Adoption is concentrated within comprehensive cancer centres that can support companion testing, infusion delivery and toxicity monitoring.
Daiichi Sankyo and AstraZeneca, Pfizer, Roche, Gilead, AbbVie, and Astellas lead competition, with differentiation shifting toward a superior therapeutic index, earlier-line evidence, and combination strategies. In May 2026, Enhertu gained two U.S. indications in HER2-positive early breast cancer, reinforcing the transition of ADCs into curative-intent settings. Commercial expansion nevertheless depends on payer authorization, standardized antigen scoring and effective management of interstitial lung disease, ocular toxicity and haematological events. The next value pool will favour companies linking advanced diagnostics, community-oncology education, scalable manufacturing and real-world evidence with clearly differentiated clinical outcomes.
Japan Antibody-Drug Conjugates (ADC) Market Outlook
Japan’s antibody-drug conjugates market is positioned for sustained expansion, supported by oncology infrastructure, centralized specialist care and domestic leadership in ADC engineering. Daiichi Sankyo anchors the ecosystem through its DXd platform and reported nine ADCs in clinical development in 2025, spanning HER2, Trop-2, HER3 and B7-H3 targets. Japan’s early approval of Datroway for previously treated HR-positive, HER2-negative breast cancer has broadened competition beyond established products including Enhertu, Kadcyla, Adcetris, Polivy and Padcev. Adoption is strongest in major cancer centres capable of standardized antigen testing and intensive toxicity monitoring.
The outlook increasingly depends on moving ADCs into earlier treatment lines and extending development across gastric, lung, breast, ovarian and haematological cancers. Domestic companies benefit from strong translational research and proximity to PMDA consultations, while collaborations with AstraZeneca, Merck and other international partners provide global development scale. However, reimbursement scrutiny, an ageing treatment population, interstitial lung disease risk and uneven biomarker-testing capacity outside urban centres may moderate uptake. Competitive advantage will favour developers combining differentiated linker-payload technology, Japan-specific evidence, reliable manufacturing, companion diagnostics and clear treatment-sequencing strategies within the national insurance system.
Antibody-Drug Conjugates (ADC) Market Competitive Landscape
- The global antibody-drug conjugates market is characterized by strong competition among established pharmaceutical companies, specialized biotechnology firms and emerging Asian developers. Daiichi Sankyo and AstraZeneca maintain leadership through their DXd-based portfolio, while Pfizer has strengthened its position by integrating Seagen’s commercial products, platform capabilities and development pipeline. Roche, Gilead Sciences, AbbVie, GSK and Astellas Pharma maintain competitive relevance through approved ADCs across breast cancer, lymphoma, ovarian cancer, multiple myeloma and urothelial cancer. Competition increasingly centres on target selection, linker stability, payload potency, drug-to-antibody ratio, safety management, manufacturing consistency and successful movement into earlier treatment settings.
- The next phase of competition will be shaped by expansion beyond established HER2 and Trop-2 targets toward B7-H3, HER3, Claudin 18.2, FRα and other tumour-associated antigens. Merck, BioNTech, Genmab and Johnson & Johnson are strengthening their positions through licensing agreements, acquisitions and portfolio partnerships, while DualityBio, Kelun-Biotech, RemeGen, Innovent Biologics and Hansoh Pharma are emerging as important innovation sources. Sustainable leadership will depend on differentiated clinical outcomes, effective biomarker strategies, scalable manufacturing, regulatory execution and disciplined portfolio prioritization across crowded oncology indications. Combination strategies involving immunotherapies and targeted agents will further influence treatment sequencing, competitive positioning and commercial adoption.
Key Companies of Antibody-Drug Conjugates (ADC) Market
- Daiichi Sankyo Company, Limited (Japan)
- AstraZeneca plc (United Kingdom)
- Pfizer Inc. (United States)
- F. Hoffmann-La Roche Ltd (Switzerland)
- Gilead Sciences, Inc. (United States)
- AbbVie Inc. (United States)
- Astellas Pharma Inc. (Japan)
- GSK plc (United Kingdom)
- Merck & Co., Inc. (United States)
- Genmab A/S (Denmark)
- BioNTech SE (Germany)
- RemeGen Co., Ltd. (China)
- Sichuan Kelun-Biotech Biopharmaceutical Co., Ltd. (China)
- ADC Therapeutics SA (Switzerland)
- Johnson & Johnson (United States)
- Duality Biologics Co., Ltd. (China)
- Innovent Biologics, Inc. (China)
- Hansoh Pharmaceutical Group Company Limited (China)
- Bristol Myers Squibb Company (United States)
- Sutro Biopharma, Inc. (United States)
Antibody-Drug Conjugates (ADC) Market Recent Developments
- September 2026 - Cipla and Sino Biopharmaceutical: Cipla entered an exclusive licensing and supply agreement for rolditamig deuderuxtecan, TQB2102, a HER2-directed bispecific ADC. Cipla received development and commercialization rights across India, South Africa and five additional emerging markets, while Chia Tai Tianqing will retain manufacturing responsibility. The transaction expands access to next-generation ADCs outside established markets.
- September 2026 - Cohance Lifesciences: Cohance announced an additional US$13 million investment in NJ Bio and a US$5 million controlling investment in Aruka Bio. The transactions strengthen its end-to-end ADC capabilities spanning discovery, linker-payload development, conjugation, manufacturing and co-development.
- July 2026 - Glenmark Pharmaceuticals: Glenmark Specialty initiated a multi-country Phase III study of trastuzumab rezetecan, SHR-A1811, in platinum-resistant ovarian cancer, with India becoming the first licensed market to begin enrolment. Expansion into Australia and South Korea is planned subject to regulatory clearances.
- June 2026 - Pfizer Portfolio Rationalization: Pfizer reported a late-stage setback involving a legacy Seagen ADC programme and subsequently reassessed parts of its investigational ADC portfolio. The development emphasizes increasing pressure on companies to prioritize assets offering differentiated efficacy, safety and target biology.
What DATAM Uniquely Provides
- In-depth segmentation of the antibody-drug conjugates market by product type, target type, linker technology, payload technology, cancer indication, treatment line, development stage, route of administration, end user and region.
- Competitive analysis of leading ADC companies covering approved products, clinical pipelines, overall survival, progression-free survival, objective response, response durability, safety, target antigen, linker-payload architecture, dosing, pipeline maturity and commercialization strategy.
- Comprehensive assessment of treatment-eligible populations by HER2, Trop-2, CD30, CD22, CD79b, Nectin-4, FRα, BCMA, HER3, B7-H3, Claudin 18.2 and c-MET expression, including low-expression, heterogeneous, refractory and previously ADC-treated populations.
- Actionable intelligence on ADC pricing, reimbursement, regulatory pathways, companion diagnostics, antigen-expression testing, treatment sequencing, adverse-event management, manufacturing capacity, patient-support programmes, licensing activity, strategic partnerships and investment opportunities.
- Analyst forecasts highlighting high-growth target classes, commercially attractive cancer indications, regional expansion opportunities and emerging competitive threats across conventional ADCs, bispecific ADCs, dual-payload ADCs, immune-stimulating antibody conjugates and site-specific conjugation platforms, supported by tracking of recent approvals, clinical results, trial initiations, pipeline discontinuations, acquisitions and manufacturing investments.




























































