


Hypercholesterolemia Treatment Market Overview
The hypercholesterolemia treatment market reached US$22.72 billion in 2025 and is expected to reach US$68.7 billion by 2035, growing with a CAGR of 11.7% during the forecast period 2026-2035.
The global hypercholesterolemia treatment market is expanding steadily as rising cardiovascular disease risk, increasing detection of elevated ldl-c levels, and broader lipid screening strengthen demand for long-term cholesterol management.Statins remain the foundation of treatment; however, therapeutic strategies are increasingly shifting toward non-statin and combination approaches for patients who fail to achieve recommended LDL-C targets or experience statin intolerance.
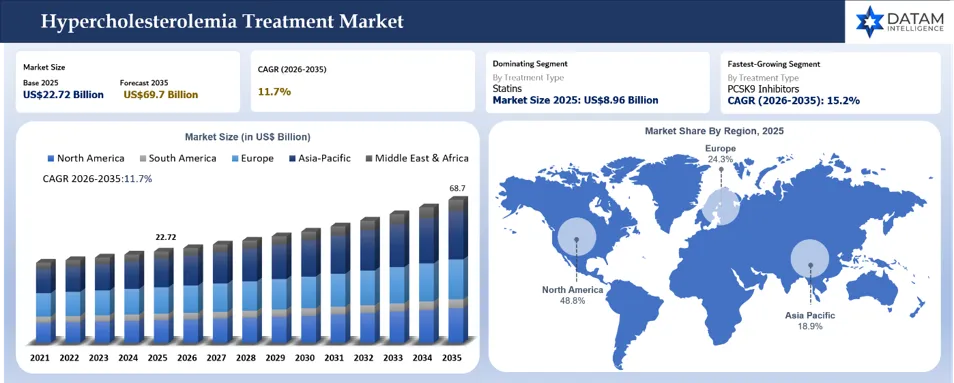
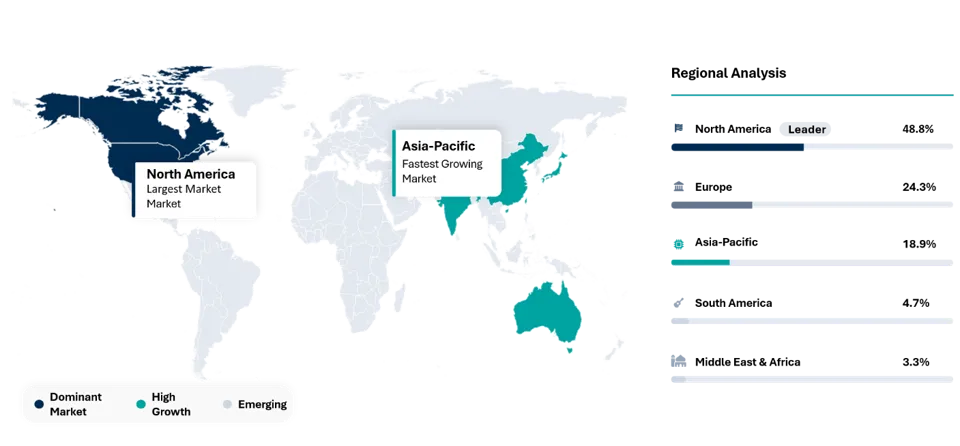
PCSK9 inhibitors, inclisiran, bempedoic acid, ezetimibe, and emerging oral PCSK9 therapies are broadening treatment options and intensifying competition. Innovation is also progressing toward long-acting RNA-based therapies, gene-editing platforms, and fixed-dose combinations designed to improve adherence and durability. North America remains the leading regional market, supported by advanced cardiovascular care and rapid therapeutic adoption, while Asia-Pacific is gaining importance through expanding diagnosis, healthcare access, and preventive cardiovascular management.
Hypercholesterolemia Treatment Market Key Takeaways
- The global Hypercholesterolemia Treatment Market is estimated at US$22.72 billion in 2025 and projected to reach approximately US$68.7 billion by 2035, growing at a 11.7% CAGR during 2026-2035.
- Market expansion is driven by increasing hypercholesterolemia prevalence, greater cardiovascular-risk screening, improved diagnosis of familial hypercholesterolemia, and stronger focus on preventive lipid management.
- PCSK9 inhibitors and other advanced non-statin therapies are gaining importance due to strong LDL-C reduction, cardiovascular-outcomes evidence, improved dosing convenience, and applicability in inadequately controlled patients.
- North America remains the leading regional market, supported by advanced healthcare infrastructure, high diagnosis rates, favorable treatment access, strong reimbursement systems, and rapid adoption of innovative lipid-lowering therapies.
- Major growth opportunities exist in oral PCSK9 inhibitors, fixed-dose combinations, long-acting RNA therapies, gene-editing approaches, and precision lipid-management solutions, while high treatment costs and reimbursement restrictions remain key restraints.
Hypercholesterolemia Treatment Market Scope
| Metrics | Details | |
| 2025 Market Size | US$22.72 Billion | |
| 2035 Projected Market Size | US$68.7 Billion | |
| CAGR (2026-2035) | 11.7% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Disease Type | Genetic Hypercholesterolemia (Familial Hypercholesterolemia), Acquired Hypercholesterolemia | |
| By Treatment Type | Statins, PCSK9 Inhibitors, Ezetimibe, Bile Acid Sequestrants, Niacin, Bempedoic Acid, Others | |
| By Distribution Channel | Hospital Pharmacies, Retail Pharmacies, Online Pharmacies | |
| By End-User | Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Academic and Research Institutes, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Hypercholesterolemia Treatment Market White Space & Investment Opportunities
Next-Generation Oral LDL-C Lowering Therapies:
Invest in oral therapies that can deliver substantial LDL-C reduction without injections, particularly for patients who remain above target despite statins or who are unwilling to use injectable treatments. Opportunities are attractive for oral PCSK9 inhibitors, ATP citrate lyase inhibitors, and fixed-dose combinations that improve convenience, adherence, and treatment persistence while reducing dependence on frequent clinical administration.
Long-Acting and One-Time Treatment Approaches:
Develop long-duration therapies based on RNA interference, gene silencing, and gene-editing technologies capable of maintaining LDL-C control with infrequent or potentially single-dose administration. Such approaches could address poor adherence associated with daily medicines and create differentiated options for familial hypercholesterolemia and very high cardiovascular-risk populations.
Fixed-Dose Combination Therapies:
Expand combination products integrating complementary lipid-lowering mechanisms such as statins, ezetimibe, bempedoic acid, and emerging PCSK9-targeting therapies. Fixed-dose combinations can simplify treatment regimens, improve adherence, support greater LDL-C reduction, and provide commercially attractive options for patients requiring treatment intensification beyond single-agent therapy.
Precision Lipid Management and Risk Stratification:
Develop diagnostic and clinical decision-support solutions that integrate LDL-C levels, lipoprotein(a), genetic risk, familial hypercholesterolemia screening, imaging, and broader cardiovascular-risk factors. Improved patient stratification can support earlier treatment escalation, identify candidates for advanced therapies, reduce undertreatment, and enable more personalized therapy selection across primary and secondary cardiovascular prevention populations.
Hypercholesterolemia Treatment Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- LDL-C Reduction Efficacy
- Cardiovascular Risk Reduction Evidence
- Speed and Durability of LDL-C Lowering
- Safety and Tolerability Profile
- Route of Administration
- Dosing Frequency and Treatment Convenience
- Suitability for Statin-Intolerant Patients
- Effectiveness in Familial Hypercholesterolemia
- Compatibility With Statins and Other Lipid-Lowering Therapies
- Requirement for Combination Therapy
- Patient Adherence and Treatment Persistence
- Drug-Drug Interaction Profile
- Clinical Guideline Positioning
- Regulatory Approval and Label Coverage
- Reimbursement and Insurance Coverage
- Prior Authorization Requirements
- Treatment Cost and Patient Out-of-Pocket Burden
- Availability Through Hospital, Retail and Online Pharmacies
- Physician Familiarity and Prescribing Preference
- Long-Term Cardiovascular Outcomes Evidence
- Suitability by Baseline LDL-C and Cardiovascular Risk Category
- Convenience of Monitoring and Follow-Up
- Patient Preference for Oral Versus Injectable Therapy
- Real-World Effectiveness and Safety Evidence
Hypercholesterolemia Treatment Market BCG Matrix: Company Evaluation
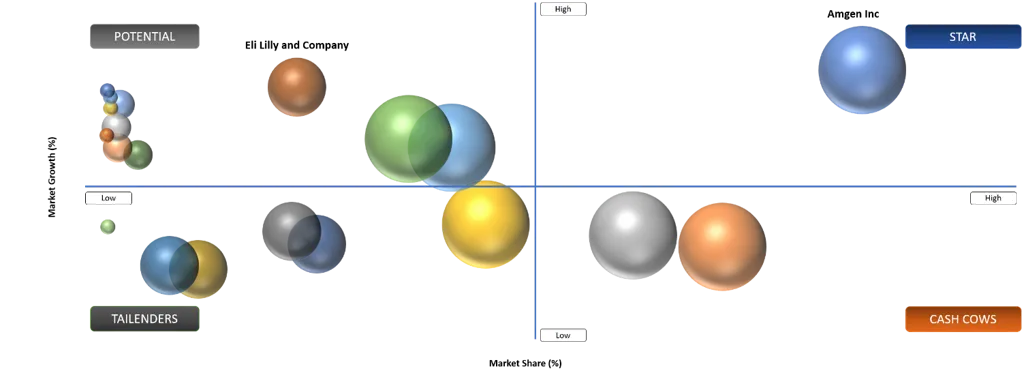
STAR
Amgen Inc., Novartis AG, Regeneron Pharmaceuticals, Inc., Sanofi S.A., and Merck & Co., Inc. represent the Star category in the Hypercholesterolemia Treatment Market due to their established commercial presence, differentiated lipid-lowering therapies, and continued clinical and regulatory expansion. Amgen maintains a strong position through Repatha, supported by extensive cardiovascular-outcomes evidence and broader treatment indications. Novartis strengthens the category through Leqvio, a twice-yearly maintenance therapy supported by the large VICTORION clinical program. Regeneron and Sanofi maintain participation through established PCSK9-targeting therapy, while Merck entered the commercial market with Lipfendra, the first FDA-approved once-daily oral PCSK9 inhibitor, approved in July 2026. These companies benefit from established commercialization capabilities, strong clinical evidence, broad geographic reach, and continued investment in next-generation cholesterol-lowering approaches.
POTENTIAL
NewAmsterdam Pharma Company N.V., Eli Lilly and Company, Arrowhead Pharmaceuticals, Inc., AstraZeneca PLC, and LIB Therapeutics Inc. represent the Potential category in the Hypercholesterolemia Treatment Market due to their expanding pipelines and focus on next-generation LDL-C lowering therapies. NewAmsterdam Pharma is advancing obicetrapib, including a fixed-dose combination with ezetimibe, supported by Phase 3 studies and a positive CHMP opinion in 2026. Eli Lilly is progressing VERVE-102, an investigational PCSK9 base-editing therapy designed for durable LDL-C reduction following a single treatment. Arrowhead Pharmaceuticals is advancing zodasiran in Phase 3 for homozygous familial hypercholesterolemia. AstraZeneca is developing oral PCSK9 inhibitor AZD0780, while LIB Therapeutics is expanding commercialization of once-monthly PCSK9 inhibitor LEROCHOL.
Hypercholesterolemia Treatment Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Rising Burden of Hypercholesterolemia and Cardiovascular Risk | 15.2% | Patient diagnosis and treatment demand | Patients with elevated LDL-C and high cardiovascular risk | Increasing identification of elevated cholesterol and cardiovascular risk expands the treatment-eligible population and supports sustained demand for lipid-lowering therapies. |
Growing Adoption of Advanced Non-Statin Therapies | 12.8% | Treatment intensification | Statin-intolerant and inadequately controlled patients | Greater use of PCSK9 inhibitors, bempedoic acid, inclisiran and combination therapies expands treatment options for patients not reaching LDL-C goals with statins alone. |
Expansion of Screening and Preventive Cardiovascular Care | 10.7% | Early diagnosis and intervention | Primary prevention and high-risk populations | Wider lipid screening, risk assessment and earlier therapeutic intervention increase diagnosis rates and support longer treatment duration across broader patient groups. |
Driver: Rising Burden of Hypercholesterolemia and Cardiovascular Risk
The rising burden of hypercholesterolemia and associated cardiovascular risk is a major driver of the Hypercholesterolemia Treatment Market. Increasing detection of elevated LDL-C, greater awareness of cardiovascular prevention, and broader screening of high-risk populations are expanding the number of patients eligible for lipid-lowering therapy. Persistent cholesterol elevation is closely associated with atherosclerotic cardiovascular disease, encouraging physicians to initiate treatment earlier and intensify therapy when LDL-C targets are not achieved. Growing use of combination regimens and advanced non-statin therapies further supports market expansion, particularly among patients with familial hypercholesterolemia, established cardiovascular disease, statin intolerance, or inadequate response to conventional statin treatment.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Cost of Advanced Lipid-Lowering Therapies | 13.8% | Treatment affordability and reimbursement | Patients requiring PCSK9 inhibitors and other non-statin therapies | High treatment costs and payer authorization requirements can restrict access to advanced therapies, delay treatment escalation, and sustain reliance on lower-cost conventional drugs. |
Low Diagnosis and Treatment Adherence | 11.6% | Patient identification and long-term disease management | Undiagnosed patients and patients receiving chronic lipid-lowering therapy | Limited screening, asymptomatic disease progression, treatment discontinuation, and inconsistent medication adherence can reduce the eligible treated population and weaken long-term therapeutic uptake. |
Strong Generic Statin Competition | 9.4% | Pricing and premium therapy adoption | Patients adequately controlled with first-line statins | Wide availability of inexpensive generic statins can limit adoption of higher-priced branded and next-generation therapies, particularly among patients who achieve sufficient LDL-C reduction with conventional treatment. |
Restraint: High Cost of Advanced Lipid-Lowering Therapies
The high cost of advanced lipid-lowering therapies remains a significant restraint on the Hypercholesterolemia Treatment Market, particularly for PCSK9 inhibitors and other branded non-statin treatments. Although these therapies offer substantial LDL-C reduction for high-risk and inadequately controlled patients, their higher acquisition costs can limit broad adoption compared with widely available generic statins and ezetimibe. Reimbursement restrictions, prior-authorization requirements, step-therapy protocols, and patient out-of-pocket expenses may further delay treatment initiation or escalation. These affordability barriers are particularly relevant in cost-sensitive healthcare systems, potentially restricting access to innovative therapies and slowing penetration among eligible patients despite demonstrated clinical benefits.
Hypercholesterolemia Treatment Market Segment Analysis
The global hypercholesterolemia treatment market is segmented based on disease type, treatment type, distribution channel, and region.
Statins in the treatment type segment are dominating with the highest market share of 45.6% of market share in the global hypercholesterolemia treatment market.
Statins are the most widely used drugs for hypercholesterolemia due to their proven ability to significantly lower low-density lipoprotein cholesterol (LDL-C). This class includes drugs like atorvastatin, simvastatin, and rosuvastatin, which can reduce LDL-C by 30% to 50%, depending on the dose, and have been shown to reduce the risk of heart attacks, strokes, and cardiovascular-related deaths.
Their widespread use is supported by decades of clinical trial data, which demonstrated that statins improve survival in high-risk patients. In addition to efficacy, statins are generally safe and well-tolerated, with rare serious side effects. The availability of generic versions has made statins affordable and accessible worldwide, contributing to their dominance in the hypercholesterolemia treatment market.
Moreover, international guidelines, such as those from the American College of Cardiology (ACC) and the European Society of Cardiology (ESC), recommend statins as first-line therapy for managing hypercholesterolemia. Alternative treatments like ezetimibe or PCSK9 inhibitors exist but are typically used as add-on therapies or in statin-intolerant patients due to higher costs. Altogether, this combination of efficacy, safety, cost-effectiveness, and strong clinical endorsement explains why statins hold the largest market share in cholesterol management.
Hypercholesterolemia Treatment Market Geographical Penetration
U.S. Hypercholesterolemia Treatment Market Landscape
The United States represents a major market for hypercholesterolemia treatment, supported by a large patient population, widespread lipid screening, strong reimbursement infrastructure, and rapid adoption of advanced lipid-lowering therapies. The 2026 ACC/AHA dyslipidemia guideline emphasizes earlier intervention, LDL-C treatment goals, broader risk assessment, and use of newer therapies for patients inadequately controlled with conventional treatment. Approximately one in four U.S. adults has high LDL-C, underscoring the substantial treatment need. In July 2026, the FDA approved the first once-daily oral PCSK9 inhibitor, further expanding treatment options beyond statins, ezetimibe, injectable PCSK9 therapies, and bempedoic acid.
Japan Hypercholesterolemia Treatment Market Outlook
Japan represents an important hypercholesterolemia treatment market, supported by an aging population, established cardiovascular-risk management practices, broad use of statins and ezetimibe, and increasing availability of non-statin therapies. Treatment demand is particularly relevant among patients who fail to achieve LDL-C targets with statins or experience statin-related adverse effects. In September 2025, Japan’s Ministry of Health, Labour and Welfare approved bempedoic acid for hypercholesterolemia and familial hypercholesterolemia, expanding oral non-statin treatment options. The therapy was commercially launched in Japan in November 2025, strengthening treatment choice for patients requiring additional LDL-C reduction and supporting further diversification of the country’s lipid-management landscape.
Hypercholesterolemia Treatment Market Competitive Landscape
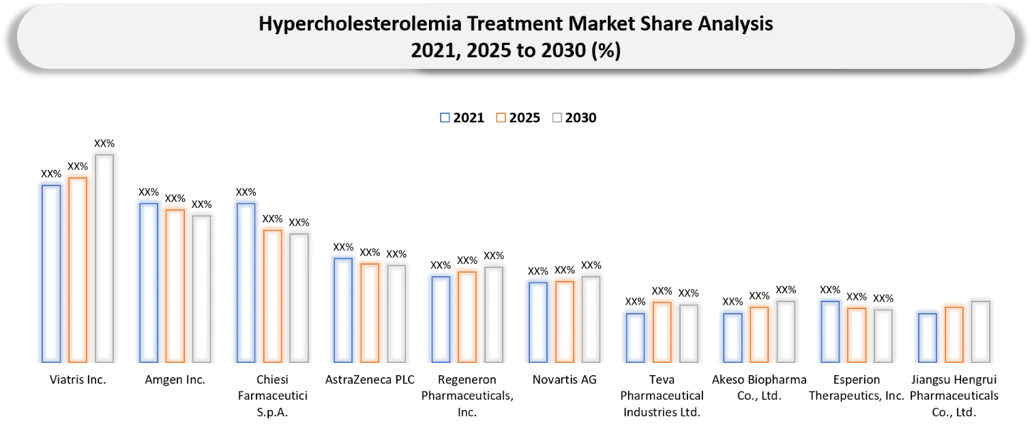
- The global hypercholesterolemia treatment market is characterized by the presence of large pharmaceutical companies, biotechnology firms, and generic-drug manufacturers competing across statins, PCSK9 inhibitors, cholesterol-absorption inhibitors, bempedoic acid, and combination therapies. Major participants include Amgen Inc., Novartis AG, Regeneron Pharmaceuticals, Inc., Merck & Co., Inc., Esperion Therapeutics, Inc., Sanofi S.A., AstraZeneca PLC, Viatris Inc., Teva Pharmaceutical Industries Ltd., and Daiichi Sankyo Company, Limited. Competition is increasingly shifting from conventional statin-based therapy toward differentiated non-statin treatments offering stronger LDL-C reduction, improved dosing convenience, and options for patients unable to achieve recommended cholesterol targets with existing therapies.
- Innovation in the PCSK9 segment is particularly significant. Amgen continues to strengthen its Repatha franchise through expanded clinical evidence, while Novartis is developing the long-term positioning of inclisiran through its large VICTORION clinical program. In July 2026, Merck received U.S. FDA approval for LIPFENDRA (enlicitide), the first approved once-daily oral PCSK9 inhibitor for adults with hypercholesterolemia, introducing a new oral alternative to injectable PCSK9 therapies. Esperion is strengthening its presence through NEXLETOL and NEXLIZET and is advancing oral combination approaches, while partnerships with Otsuka and other regional companies support international commercialization. Going forward, competitive differentiation is expected to center on LDL-C reduction, cardiovascular-outcomes evidence, oral versus injectable administration, dosing frequency, combination therapy, reimbursement access, geographic expansion, and lifecycle-management strategies.
Key Companies of the Hypercholesterolemia Treatment Market
- Viatris Inc. (United States)
- Amgen Inc. (United States)
- Chiesi Farmaceutici S.p.A. (Italy)
- AstraZeneca PLC (United Kingdom)
- Regeneron Pharmaceuticals, Inc. (United States)
- Novartis AG (Switzerland)
- Teva Pharmaceutical Industries Ltd. (Israel)
- Akeso Biopharma Co., Ltd. (China)
- Esperion Therapeutics, Inc. (United States)
- Jiangsu Hengrui Pharmaceuticals Co., Ltd. (China)
- Merck & Co., Inc. (United States)
- Otsuka Pharmaceutical Co., Ltd. (Japan)
- Daiichi Sankyo Company, Limited (Japan)
- Sanofi S.A. (France)
- Sun Pharmaceutical Industries Limited (India)
- Dr. Reddy’s Laboratories Limited (India)
- Lupin Limited (India)
- Cipla Limited (India)
- Zydus Lifesciences Limited (India)
- Aurobindo Pharma Limited (India)
Hypercholesterolemia Treatment Market Recent Developments
- August 2026: Amgen reported additional Phase 3 VESALIUS-CV results for Repatha (evolocumab) in more than 12,000 high-risk patients without a prior heart attack or stroke. Repatha reduced the risk of all-cause death by 20%, while earlier VESALIUS-CV findings showed a 25% reduction in the risk of coronary heart disease death, heart attack or ischemic stroke.
- August 2026: The U.S. FDA updated the label for Novartis’ Leqvio (inclisiran) to recognize that lowering LDL-C reduces the risk of major adverse cardiovascular events in adults at increased cardiovascular risk. Novartis is continuing its VICTORION clinical development program, which includes more than 60,000 patients across over 30 clinical trials in more than 50 countries.
- July 2026: The U.S. FDA approved Merck’s Lipfendra (enlicitide), the first once-daily oral PCSK9 inhibitor for reducing LDL-C in adults with hypercholesterolemia, including heterozygous familial hypercholesterolemia. In the Phase 3 CORALreef Lipids and CORALreef HeFH trials, Lipfendra reduced LDL-C by a placebo-adjusted 56% and 59%, respectively, at week 24.
- July 2026: The European Medicines Agency’s Committee for Medicinal Products for Human Use adopted a positive opinion supporting broader use of Amgen’s Repatha in adults with established or high risk of atherosclerotic cardiovascular disease. The recommendation was supported by the Phase 3 VESALIUS-CV study involving more than 12,000 patients and subsequently supported an expanded European indication.
What DATAM Uniquely Provides
- In-depth segmentation of the Hypercholesterolemia Treatment Market by disease type, treatment type, distribution channel and region, with additional assessment of familial hypercholesterolemia, acquired hypercholesterolemia, statins, PCSK9 inhibitors, ezetimibe, bempedoic acid and other emerging lipid-lowering therapies.
- Competitive analysis of leading hypercholesterolemia treatment companies covering marketed product portfolios, mechanism of action, LDL-C reduction efficacy, dosing frequency, route of administration, safety profile, regulatory status, pipeline maturity, commercialization strategy, geographic expansion and lifecycle-management initiatives.
- Comprehensive assessment of diagnosed and treatment-eligible hypercholesterolemia populations, including analysis of familial and non-familial disease, statin-intolerant patients, high cardiovascular-risk populations, patients inadequately controlled on existing therapies, treatment adherence, unmet clinical needs and regional diagnosis and treatment patterns.
- Actionable intelligence on pharmaceutical pricing, reimbursement pathways, treatment guidelines, formulary access, payer restrictions, prescription trends, combination-treatment strategies, patient-support programs, clinical development activity, regulatory approvals, licensing agreements, strategic partnerships and market-access barriers.
- Detailed evaluation of current and emerging treatment modalities, including statins, PCSK9 monoclonal antibodies, small interfering RNA therapies, oral PCSK9 inhibitors, cholesterol-absorption inhibitors, ATP citrate lyase inhibitors and next-generation gene-silencing and gene-editing approaches.
- Analyst forecasts highlighting high-growth drug classes, commercially attractive patient groups, evolving treatment sequencing, oral versus injectable therapy adoption, emerging combination therapies, pipeline opportunities and potential whitespace across developed and emerging hypercholesterolemia treatment markets.




























































