


Hydrogen Compressor Market Size and Overview
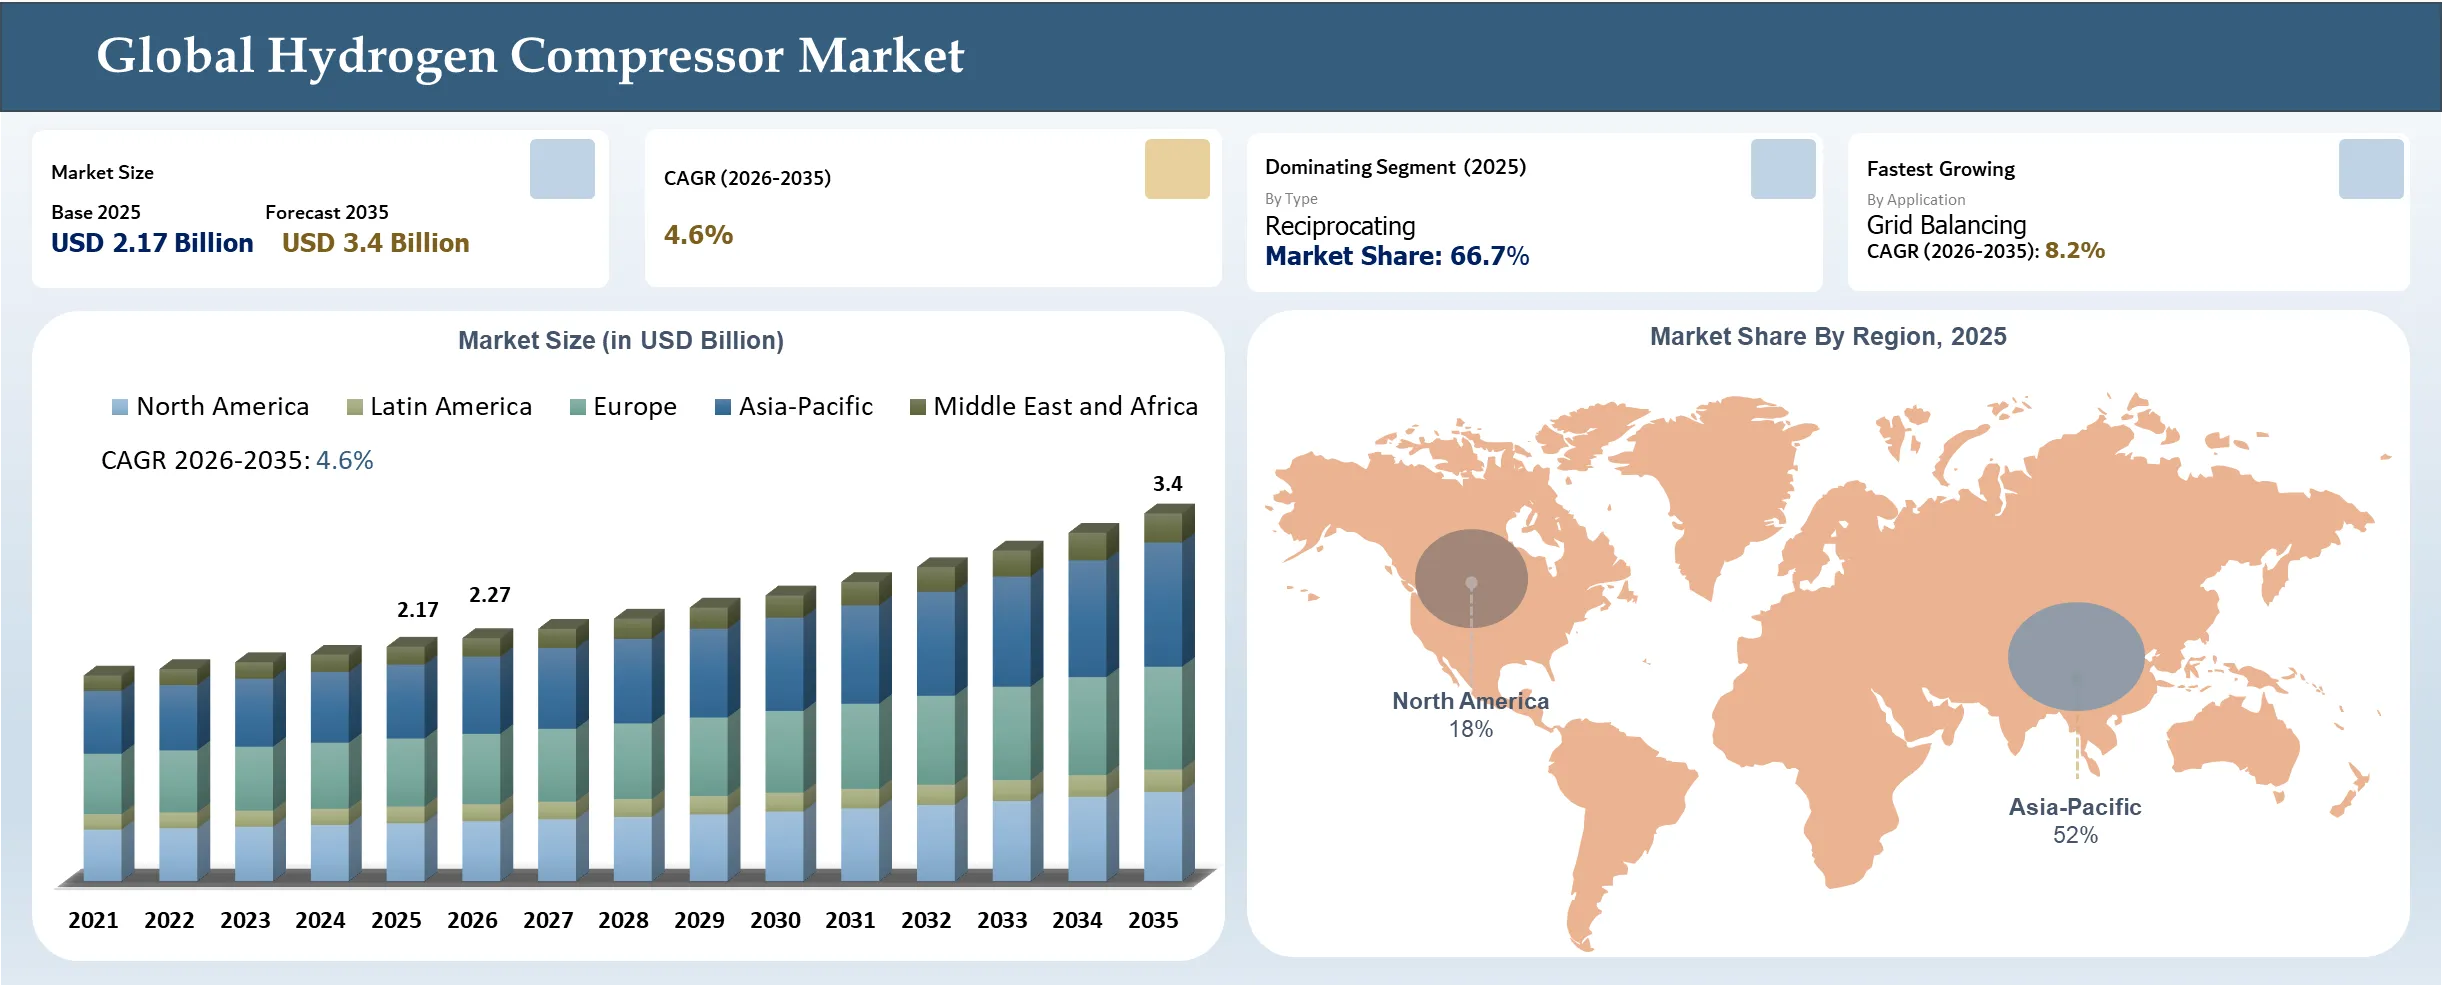
The global hydrogen compressor market reached USD 2.17 billion in 2025 and is expected to reach USD 3.4 billion by 2035, growing with a CAGR of 4.6% during the forecast period 2026-2035. The market is expanding as hydrogen production, storage, transportation, processing, and mobility applications require compression systems to raise hydrogen pressure for efficient handling and utilisation. According to the International Energy Agency (IEA), global hydrogen consumption rose by almost 3% in 2025 and exceeded 100 million tonnes, whereas hydrogen production with minimal emissions grew by 20% and reached almost 1 million tonnes.
The increase in hydrogen infrastructure is increasing the need for compressors that operate under high pressure and high purity to facilitate hydrogen storage and transport. In April 2025, Burckhardt Compression secured an order from a leading Swedish gas company to deliver its MD10-L diaphragm compressor package for hydrogen trailer filling. It is a standardised, skid-mounted, and container-based unit capable of delivering high-pressure hydrogen, set for delivery in 2025. Burckhardt Compression claims the MD10-L can process 500 normal cubic meters of hydrogen per hour, equivalent to 2-2.5 MW electrolyser capacity at 30-40 barg.
White-Space Opportunities for Hydrogen Compressor Manufacturing and Hydrogen Infrastructure Expansion
In February 2026, the European Commission approved a €3 billion (USD 3.36 billion) German state-aid scheme to expand manufacturing capacity for net-zero technologies and their key components, creating a wide-space opportunity for the hydrogen compressor market because H₂ compressors are included among the eligible hydrogen technologies.
The largest investment area within the scheme is not individually allocated to hydrogen compressors; the €3 billion envelope covers a broad range of cleantech manufacturing, including hydrogen technologies and components, electrolysers, fuel-cell equipment, renewable-energy technologies, energy-storage equipment, heat pumps, and related critical raw materials.
The aid can be provided through grants, tax advantages, interest subsidies, and loan guarantees and is available to companies across Germany through 2030. For hydrogen compressors specifically, the opportunity is concentrated around manufacturing and capacity expansion for high-pressure compression equipment, hydrogen refuelling infrastructure, pipeline compression, storage compression, and compressor packages integrated with electrolysers and hydrogen production facilities.
The investment is expected to create opportunities for companies across the hydrogen-compression, hydrogen-production, storage, transportation, refuelling, and fuel-cell equipment value chains. In hydrogen compression, NEUMAN & ESSER (NEA Group), Burckhardt Compression, Howden, Atlas Copco, Sauer Compressors, and HAUG Kompressoren can benefit from increasing demand for reciprocating, diaphragm, piston, and oil-free compressor systems used for hydrogen production, storage, transport, and refuelling.
In hydrogen production and electrolyser equipment, Siemens Energy, thyssenkrupp nucera, Sunfire, Nel, ITM Power, and Plug Power are positioned to benefit from manufacturing and deployment of electrolysers and integrated hydrogen-production systems.
Hydrogen Compressor Market Key Takeaways
- Asia-Pacific led the global hydrogen compressor market by capturing a 52.0% market share in 2025. This market growth is driven by heavy investments in electrolysers and refuelling infrastructure across China, Japan, South Korea, and Australia.
- Reciprocating compressors held a dominant position in the market with a 66.7% share in 2025. Their ability to deliver high pressures for multi-stage compression makes them ideal for hydrogen refuelling and tube-trailer storage.
- Heavy-duty hydrogen vehicle deployments (buses, trucks, and trains) contribute a 28% growth impact to the market. Heavy-duty transport requires higher-capacity, parallel-compression systems due to larger hydrogen volumes per refuelling cycle.
- A major €3 billion (USD 3.36 billion) German state-aid scheme was approved by the European Commission in February 2026. Running through 2030, this initiative funds net-zero cleantech manufacturing, including high-pressure hydrogen compressors and refuelling equipment.
Hydrogen Compressor Market Industry Trends and Strategic Insight
- Shift toward application-specific compressor selection. Compressor technology is increasingly being selected according to hydrogen flow rate, pressure ratio, purity requirements, operating flexibility, and site conditions rather than using a single compression technology across applications.
- Expansion of high-pressure trailer-filling systems. Hydrogen producers are increasingly using high-pressure compression to fill tube trailers, providing a flexible distribution route where dedicated hydrogen pipeline infrastructure is not yet available.
- Increasing adoption of high-flow compression for heavy mobility. Hydrogen compression systems are being developed around the requirements of truck, bus, and train refuelling, where higher throughput and rapid dispensing are more important than the smaller flow requirements of passenger-vehicle stations.
- Compression is becoming a critical infrastructure-enabling technology. Expansion of hydrogen storage, pipelines, refuelling networks, industrial hydrogen use, and hydrogen-derived fuels is positioning compression as a core component across the hydrogen value chain rather than a standalone equipment category.
- Strategic shift toward lifecycle economics. Customers are increasingly evaluating compressor suppliers on energy efficiency, maintenance requirements, reliability, footprint, installation time, and lifetime operating cost in addition to initial equipment price.
Hydrogen Compressor Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 2.17 Billion | |
| 2035 Projected Market Size | USD 3.4 Billion | |
| CAGR (2026-2035) | 4.6% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | Asia-Pacific | |
| By Type | Centrifugal, Reciprocating, Screw | |
| By Pressure Limit | 200 to 500 psi, 501 to 900 psi, Others | |
| By Flow Limit | Low Flow, Medium Flow, High Flow | |
| By Power Consumption | Low Power (Up to 100 kW), Medium Power (100 kW to 500 kW), High Power (Above 500 kW) | |
| By Oil Free | Standard Oil-Free Compressors, High-Purity Oil-Free Compressors | |
| By Running Reference | Pressure Reference, Temperature Reference, Flow Rate Reference, Power Consumption Reference, Efficiency Reference | |
| By Application | Energy storage solutions, Grid balancing, Food processing, Power station cooling, Others | |
| By End-User | Hydrogen Filling Stations, Oil & Gas Energy Storage, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Hydrogen Compressor Market Disruption Analysis
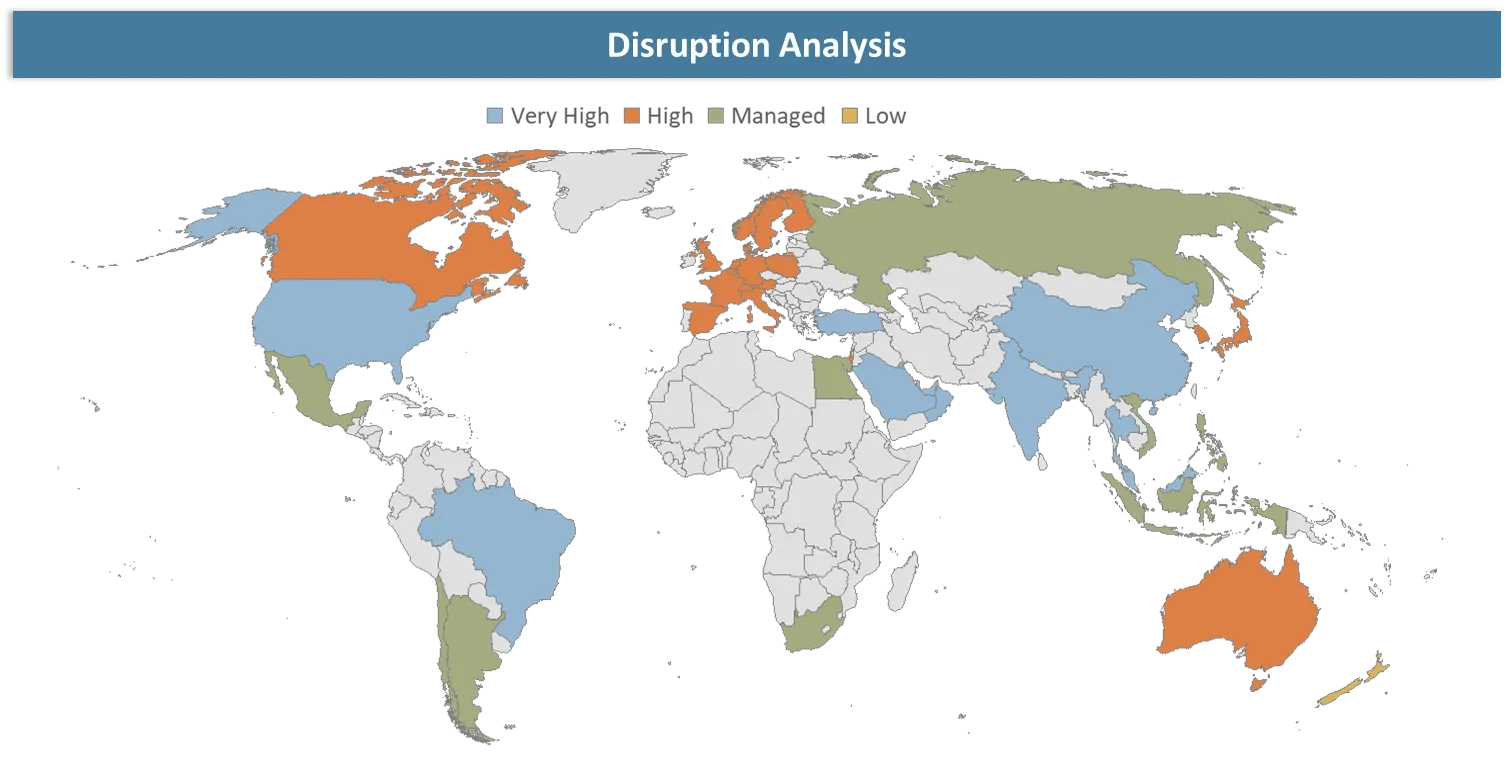
Shift Toward High-Efficiency, Oil-Free and Digitally Controlled Compression Technologies Reshaping the Hydrogen Compressor Market
The disruption in the hydrogen compressor market is primarily associated with the transition from conventional mechanical compression toward high-efficiency, oil-free, modular, and alternative compression techniques. The growing demand for the compression of hydrogen at various stages, be it during production, storage, transportation, or even refuelling, is leading to innovations in compressor designs that help save on energy, minimise leaks, cut down maintenance work, and prevent hydrogen contamination. Novel concepts like electrochemical compression, metal hydride compression, hydraulic compression, cryogenic compression, and advanced diaphragm compression are posing a challenge to the traditional concept of compressor design.
The above disruption is further justified by the introduction of modular and large-scale hydrogen compressors, which enhance the ease of installation, reliability, and efficiency of the process. According to Siemens Energy, the company’s Plug and Play reciprocating compressor package enables reduction of erection, installation, and commissioning time of a typical compressor plant by 50%. The compressor package is made up of 17 engineered modules, with each module weighing less than 25 tonnes, and has a modular design that reduces its footprint by 20%, highlighting the efforts by compressor companies to make compressors that are easier to install in order to build smaller hydrogen facilities.
Hydrogen Compressor Market BCG Matrix: Company Evaluation
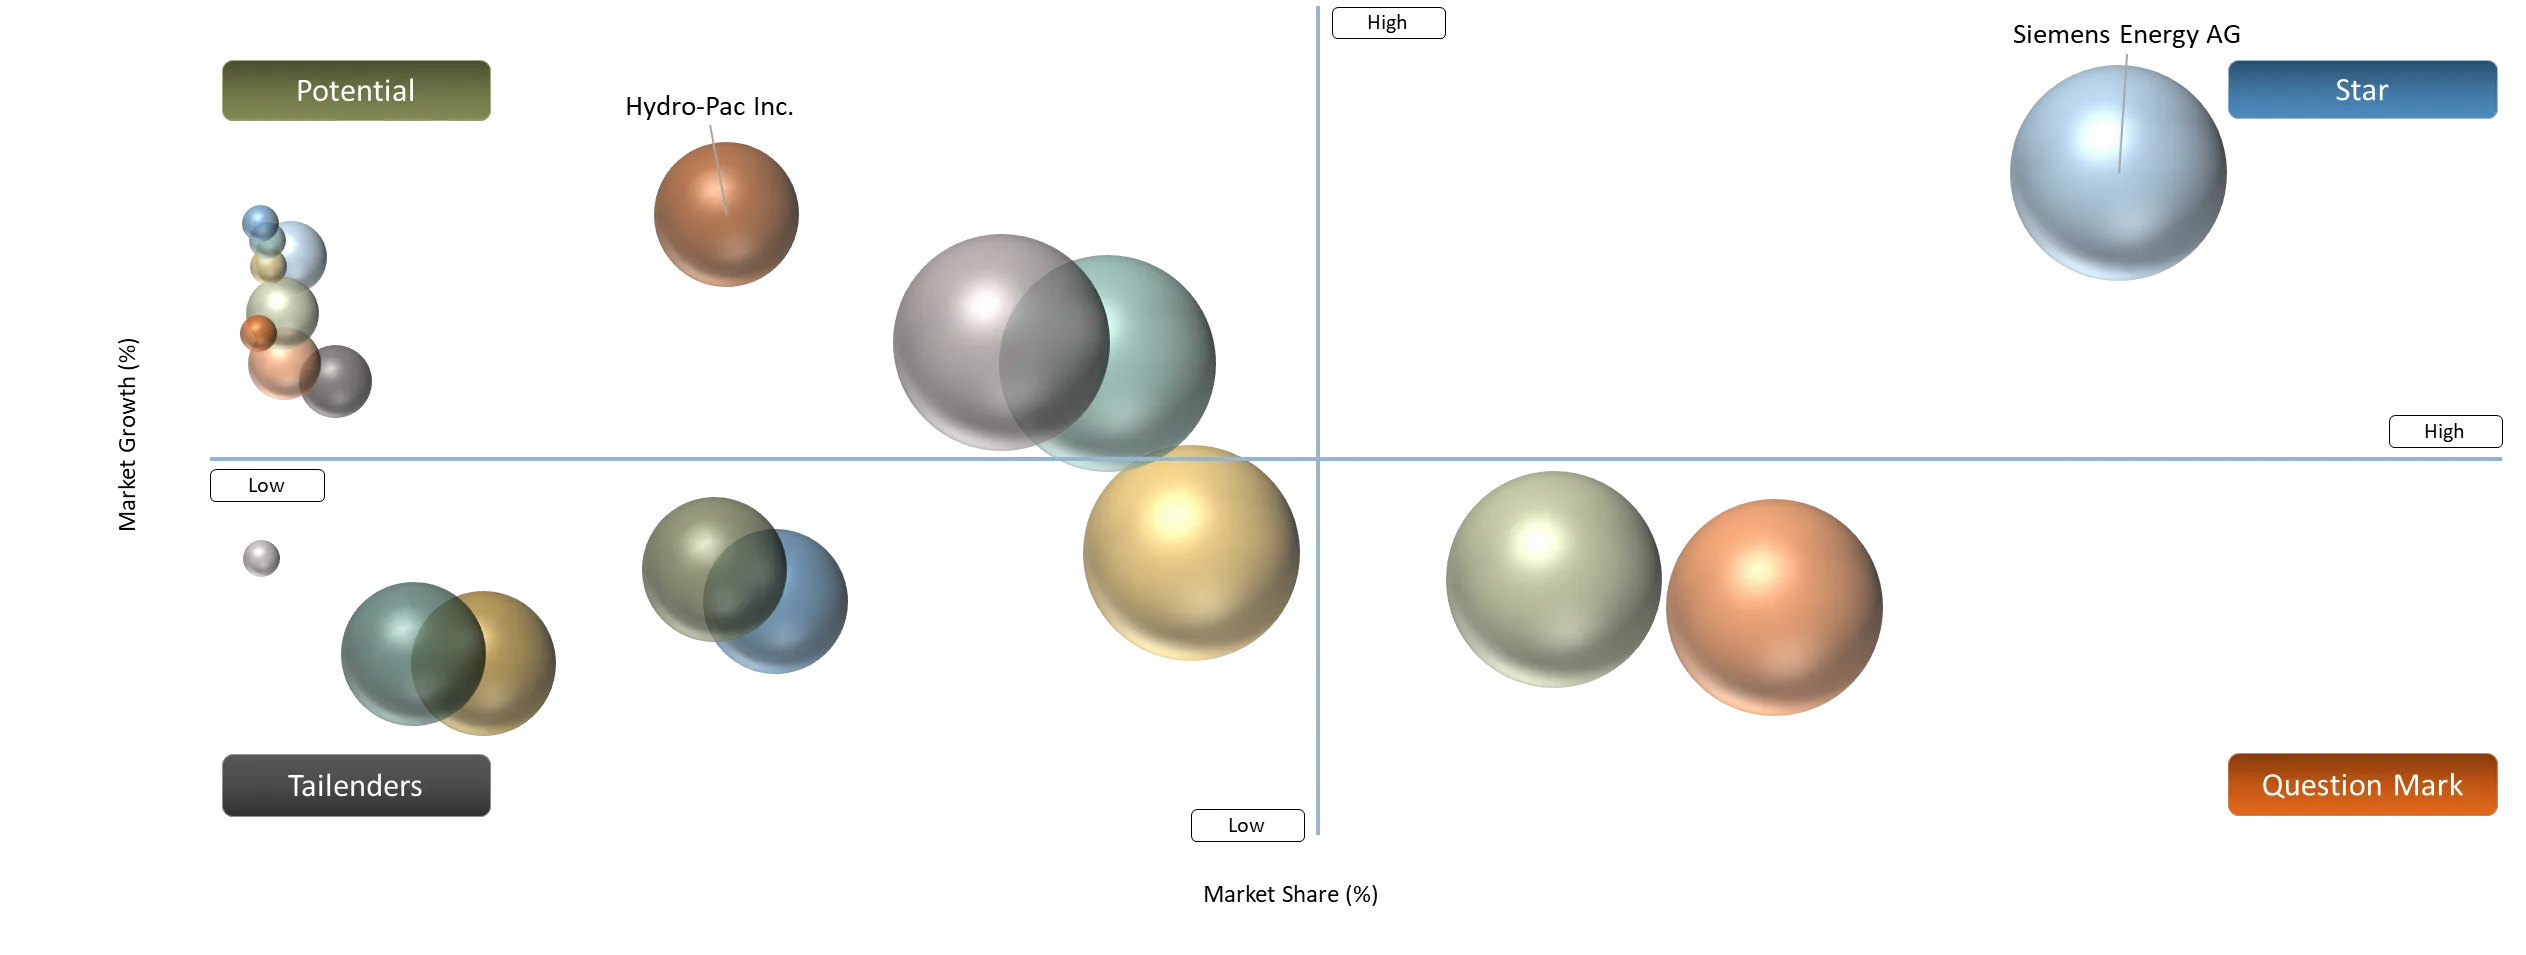
Stars include Siemens Energy AG, Burckhardt Compression AG, and PDC Machines Inc. because of their strong positioning in hydrogen compression and established portfolios covering high-pressure, refuelling, storage, pipeline, and industrial hydrogen applications. Question Marks include Atlas Copco AB, Ariel Corporation, and Sundyne, which have strong compressor engineering capabilities and opportunities to expand their hydrogen portfolios but face competition from companies with more specialised hydrogen-compression offerings.
The Potential category includes Hydro-Pac Inc., Haug Kompressoren AG, and NEUMAN & ESSER Group, which benefit from expertise in high-pressure, reciprocating, and diaphragm compression technologies applicable to hydrogen. Tailenders include Indian Compressors Ltd, whose compressor capabilities provide an entry point into hydrogen applications but whose dedicated hydrogen-compression presence remains comparatively limited among the selected top 10 companies.
Hydrogen Compressor Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
The growing deployment of hydrogen refuelling stations is increasing demand for high-pressure compressors. | 30% | Asia-Pacific & Europe, with increasing activity in China, Japan, South Korea and Europe | Hydrogen refuelling stations; passenger FCEVs; heavy-duty refuelling | Increases demand for high-pressure, fast-response and reliable compressors capable of supporting storage and dispensing requirements. |
Increasing deployment of hydrogen buses, trucks, and other heavy-duty vehicles is creating demand for higher-capacity compressors. | 28% | Asia-Pacific, Europe & North America | Heavy-duty trucks, buses, fleet depots and commercial-vehicle HRS | Creates demand for higher-flow compressors and parallel compression systems because heavy-duty vehicles consume more hydrogen per refuelling cycle. |
Hydrogen must be compressed to high pressures for compact storage and transportation. | 24% | Global, particularly hydrogen mobility, tube-trailer logistics and distributed hydrogen systems | High-pressure storage; tube trailers; pipeline delivery; hydrogen stations | Supports sustained demand for 350-700 bar and higher-pressure compression systems. |
Growing investment in liquid-hydrogen infrastructure is creating demand for specialised compressors. | 18% | North America, Europe and Asia-Pacific, particularly Japan and South Korea | Liquid hydrogen production, liquefaction, storage, transportation and cryo-compressed systems | Encourages development of specialised cryogenic and high-pressure compression technologies and expands the market beyond conventional gaseous-hydrogen compressors. |
The growing deployment of hydrogen refuelling stations is increasing demand for high-pressure compressors
The rapid expansion of hydrogen refueling stations (HRSs), is increasing demand for high-pressure compressors since hydrogen refuelling stations have a need for a system of compression in order to increase the pressure of hydrogen and make its storage and dispensing to vehicles more efficient. One factor that is especially important is the rise of fuel cell-powered heavy-duty vehicles, as buses and trucks need considerably larger amounts of hydrogen than regular passenger cars.
In February 2025, Kawasaki Heavy Industries commenced sales of a hydraulic booster-type hydogen compressor specifically designed for large-scale HRS serving fuel-cell heavy-duty vehicles. It is specifically meant for large-scale hydrogen refuelling stations (HRS) that provide fuel for fuel-cell heavy-duty vehicles. As stated by Kawasaki Heavy Industries, this new compressor offers a hydrogen supply capacity of 600 Nm³/h, which is double the supply capacity of 300 Nm³/h that is offered by the current compressor for normal HRSs. The system operates with an intake pressure of 20 MPa, and the pressure at which it supplies hydrogen can be up to 82 MPaG. This system is appropriate for use in large-scale HRSs where the hydrogen supply capacity is above 500 Nm³/h.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Compressors operating at high pressures experience wear in moving parts, seals, diaphragms, and other components, increasing maintenance and downtime requirements. | 28% | High-pressure compressor reliability and maintenance | Hydrogen refuelling stations, storage systems, industrial hydrogen facilities | Drives demand for oil-free, low-wear, longer-life compressor designs and predictive maintenance technologies. |
Compressing hydrogen to very high pressures requires significant energy, increasing the operating cost of hydrogen stations and storage systems. | 27% | Energy consumption and operating costs | 350-700 bar refuelling, high-pressure storage, tube trailers, pipeline compression | Encourages development of high-efficiency compressors, improved compression cycles, and alternative technologies with lower energy consumption. |
Hydrogen molecules are very small and can escape through seals and connections, making leakage prevention a major technical challenge for compressors. | 23% | Sealing, containment, safety and hydrogen purity | Hydrogen refueling stations, pipelines, storage, industrial processing | Increases the need for advanced sealing materials, leak detection, monitoring systems, and hydrogen-compatible components. |
Compression equipment depends on the development of hydrogen production, storage, pipelines, and refuelling infrastructure. | 22% | Hydrogen infrastructure development and equipment utilization | Hydrogen production plants, HRS, storage facilities, pipelines and distribution networks | Slower infrastructure deployment can delay compressor orders and reduce equipment utilization, encouraging suppliers to develop modular and scalable systems. |
Compressors operating at high pressures experience wear in moving parts, seals, diaphragms, and other components, increasing maintenance and downtime requirements
The hydrogen compressors operate under high-pressure conditions and repeated compression cycles, placing significant mechanical stress on the piston, diaphragm, valve, seal, bearings, and many other parts of the compressor. It is resulting in increased wear, the need for more frequent inspections, and unexpected outages of the equipment. The factors become crucial in case of hydrogen fueling stations, as compressor performance directly influences station reliability and continuous operation. In light of growing demand for larger and high-pressure systems, manufacturers develop compressor models with reduced mechanical wear.
In addition, the issue of maintaining the system becomes increasingly important since hydrogen compressors run at high pressures and experience cycling operations. In the February 2026, MDPI, the pressure levels that piston and diaphragm compressors can achieve can be equal to 1,000 bar and the flow rate is up to 2,000 Nm³/h, but because of the mechanical elements these machines have, the level of maintenance becomes significant. It is noted that mature mechanical systems consume about 3.7 to 6.0 kWh/kg of hydrogen in energy terms, and as per U.S. DOE analysis of 29 hydrogen refuelling stations, the compressors are the main reason behind maintenance problems and station outages.
Hydrogen Compressor Market Segment Analysis
The global hydrogen compressor market is segmented based on type, pressure limit, flow limit, power consumption, oil-free, running reference, application, end-user, and region.
Reciprocating Compressors Driving High-Pressure Hydrogen Compression Demand
The reciprocating compressor segment dominates the hydrogen compressor market, with the market share of 66.7% in 2025, due to its great compatibility for high-pressure hydrogen compression in various applications, including refueling, storage, transportation, and industries. Reciprocating compressors have the capability to deliver hydrogen at high pressures through regulated and consistent gas flow, and therefore they are highly compatible when multi-stage compression of hydrogen is required.
The adoption of reciprocating technology is also being reinforced by the expansion of large-scale hydrogen production and distribution projects. In July 2026, Burckhardt Compression was selected by Hydrogen Solutions AS (HYDS) to supply high-pressure hydrogen compression solutions for projects with planned production capacities of 20-40 MW. The company's reciprocating compressor systems will be capable of compressing hydrogen to up to 515 bar for high-pressure tube-trailer filling, supporting transportation and distribution from renewable hydrogen production sites. Burckhardt Compression states that its reciprocating technology is designed specifically for high-pressure hydrogen applications, addressing gas purity, operational reliability, efficiency, and long-term durability.
Hydrogen Compressor Market Geographical Penetration
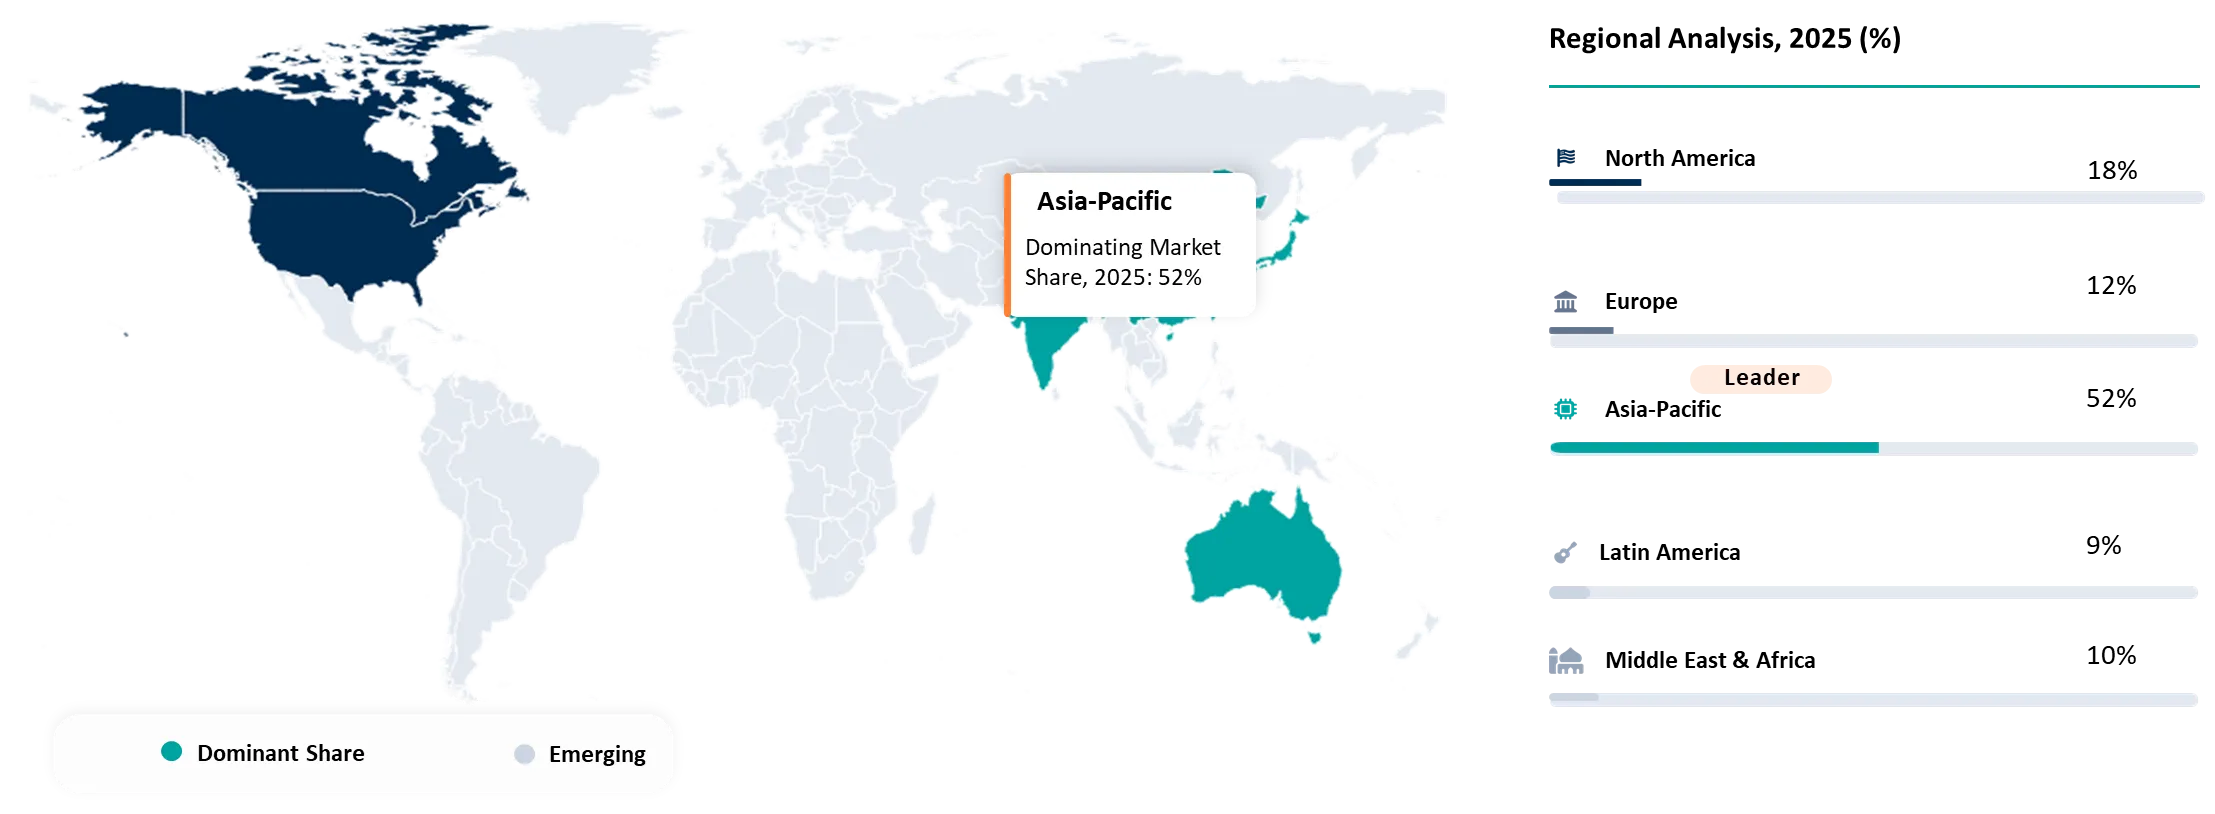
Accelerating Hydrogen Infrastructure Deployment and Large-Scale Compression Projects in Asia-Pacific
The Asia-Pacific region dominates the hydrogen compressor market, accounting for a 52.0% market share in 2025, supported by its large hydrogen production base, expanding refueling infrastructure, and strong investment in electrolyzers and hydrogen supply chains. China, Japan, South Korea, and Australia are key contributors to regional demand, with compressor requirements spanning hydrogen production, storage, transportation, industrial applications, and mobility.
The growing deployment of integrated hydrogen-refuelling infrastructure across Asia is increasing demand for high-pressure compression and on-site hydrogen-production technologies. In November 2025, LightBridge Co., Ltd., a South Korean-based hydrogen technology company, signed an MOU with Zhonglei, a China-based hydrogen equipment manufacturer, to jointly develop integrated hydrogen-refuelling systems across Asian markets. The partnership combines LightBridge’s high-pressure modular PEM electrolyser technology with Zhonglei’s hydrogen compression, storage, and dispensing equipment, integrating hydrogen production, compression, storage, and dispensing into a single system.
China Hydrogen Compressor Market Trends
China holds a dominant position in the Asia-Pacific hydrogen compressor market, supported by its large hydrogen production base, extensive electrolyzer manufacturing ecosystem, rapidly expanding hydrogen mobility infrastructure, and growing investment in large-scale hydrogen projects. The country's combination of hydrogen production, storage, transportation, and refueling applications creates strong demand for compressors across the hydrogen value chain.
China’s expansion of integrated hydrogen-refueling infrastructure is increasing demand for domestically manufactured high-pressure compression equipment. In May 2025, Yantai Dongde Hydrogen Energy Technology Co., Ltd. (Dongde Hydrogen Energy), a China-based hydrogen-equipment manufacturer, delivered its DZ45-750 diaphragm hydrogen compressor to an integrated oil–hydrogen station in Ordos, Inner Mongolia. The compressor has an inlet pressure of 5-20 MPaG, discharge pressure of 45 MPaG, and hydrogen flow rate of 750 Nm³/h, providing compression for the station’s hydrogen-refueling operations.
Japan Hydrogen Compressor Market Outlook
Japan is a major country in the Asia-Pacific hydrogen compressor market because of its established hydrogen technology ecosystem, strong government-backed hydrogen programs, and early development of hydrogen production, transportation, storage, and refueling infrastructure. Japanese companies are advancing both high-pressure gas compression and liquefied-hydrogen technologies, creating demand for specialized compressor systems across mobility, industrial applications, and large-scale hydrogen supply chains.
In FY2025, Japan’s New Energy and Industrial Technology Development Organization (NEDO), a Japanese government-funded research and development organization, allocated JPY 6.4 billion (USD 43 million) to its “Development of Technologies for Building a Competitive Hydrogen Supply Chain” project, running from FY2023 to FY2027. The program directly supports development of hydrogen compressors, liquefiers, pipelines, storage systems, pressure equipment, pre-coolers, and dispensers, with compressors specifically targeted for demand-area hydrogen supply chains and low-cost, advanced hydrogen-refueling stations.
Expanding Clean Hydrogen Infrastructure and High-Capacity Compression Development in North America
The North America is one of the major regions in the hydrogen compressor market accounted for an estimated 18.0% market share in 2025, supported by the region's expanding clean-hydrogen infrastructure, government-backed hydrogen hubs, and growing demand for high-pressure compression in transportation, industrial, storage, and energy applications. The United States is the principal contributor, with Canada also developing hydrogen production and export infrastructure.
Strategic acquisitions in the U.S. are strengthening the domestic hydrogen-compression equipment ecosystem by consolidating specialized compressor technologies with broader industrial capabilities. In March 2025, Honeywell International Inc., a U.S.-based industrial technology company, announced the acquisition of Sundyne, a U.S.-based engineered pumps and gas-compressor manufacturer, for USD 2.16 billion in an all-cash transaction.
U.S. Hydrogen Compressor Market Trends
The U.S. holds a dominant position in the North American hydrogen compressor market, supported by its large-scale clean hydrogen investments, established compressor manufacturing base, and expanding network of hydrogen production, storage, transportation, and refueling projects. The country's combination of federal funding, hydrogen hub development, and increasing demand for heavy-duty hydrogen mobility is creating opportunities for high-pressure and high-capacity compressor systems.
The U.S. hydrogen infrastructure market is seeing continued development of high-pressure, oil-free compression technologies to support electrolyzer and refueling applications. In July 2026, PDC Machines, LLC, a U.S.-based manufacturer of high-pressure diaphragm compressors and hydrogen-refueling systems, introduced the new PDC-7 diaphragm compressor model line for high-pressure, oil-free gas compression. The PDC-7 is available in single-stage, two-stage, and duplex configurations, with up to 75 HP (55 kW) drive power and 9,000 psig (620 bar) maximum discharge pressure.
Hydrogen Compressor Market Competitive Landscape
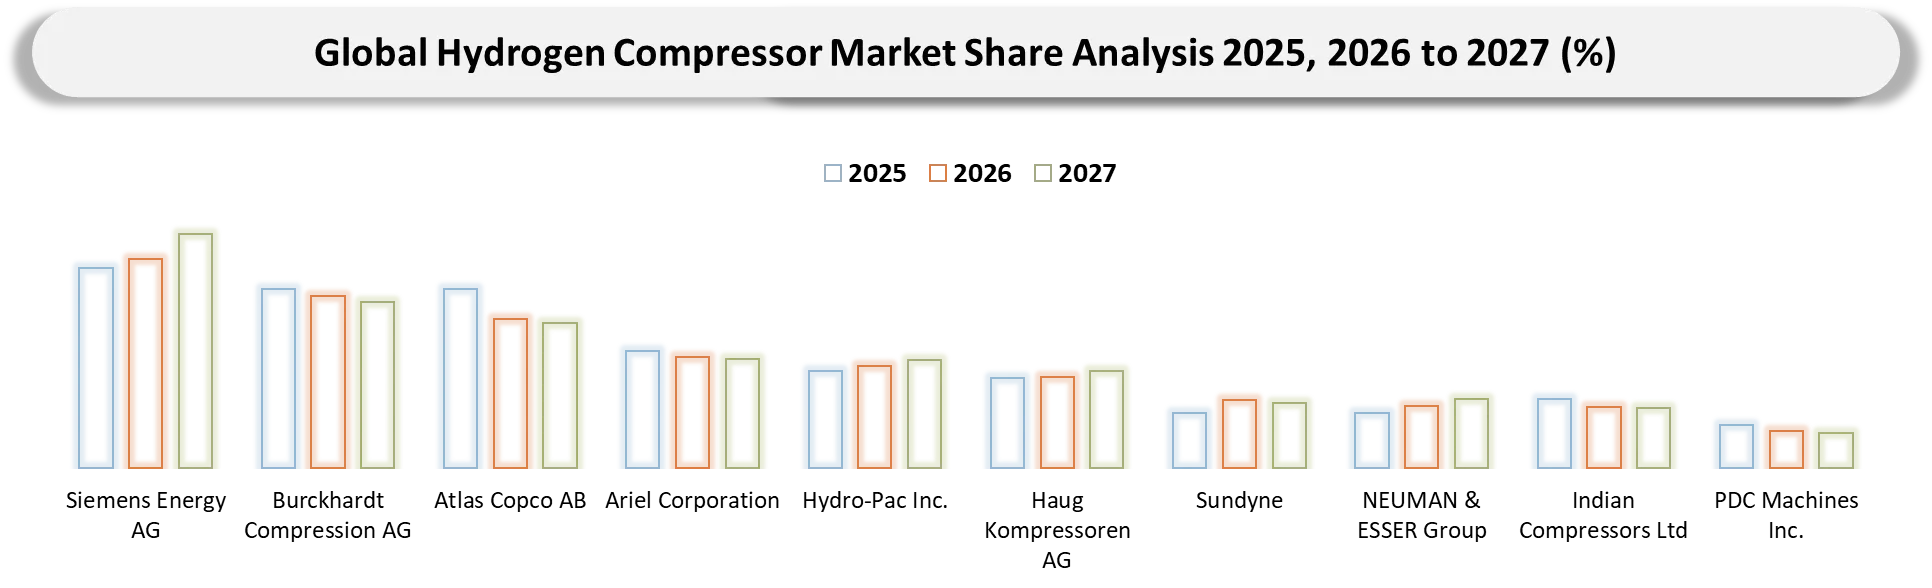
- The hydrogen compressor market is characterized by three major participant groups: large-scale compressor and energy-equipment manufacturers, specialized hydrogen compression companies, and high-pressure/diaphragm compressor specialists. Siemens Energy AG, Burckhardt Compression AG, Atlas Copco AB, Ariel Corporation, and NEUMAN & ESSER Group represent leading suppliers with broad reciprocating and high-pressure compression capabilities, while PDC Machines Inc., Hydro-Pac Inc., Haug Kompressoren AG, and Sundyne focus more strongly on diaphragm, hydraulic, centrifugal, and specialized hydrogen applications. Indian Compressors Ltd. adds a regional manufacturing presence serving India's growing industrial and hydrogen infrastructure. Competition is increasingly shaped by pressure capability, hydrogen purity, oil-free operation, compressor efficiency, modularization, reliability, and the ability to integrate compression with electrolyzers, storage, tube-trailer filling, and hydrogen refueling stations.
- Key players include Siemens Energy AG (Germany), Burckhardt Compression AG (Switzerland), Atlas Copco AB (Sweden), Ariel Corporation (United States), Hydro-Pac Inc. (United States), Haug Kompressoren AG (Switzerland), Sundyne (United States), NEUMAN & ESSER Group (Germany), Indian Compressors Ltd. (India), and PDC Machines Inc. (United States).
Key Developments
- October 2025: HOERBIGER, an Austria-based compression and engineering technology company, was selected by Kraftanlagen Energies & Services, a Germany-based energy and plant-engineering company, to supply three HCP 500 hydrogen compressor packages for the 105-MW Hamburg Green Hydrogen Hub in Germany.
- December 2025: KAJI Technology Corporation, a Japan-based compressor manufacturer, partnered with KOREA GASGEN Co., Ltd., a South Korean hydrogen-compression equipment company, to introduce high-pressure hydrogen compressors into the Korean market.
- March 2026: Sprintex Limited, an Australia-based advanced compressor technology company, entered into an exclusive distribution agreement with ChoisTechnics Corp., a South Korea-based engineering and technology company, to supply Sprintex’s fuel-cell compressors across South Korea.
- October 2025: DESCO Infratech Limited, an India-based engineering and clean-energy technology company, KPI Green Hydrogen and Ammonia Private Limited, an India-based green-hydrogen producer and KP Group subsidiary, and Naveriya Gas Pvt. Ltd., an India-based city-gas distribution company, signed an MoU to develop hydrogen–natural gas blending projects in India’s City Gas Distribution sector.
- December 2025: CATAGEN, a UK-based net-zero technology company, launched its ClimaHtech Compressor at Gastech 2025 in Milan, Italy.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organizations investing in hydrogen production, storage, transportation, and refueling infrastructure increasingly select compressor suppliers based on their ability to provide high-pressure, reliable, and hydrogen-compatible compression systems that can operate continuously under demanding conditions.
- The procurement decision-making process is increasingly influenced by the expansion of hydrogen refueling stations, electrolyzer projects, heavy-duty hydrogen mobility, tube-trailer filling, pipeline transportation, and large-scale hydrogen storage, requiring compressors that can accommodate different pressure, flow, and capacity requirements.
- Buyers consider factors such as maximum discharge pressure, flow capacity, compression efficiency, energy consumption, hydrogen purity, leakage control, sealing performance, material compatibility, maintenance requirements, and expected operating life when evaluating hydrogen compressor suppliers.
Why Choose DataM?
- Technological Innovations: Explores advancements in hydrogen compression technologies, including high-pressure reciprocating, diaphragm, centrifugal, screw, hydraulic, oil-free, and alternative compression systems, highlighting improvements in energy efficiency, hydrogen purity, reliability, modularity, and high-pressure performance across production, storage, transportation, and refueling applications.
- Product Performance & Market Positioning: Evaluates compressor suppliers based on discharge pressure, flow capacity, compression efficiency, power consumption, oil-free operation, leakage control, maintenance requirements, footprint, durability, and suitability for hydrogen-specific applications, showing how leading companies differentiate through high-pressure capability and system integration.
- Real-World Evidence: Highlights hydrogen compressor deployment in refueling stations, electrolyzer projects, tube-trailer filling, hydrogen storage, pipelines, industrial facilities, and heavy-duty mobility, demonstrating practical applications of high-pressure and high-flow compression technologies.
- Market Updates & Industry Changes: Tracks new hydrogen compressor launches, capacity expansions, demonstration projects, electrolyzer developments, hydrogen refueling infrastructure, and investments across Asia-Pacific, Europe, North America, and emerging hydrogen markets, providing insight into changes in compression requirements.
- Competitive Strategies: Analyzes how leading companies strengthen their market positions through hydrogen-specific compressor development, oil-free technologies, high-pressure systems, modular designs, strategic partnerships, project contracts, and integration with hydrogen production, storage, and refueling infrastructure.
- Pricing & Market Access: Examines compressor pricing based on pressure rating, flow capacity, compressor type, power requirements, materials, hydrogen purity specifications, automation, and system configuration, while assessing market access through equipment manufacturers, engineering contractors, hydrogen developers, refueling-station operators, and industrial gas companies.
- Market Entry & Expansion: Identifies growth opportunities created by hydrogen refueling stations, green hydrogen production, heavy-duty hydrogen mobility, hydrogen pipelines, high-pressure storage, and liquid-hydrogen infrastructure, while outlining strategies such as localized manufacturing, technology partnerships, modular systems, application-specific designs, and after-sales service expansion.
Target Audience 2026
- Hydrogen Compressor Manufacturers & Technology Providers
- Hydrogen Producers & Electrolyzer Developers
- Hydrogen Refueling Station Operators
- Oil & Gas and Industrial Gas Companies
- Hydrogen Mobility Companies & Fleet Operators
- Energy & Power Companies
- Engineering, Procurement & Construction (EPC) Companies



























































