

Heat Pump Market Size and Overview
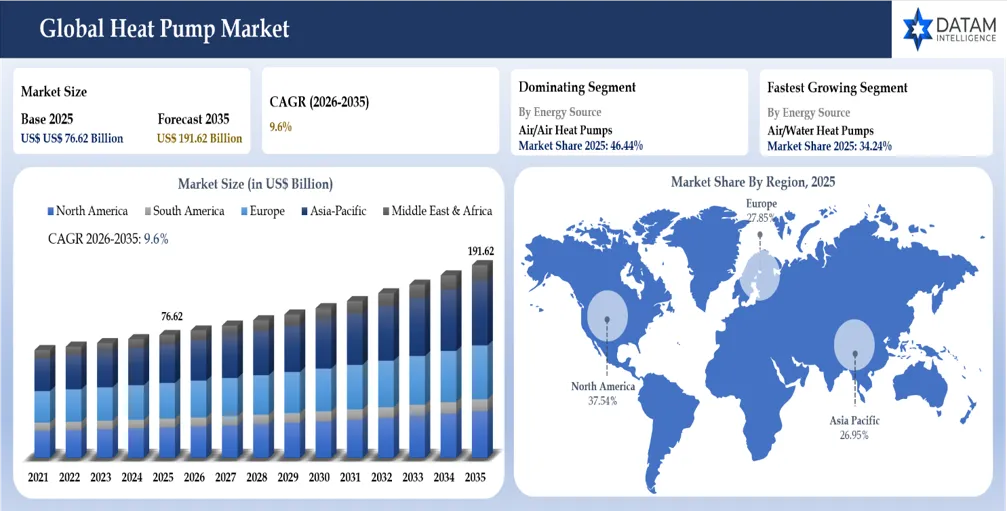
The global heat pump market reached US$ 76.62 billion in 2025 and is expected to reach US$ 191.62 billion by 2035, growing with a CAGR of 9.6% during the forecast period 2026-2035.
The heat pump market is quickly transitioning from heating systems that utilize oil and gas to heat-pump systems that work offline, with air-source and air-to-water systems witnessing strong uptake in both residential and industrial sectors. The demand in the market is being fueled by the electrification of heating systems, the aging of the existing heating system infrastructure, changing requirements for energy efficiency and the growing demand for integrated systems that provide space heating and cooling and hot-water supply. From a technical point of view, inverter compressors, low temperature applications, high temperature heating and retrofit options are becoming essential features of new products implemented in buildings of different types and climates.
The market is developing through the use of refrigerants such as R290, CO2 and ammonia, in addition to smart controls and connected energy management systems. The demand from the residential segment is growing through the retrofit market and the heat pump water heaters. Commercial and industrial segments have increased their demand through large capacity and high-temperature products which can replace process heating that uses fossil fuels. Systems that provide process heating from 80–160 degrees Celsius and above are being introduced into the market beyond traditional HVAC, while compatibility with technologies such as solar PV, thermal storage and demand-response systems is pushing prospects for advanced heat-pumps even further.
Heat Pump Market Key Takeaways
- Air/Air Heat Pumps led the heat pump market on a global scale in 2025 with market share of 46.44% due to their broad utilization in both residential and commercial buildings as heating and cooling solutions.
- Air/Water Heat Pumps are predicted to become one of the fastest growing segments with an estimated CAGR of 10.8% for the forecast period from 2026 to 2035 due to their growing utilization in building electrification, residential heating systems, domestic hot water and gas/oil-fired boilers.
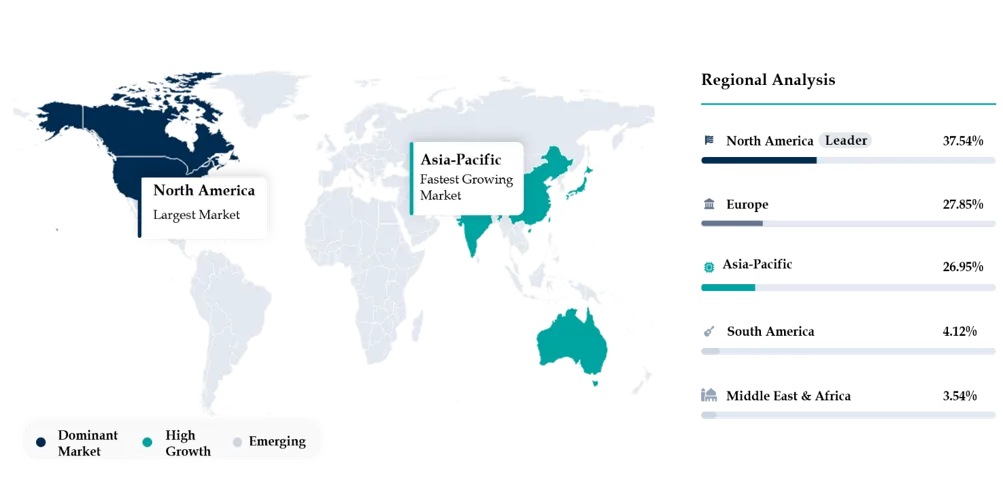
- North America has taken the lead in the heat pump market globally, occupying a market share of 37.54% in 2025 due to high residential HVAC installation, heat pump installations for replacing existing heating systems, heat pump installation in cold climates and rising electrification efforts.
- The increasing use of low GWP refrigerants like R290, CO₂ and ammonia is motivating manufacturers to innovate and come up with new designs for heat pumps that are more environmentally friendly and efficient in a wider range of temperatures.
- The increased demand for such equipment in residential buildings, commercial sites, industrial applications and for heat-pump water heating is providing room for the advancement of more sophisticated technologies.
Heat Pump Industry Trends and Strategic Insights
- Shift Toward Low-GWP Refrigerants: Manufacturers of heat pump systems are fast shifting their reliance on HFC refrigerants to CO2 and other refrigerants with lower global warming potential due to increasing refrigerant regulations and emissions.
- Expansion of High-Temperature Heat Pumps: The industrial use of high temperature heat pumps that provide process heat in addition to space heating is growing, leading to new applications for use in food processing, chemicals, district heating and other sectors.
- Growth of Cold-Climate Heat Pump Technology: The development of improved compressors, variable speed motors, refrigerant systems and defrost systems is enhancing the heating efficiency of cold climate heat pumps.
- Integration with Smart Energy Systems: Heat pumps have become integrated into smart controls, thermal storage, rooftop solar power, battery storage and demand response systems to allow the user to shift their use of electricity and reduce their heating expenses based on the energy grid situation.
- Rise of Electrification-Based Replacement Demand: The replacement of gas boilers, oil-based heating systems and traditional electric heating systems has become an important path for adoption especially where building efficiency standards, subsidies and carbon-reducing policies make it economical.
Heat Pump Market Scope
| Metrics | Details | |
| 2025 Market Size | US$ 76.62 Billion | |
| 2035 Projected Market Size | US$ 191.62 Billion | |
| CAGR (2026-2035) | 9.6% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Type | Ducted, Ductless | |
| By Energy Source | Air/Air, Air/Water, Ground/Geothermal Source, Hybrid, Others | |
| By Refrigerant | HFC, CO₂, Ammonia, Hydrocarbon, Others | |
| By Category | Reversible Air-Air W/Heating, H-Air/Water, Ground/Water, Sanitary Hot Water, Exhaust Air, Others | |
| By Capacity | Units < 20 kW, Units > 20 kW | |
| By Power | Electric, Gas Driven | |
| By End-User | Residential, Commercial, Industrial | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, Russia, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Turkiye, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Why does this report matter in 2026?
Heat pumps industry has become crucially dynamic as far as 2026 is concerned. Building heating will no longer rely on fossil fuel combustion but will shift to electric heat pumps. The usage of low-GWP refrigerants, advancements in cold climate efficiency, introduction of high-temperature industrial heat pumps and the upgrading of aging gas/oil furnaces will affect the competitive demand in a significant way. Thus, knowledge about technology trends in air-air, air-water, geothermal, hybrid, ducted and ductless technologies can be crucial in determining areas where market expansion is occurring.
The refrigerants regulations, electrification of buildings, cost of electricity, manufacturing localization and integration with smart grids will affect the market in 2026. Such trends will affect the economics and investments made into different end-use applications. This report gives an organized outlook of such trends so that manufacturers, investors, technology providers and HVAC companies can be able to identify high-growth products, refrigerants, retrofitting and regional expansion opportunities.
Heat Pump Market White Space & Investment Opportunities
- High-Temperature Industrial Heat Pumps: There are opportunities for investment in heat pumps that have the ability to provide 80-160 degrees centigrade plus industrial process heat, especially in food and beverages, chemical industry, pharmaceutical sector and district heating, as industries move away from fossil fuel boilers.
- Cold-Climate Heat Pump Systems: Research and product development in maintaining heating capacity even below freezing point has opened up many gaps in the market in the cold regions like Northern Europe, Canada, northern parts of the US, etc.
- Natural-Refrigerant Heat Pump Platforms: Investment in CO₂ and hydrocarbons-based platforms, such as propane heat pumps, will take advantage of the demand generated by HFC restrictions and the move towards GWP-friendly refrigerants.
- Heat Pump-Solar-Thermal Storage Integration: Integrated platforms that integrate heat pumps with solar PV, energy storage, advanced control and demand response systems are becoming a promising opportunity to reduce both cost and grid dependence.
- Heat Pump Retrofit Solutions for Existing Buildings: There is a great investment opportunity in compact heat pump retrofits, hybrid systems and low-temperature heating solutions for existing buildings where insulation, radiator suitability and power capacity would otherwise inhibit deployment.
Heat Pump Future Market Transformation
The heat pump market is forecasted to evolve from the existing traditional heating technologies to advanced and intelligent thermal energy systems which will comprise of heating, cooling, domestic hot water, thermal storage, renewable generation and grid interactive control. Future product innovations will focus on low-GWP natural refrigerants, high-temperature industrial heat pumps, cold climate operation, modularity and AI optimization, allowing heat pumps to be useful in more buildings and industrial applications. The future transformation will move the competition from equipment efficiency to systems integration and optimization, opening up business models for new types of businesses such as manufacturers, component suppliers, software providers and energy service providers.
Heat Pump Market Buyer Decision-Making Criteria
Buyers of heat pumps are basing their purchase decision not only on the initial cost but also on heating economics throughout the lifecycle of the heat pump, its suitability to the local weather conditions, ease of installation, need for particular refrigerants and projected lifespan. Buyers in residential and commercial sectors give priority to efficiency and capacity during seasons when there is heating demand, while industrial customers focus more on temperature of the process water or process air, continuous heating and system compatibility. Other factors that increasingly affect buying decisions include incentive programs, installation, control technology and maintenance programs.
Major Decision-Making Criteria
- Seasonal Energy Efficiency
- Heating and Cooling Capacity
- Performance at Low Outdoor Temperatures
- Upfront Equipment and Installation Cost
- Total Cost of Ownership
- Refrigerant Type and GWP
- Operating Temperature Range
- Compatibility with Existing HVAC Infrastructure
- Noise and Space Requirements
- System Reliability and Expected Lifespan
- Smart Controls and Remote Monitoring
- Integration with Solar PV and Thermal Storage
- Maintenance and After-Sales Support
- Availability of Government Incentives
- Installer and Service Network Availability
Heat Pump Market Economic & Investment Analysis
The economic dynamics within the heat pump market will now become increasingly dependent on the economics of power versus natural gas, oil and other heating fuels as well as the economics associated with the initial capital investment in heat-pump systems. The trend towards lower costs of technology, increased efficiency seasonally and incentives to build out electric-based buildings is helping the economics of investments in some markets while higher initial costs, electrical upgrades and building retrofits continue to be part of the equation. There is growing demand where heat pumps can help save on energy costs while performing multiple roles.
The investments are being made in efficient compressors, low GWP refrigerant, cold climate systems, high temperature industrial heat pumps and intelligent energy management systems. Investors are also making efforts in local manufacturing and sourcing of components to minimize the impact of shipping costs and supply chain disruptions. The greatest investment opportunity exists in those markets that have good electricity policy and old heating systems with high fossil fuel substitutability and an increasing demand for efficient heating ventilation and air conditioning (HVAC) systems, creating opportunities across equipment manufacturing, components, installation, controls and retrofit services.
Heat Pump Investment Trends in the Market
- Investment in Low-GWP Refrigerant Technologies: The companies are investing more of their money in CO2, Propane and other types of natural refrigerants heat-pump technology in order to meet regulations concerning refrigerants and also to build their future product lines.
- Expansion of High-Temperature Industrial Heat Pumps: There is an investment focus on industrial heat pumps with capabilities to provide high-temperature process heat that can be used for applications where traditionally natural gas, oil or steam is used for heating.
- Localization of Heat Pump Manufacturing: Businesses are building local manufacturing capability, developing compressor capacity, heat exchangers and component networks to limit risk exposure due to logistics and local market growth.
- Development of Smart and Grid-Interactive Heat Pumps: More resources are being allocated towards Internet of Things controls, variable speed compressors, software solutions for energy management, thermal energy storage and demand response functionality allowing for operation based on electricity price and grid situation.
- Investment in Retrofit-Oriented Product Development: Businesses are putting R&D efforts and investments into heat pump development that will have high temperature, compact designs and hybrid options that will be able to work with existing radiators and hot water systems.
Strategic Indicators for Heat Pump Market
High Regulation Impact
The heat pump market will have high regulation impact since product economics, refrigerant choice, installation considerations and consumer acceptance will be determined more and more by the F-gas regulations, regulations on the use of low GWP refrigerants, energy efficiency in buildings, prohibition of fossil fuels for heating and heat pump incentives schemes. Regulations steer the shift from high-GWP HFCs toward CO₂, propane and other low GWP refrigerants while codes on building and electrifications help inform the feasibility and attractiveness of shifting gas and oil heating systems for heat pumps. Changes in subsidies, refrigerant compliance timelines and minimum efficiency standards, then, can very quickly excite demand for technology, product portfolios, manufacturing priorities and investments by the private sector across the market.
High Investment Activity
Investment is flowing into the heat pump market in the form of investments into manufacturing capacity, localization of components, product innovations and digital technology. More capital is being invested in efficient compressors, heat exchangers, low global warming potential refrigerants, cold climate heat pumps, high temperature industrial heat pumps and intelligent controls. Companies are also increasing their regional manufacturing operations to cater to regional demands and limit their logistics exposure while investments are being made into heat pump retrofits, thermal storage, grid interactive controls and solar energy integration.
Supply Chain Disruption
The heat pump market is still vulnerable to market disturbances in the supply chain due to its dependence on major components such as compressors, heat exchangers, electronic controls, inverters, refrigerant circuits, copper pipes and special-purpose valves all obtained through global supply networks. The changes in the prices of copper and aluminium, availability of semiconductors, manufacturing capability of compressors, disturbances in shipping and changes in regulations of refrigerants may contribute to an increase in the costs of equipment and a lengthening of the waiting times. For this reason, manufacturers of heat pumps are switching to regional sources of components, diversification of suppliers, local production of components and material stocks organization while redesigning devices for alternative refrigerants and materials.
Pricing Volatility
Price in the Heat Pumps Industry is affected by the cost of copper, aluminum, compressors, electronics, refrigerants, the cost of electricity and costs associated with the installation process. In June 2026, the price of copper at the LME was estimated at US$13,572 per metric ton, illustrating a notable vulnerability to volatility in prices of the critical raw materials. Cost factors continue to be an important barrier to adoption, especially in residential retrofits due to the potential increase in the cost of the projects from electrical work, system distribution changes and labor costs. On the other hand, ratios of the cost of electricity and natural gas become increasingly crucial as it defines the cost benefits of heat pumps. In 2025, heat pumps were economically advantageous to gas boilers in 16 EU countries which constituted one-third of heating demands of residential buildings.
Procurement Pressure
The pressure of procurement in the heat pump market is growing due to the competition among manufacturers and installers for compressors, copper and aluminum heat exchangers, power electronics, inverters, electronic control boards, refrigerants and specific valves while dealing with irregular supplies and growing demand for electrified heating systems. The customers’ requirements towards suppliers become more sophisticated since they require the ability of the suppliers to provide certain ratings of the products and their compatibility with low-GWP refrigerants, ability to work in cold conditions, limitation of noise and compliance with certifications which reduces the number of suppliers of qualified components. Besides, procurement for large residential, commercial and industrial projects pays more attention to the availability and other aspects of the components’ life cycle.
New Technology Adoption
The adoption of the latest technology in the heat pump market is happening at a rapid pace using natural refrigerants, variable speed compressors, sophisticated inverter technology, upgraded vapor injection systems and low-temperature heat pump configurations to provide heating efficiency under tough operating conditions. The inclusion of AI-powered controls, Internet of Things connectivity, predictive maintenance systems, weather-optimized design and intelligent defrost systems is making systems more efficient and energy-efficient. The application of high-temperature heat pumps used to deliver heating beyond the conventional HVAC temperature ranges is being adopted by industries. The residential and commercial heat pump systems are now developed for integration with Solar PV, thermal storage, smart metering and demand response systems.
Regional Expansion Opportunity
Regional prospects for progress in the heat pump market are most promising in markets where there is a presence of fossil fuel heat replacement market growth potential, building electrification initiatives and adequate electricity costs alongside increasing HVAC demand. Europe presents an attractive opportunity for cold climate and residential replacement systems, whereas North America has high growth opportunities for energy efficient residential and commercial heat pumps along with cold climate models. Asia Pacific region, especially China, Japan, South Korea and emerging markets in Southeast Asia show lucrative prospects in the sectors of residential air source systems, commercial HVAC and industrial heat pumps due to developing urban infrastructure and industry expansion. At the same time, India as well as other emerging markets have prospects for air-to-water systems, heat pump water heaters and system efficiency improvement as energy costs and energy electrification in commercial buildings, hospitality and industry sector continue to grow.
Government Policy Support
Government policy support is an important driver of growth for the heat pump market through various policies that nations implement in order to promote heating electrification. In Europe energy efficiency regulations are being used to sopport the replacement of gas and oil-fired boilers with heat pumps, whereas in North America the government is introducing supportive programs for installation of energy efficient heat pumps and heat pumps designed for cold climates. In Asia, supportive measures are increasingly oriented at promotion of energy efficient construction processes, where heat pump water heaters, electrification of industries and the use of low GWP refrigerant technologies are gaining importance.
Pricing Intelligence
Pricing intelligence in the heat pump market will become more focused on cost positioning in terms of whole systems as opposed to equipment pricing, where residential air-source heat pump equipment has become very price-sensitive while the projects for air-to-water heat pumps, geothermal heat pumps and industrial heat pumps are valued at higher costs. In 2025–2026, equipment costs for residential air-source heat pumps range from about US$4,000 to US$15,000 while full system costs vary between US$8,000 to US$25,000 and more, depending on capacity, climate conditions, building adaptation measures and design of the system. Air-to-water and ground-source heat pump systems usually have higher initial costs due to the use of hydronic technology, the necessity for ground loops and the need for extra controls. This makes the pricing of such systems more sophisticated, as it is influenced by many factors, including their heating capacity, seasonal energy efficiency, cold climate performance, type of refrigerant used and inverter technology.
| HS Code | Reporter | Trade Flow | 2025 Trade Value | Interpretation |
| 841861 | China | Exports | US$1.1 Billion | China is a major global supply base for heat-pump equipment, reflecting its large-scale manufacturing capacity and strong export-oriented HVAC supply chain. |
| 841861 | Germany | Exports | US$576 Million | Germany represents a major European export hub, supported by established heating-equipment manufacturing and strong heat-pump technology capabilities. |
| 841861 | Germany | Imports | US$1.3 Billion | Germany's high import value reflects strong domestic demand for heat-pump equipment as heating systems transition toward electrification and energy efficiency. |
| 841861 | France | Imports | US$395 Million | France represents a significant European demand market, supported by residential heating electrification and replacement of conventional heating systems. |
Note: HS 841861 covers heat pumps other than air-conditioning machines of heading 8415. The trade data should therefore be presented as heat-pump trade intelligence, not as the total market size, because some heat-pump-related products can fall under other HS classifications.
AI Impact Analysis of Heat Pump Market
AI is making improvements in the performance of heat pumps through predictive control of the compressor, fan, valve and defrost cycles depending on the weather outdoors as well as occupancy and past heating requirements. The machine learning can be used to optimize the flow temperature and schedule in order to ensure efficiency regardless of weather changes. It can also help in diagnosing faults such as refrigerant pressure, compressor activity, airflow restriction and reduced performance of the system.
AI technology is affecting the design, installation and integration of heat pumps into the grid system. The manufacturing firms can make use of simulations provided by AI to maximize their efficiency in heat exchangers, circuitry of refrigerants, compressor, among others according to the climate. From the system's point of view, an AI-integrated heat pump can interact with solar PV, thermal storage systems, electricity tariff rates, demand response among other things to shift the heating load during cheap or low carbon times. It provides opportunities for intelligent heat pump systems that integrate hardware, predictive analytics, remote diagnostics and energy management software.
Disruption Analysis of Heat Pump Market
Disruption in the heat pump market can be observed in light of the swift change from the traditional approach of heating using gas and oil to the use of highly efficient electric heat pumps. The change towards the adoption of natural refrigerants like CO2 and propane, advances in cold climate heat pumps and the creation of high temperature heat pumps in industries are broadening the addressable market beyond traditional heating in residences. The use of heat pump systems that provide heating, cooling and hot water is lowering the need for thermal systems.
The second wave of disruption in the form of integration of heat pumps, artificial intelligence-based controls, distributed energy resources and thermal storage systems is being created. The smart heat pumps will be capable of adjusting themselves according to power costs, weather predictions, building loads, solar energy production and signals from the grid and thereby make heating appliances into active devices. This will provide many competitive advantages for the firms offering heat-pump hardware along with software, remote diagnosis, energy management system software and grid interaction capability, while posing tough challenges to conventional HVAC firms.
Heat Pump Market BCG Matrix: Company Evaluation
STAR
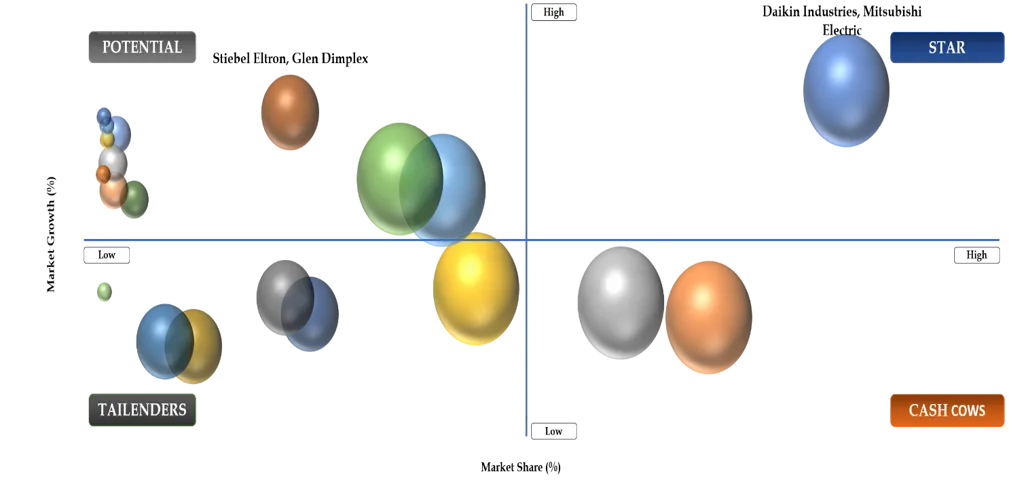
Companies that can be called Stars in the heat pump market are defined by their business prominence together with getting access to those technologies and applications that develop very rapidly in view of commercial aspects. Daikin Industries, Mitsubishi Electric, Bosch, NIBE and Danfoss have portfolios that contain various air source systems, cold-climate heat pumps, inverter technologies, low-GWP refrigerants as well as products for household and commercial purposes. Due to the networks of distribution and service companies built in the course of time, ongoing investments in electrification and the ability of these organizations to change products as required by certain regions, they have a good position in this area due to the growing number of companies that start to utilize heat pump technology.
POTENTIAL
Companies belonging to the Potential category have the capacity to acquire market share using specialized technologies or applications that have not been fully utilized. Stiebel Eltron, Glen Dimplex, Lennox International, Fujitsu General and Flamingo Heat Pumps have the ability to consolidate their positions with cold-climate systems, heat-pump water heaters, solutions for renovations, high-efficiency ductless systems and entry into new residential and commercial segments. Their growth opportunities will depend on the development of distribution channels, installation and service and product compliance with low GWP refrigerants and electrification needs.
Heat Pump Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Building Electrification and Replacement of Gas/Oil Heating | 24% | Europe, North America, Japan | Residential Space Heating | Accelerates replacement demand for air-source and air-to-water heat pumps, strengthening opportunities for retrofit-focused manufacturers. |
Government Incentives and Decarbonization Policies | 21% | Europe, North America, China | Residential & Commercial Heating | Improves purchase economics through subsidies, rebates, efficiency standards and fossil-fuel heating phase-out policies. |
Rising Demand for Energy-Efficient HVAC Systems | 19% | Asia Pacific, Europe, North America | Residential, Commercial & Institutional Buildings | Drives adoption of high-efficiency inverter heat pumps that provide heating and cooling from a single system. |
Expansion of Low-GWP Refrigerant Technologies | 16% | Europe, Japan, North America | Residential, Commercial & Industrial | Accelerates adoption of R290, CO₂, ammonia and other low-GWP systems while creating differentiation through refrigerant technology. |
Driver: Building Electrification and Replacement of Fossil-Fuel Heating Systems
The shift from gas and oil heated systems to electric heat pump solutions serves as an important trigger for the development of the heat pump market, both in the residential and commercial segments. This is due to the fact that heat pumps can offer not only space heating, but also space cooling and availability of domestic hot water utilizing one system, thus boosting energy efficiency and minimizing reliance on fossil fuel heating. Adoption is driven by building electrification initiatives, various incentives for advanced heating systems, tougher energy standards and replacement of worn heating equipment. Very strong demand for air-source heat pumps and air-to-water heat pumps is observed along with advancements in technology that allow cold and high-temperature heat pumps to be used in areas where traditional pumps were unable to operate before.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Upfront Equipment and Installation Costs | 24% | Purchase Economics | Residential Retrofits | Limits adoption among price-sensitive buyers and increases dependence on subsidies, financing and lower-cost installation models. |
Retrofit and Infrastructure Compatibility Constraints | 21% | Building Integration | Existing Residential & Commercial Buildings | Older radiators, inadequate insulation, limited electrical capacity and hydronic-system requirements can increase project complexity and installation costs. |
Shortage of Skilled Heat-Pump Installers | 17% | Installation & Service Capacity | Residential & Commercial Installations | Limited availability of trained technicians can delay installations, increase labor costs and reduce system performance through improper sizing or commissioning. |
Cold-Climate Performance and Efficiency Challenges | 15% | System Performance | Cold-Region Space Heating | Reduced heating output and increased defrost requirements at very low temperatures raise technology and operating-cost challenges, driving demand for advanced cold-climate systems. |
Restraint: High Upfront Installation Cost and Retrofit Complexity
High initial costs for both the equipment and installation continue to be an important limitation, more particularly when installing heat pumps in already built residential and commercial premises. The installation of a heat pump may involve changes in the electrical capacity, installation of new radiators or hydronics, enhanced insulation and many other things besides the installation cost of the equipment. Ground-source systems incur further costs related to drilling and installation of ground loops, while air-source systems may involve substantial integration into existing heating systems. Such factors can increase payback times and make it harder to convince budget-conscious consumers when electricity is still quite expensive compared with natural gas.
Heat Pump Market Segment Analysis
The global heat pump market is segmented based on the type, energy source, refregirant, category, capacity, power, end-user and region.
By Energy Source
Air/Air Heat Pumps Emerged as the Leading Type Segment in 2025
Air/Air Heat Pumps represented an estimated 46.44% of the global heat pump market in 2025, making them the leading segment. Their dominant share is mainly driven by the fact that they can provide heating and cooling at the same time. They are widely used in both ducted and ductless solutions and installation of the units is quite simple compared to ground-source options. Demand is especially high among residential and light commercial applications where heating and cooling demands coexist, while inverter technology and low-temperature capability continue to encourage adoption.
By Energy Source
Air/Water Heat Pumps Are Projected to Expand at a 10.8% CAGR During 2026–2035
Air/Water Heat Pumps are growing in popularity as more building owners swap their traditional boilers for electric-based heating systems that provide heating and hot water supply. Their growth has been aided by electrification of buildings, heating systems replacement and increasing demand for efficient technologies compatible with radiators, underfloor heating, thermal storage and renewable energy production. Improvements in their temperature performance are also paving the way for an air-water system use in retrofit projects in cold areas.
Heat Pump Market Geographical Penetration
U.S. Heat Pump Market Landscape
The U.S. heat pump market is characterized by the quick adoption of air-source and cold-climate heat pumps instead of gas- and electric resistance heating equipment in residential and light commercial segments. The strongest demand is seen in areas where both heating and cooling are needed. Moreover, the installation of heat pumps is rising in colder states due to better low-temperature capabilities, variable-speed compressors and defrost capabilities. Another trend is the switch from ducted systems for retrofit projects to ductless units, high-efficiency ducted units for new builds and heat pump water heaters due to the need for energy savings and electrification. The federal and state efficiency programs, utility rebates, building electrification projects and tighter restrictions on refrigerant are affecting the choice of product, while manufacturers are localizing their production and logistics capabilities to satisfy U.S. demand. The major competitive activities are among Daikin, Mitsubishi Electric, Carrier, Trane Technologies, Lennox, Bosch and Rheem, with the basis for differentiation moving toward cold climate operation, energy efficiency, low-GWP refrigerants, intelligent control and installer availability.
Japan Heat Pump Market Outlook
The Japan heat pump market features a mature installed base along with high consumer awareness about the use of air-source heat pumps, heat pump water heaters and very energy-efficient room air-conditioning. The presence of CO2-based heat pump water heaters (EcoCute systems) constitutes a unique market niche, while consumers' demands are becoming more oriented towards highly efficient inverter systems, compact heat pumps and combination heating/cooling/hot water devices. Replacing outdated equipment with new heat pumps due to Japan’s old housing stock, space restrictions in urban areas, strict energy efficiency standards and its decarbonization policies, can be considered another important driver of growth in the market. Leading Japanese producers like Daikin, Mitsubishi Electric, Panasonic and Fujitsu General have a competitive advantage because of well-developed technological competencies and wide distribution networks, while the areas of potential growth include GWP refrigerants, heat pump water heaters, energy management systems and renewable electricity generation.
China Heat Pump Market Trends
Drivers of the China heat pump market include air-source heat pumps, heat-pump water heaters, commercial HVAC electrification and industrial heat pump technology, fueled by China’s extensive manufacturing capabilities and its initiatives towards energy efficiency and decarbonization. Space heating applications dominate demand in northern China, while other regions in the country favor heat pumps for cooling and hot water supply purposes, generating multiple product mixes in the different provinces of China. Development of low-GWP refrigerants, high-efficiency inverters, low-temperature heating heat pumps and heating/cooling systems continue to be favored by heat pump manufacturers, whereas high-temperature heat pumps are adopted by industries for lowering coal and gas-fired process heating processes. Strong supply of compressors, heat exchangers, inverters and HVAC components domestically in China is helping generate competitive prices in equipment and exportable production, with leading players Midea, Gree, Haier, Hisense and AUX making headway in residential, commercial and industrial segments.
Heat Pump Market Competitive Landscape
- Portfolio Expansion Across Heat Sources: The top players in the market are diversifying their heat pumps according to different climatic conditions, structures and heating demands in the form of air-to-air, air-to-water, ground source, hybrid and heat pump water heater products. Such expansion will allow companies to cover both new builds and retrofits for various markets.
- Shift Toward Low-GWP Refrigerants: Refrigerant platforms that utilize R290, CO₂, ammonia and other low GWP refrigerants have been developed by manufacturers to respond to changes in environmental regulations and create product differentiation. Selecting the right refrigerant for a heat pump system has become a very important competitive issue.
- Cold-Climate and High-Temperature Differentiation: The companies are differentiating themselves through improvements in performance of cold weather heating and high temperature heat output, allowing the heat pumps to work efficiently in below-zero environments as well as providing elevated temperature heat to industrial applications. Improved compressors, vapor injection systems and refrigerant circuits are helping in this process.
- Smart and Grid-Interactive Systems: Variable speed compressors, Internet of Things, artificial intelligence, remote monitoring, forecasting of weather conditions and demand response are now included in heat pump systems in order to make them more efficient and flexible. Inclusion of smart grid integration, photovoltaic panels, battery and thermal storage is taking the competition to the connected energy management systems.
- Manufacturing and Service-Network Strength: Competitive advantage is becoming increasingly dependent upon localized manufacturing facilities, reliable sourcing of components, installer networks, technical skills and spare parts. Those companies that have effective regional manufacturing and after-sales services systems can better cater to large retrofitting operations for residences, as well as commercial and industrial setups.
Public Company Q1-Q2 2026 Performance Comparison
The table below compares five publicly listed companies with direct exposure to the heat pump market. Financial metrics are company-wide or HVAC-related segment-level because standalone heat-pump revenue is generally not separately disclosed. Performance drivers therefore distinguish overall corporate performance from direct heat-pump exposure.
| Company | Q1–Q2 2026 Performance | Heat Pump Exposure | Key Performance Driver |
| Daikin Industries, Ltd. | US$8.99 Billion revenue in Q1 FY2026, up 17.5% YoY; Air-Conditioning & Refrigeration Equipment revenue was approximately US$8.35 Billion, up 17.0% | Direct exposure across air-to-air, air-to-water, residential, commercial and heat-pump water-heating systems | Strong HVAC demand, expanding residential heat-pump hot-water sales in Europe and growth in Asia supported performance. |
| Lennox International Inc. | US$2.68 Billion revenue in H1 2026, up 4.2% YoY; Q2 revenue was US$1.55 Billion | Direct residential and commercial heat-pump exposure through Home Comfort Solutions and Building Climate Solutions | Strong Building Climate Solutions growth and acquisitions offset continued softness in the residential market. (Lennox) |
| NIBE Industrier AB | US$0.97 Billion revenue in H1 2026, up 7.6% YoY; operating profit approximately US$110 Million | Strong direct exposure to air-source and ground-source heat pumps through Climate Solutions | Recovery in heat-pump demand and improved profitability supported first-half performance; operating margin reached 11.4%. (Nasdaq News Viewer) |
| Mitsubishi Electric Corporation | US$9.4 Billion revenue in Q1 FY2027, up approximately 14% YoY | Direct exposure through residential, commercial, ductless and air-to-water heat-pump systems | Growth in the Life segment, particularly air-conditioning systems and home products, supported by stronger business volume and energy-efficient HVAC demand. (MarketScreener) |
| Daikin Industries, Ltd. | US$8.99 Billion revenue in Q1 FY2026, up 17.5% YoY; Air-Conditioning & Refrigeration Equipment revenue was approximately US$8.35 Billion, up 17.0% | Direct exposure across air-to-air, air-to-water, residential, commercial and heat-pump water-heating systems | Strong HVAC demand, expanding residential heat-pump hot-water sales in Europe and growth in Asia supported performance. |
Note: Company-level revenue should not be interpreted as heat-pump revenue unless separately disclosed. Financial periods differ because companies follow different fiscal calendars.
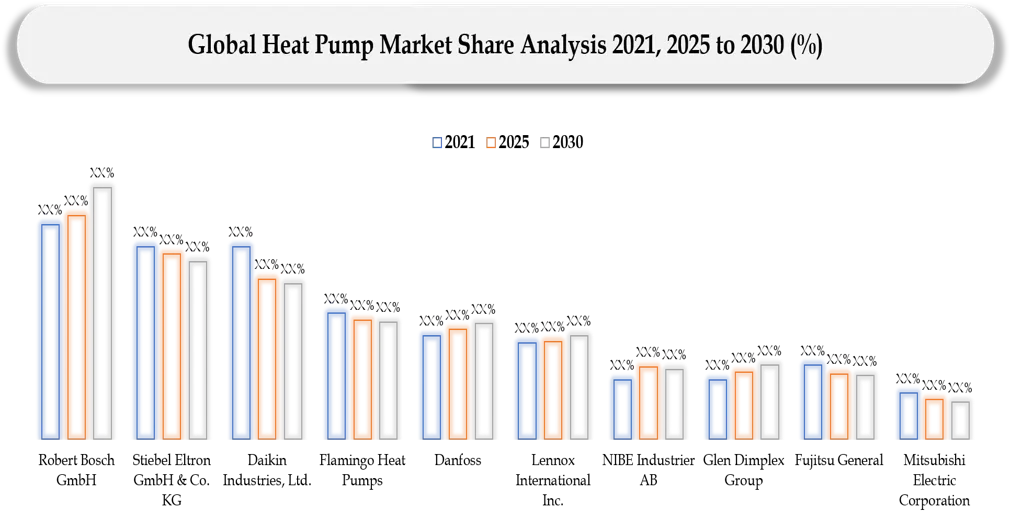
Key Companies of Heat Pump Market
- Robert Bosch GmbH
- Stiebel Eltron GmbH & Co. KG
- Daikin Industries, Ltd.
- Flamingo Heat Pumps
- Danfoss
- Lennox International Inc.
- NIBE Industrier AB
- Glen Dimplex Group
- Fujitsu General
- Mitsubishi Electric Corporation
Company Profiles of Heat Pump Market
Robert Bosch GmbH
Robert Bosch is one of the top HVAC and heating equipment providers in the world and now having a strong presence in the heat pump market with air-to-water heat pumps, hybrid heating systems and energy-efficient residential offerings. Robert Bosch’s product portfolio increasingly includes systems that offer replacement of traditional gas-fired heating solutions with electrical heating pump solutions.
The competitive objectives of the company are to enhance the adoption of air-to-water heat pumps, to increase its performance in cold climates and at high temperatures, to develop low GWP refrigerants and others.
Daikin Industries, Ltd.
Daikin is among the top HVAC producers globally, having a wide variety of heat pump products including air-to-air, air-to-water, commercial and residential. The company enjoys an advantageous position in the market, thanks to its patented compressors and refrigerants, inverter-based technology and comprehensive distribution and servicing networks in heat pump markets.
The competitive focus of the firm includes development of high-efficiency heat pump systems, promotion of low GWP refrigerants, improvement of performance in cold environments, intelligent controls and localized manufacturing and servicing.
Stiebel Eltron GmbH & Co. KG
Stiebel Eltron’s expertise lies in the domain of heating, ventilation and hot-water systems, while the heat pump constitutes an important element of their product line. The firm produces air source and geothermal heat pumps, heat-pump water heaters and combined solutions that facilitate electrification and building renovation, especially in Europe.
The areas of priority for competition include increasing the presence of heat pumps in retrofit projects, raising seasonal performance, implementing solutions with natural refrigerants, enhancing high temperature solutions and linking heat pumps to PV systems and storage.
NIBE Industrier AB
NIBE is a heating equipment company that has a very good market share for air-source and ground-source heat pumps in Nordics and Europe. NIBE’s product line is very much suited to cold climate heating needs and transitioning from traditional boilers to renewable electricity-based heating systems in residential and commercial spaces.
Priorities in terms of competition can be said to include improving cold climate performance, developing more efficient air and ground-source equipment, boosting retrofitting sales and smart energy control integration with renewable electricity and heat pumps.
Mitsubishi Electric Corporation
Heat pump market Position is achieved by Mitsubishi Electric via inverter-driven air source systems, ductless heating and cooling and cold climate heat pump solutions. These products cover both residential and commercial markets. Competitive advantages are achieved through variable speed technology, efficient heating at low temperatures and control technologies.
The competitive challenges that the company needs to overcome are low temperature efficiency improvements, ductless and air to water heat pump application expansion, refrigerant adoption for low GWP refrigerants and development of connected energy management systems.
Heat Pump Market Major Pain Points
- High Upfront Installation Cost: The initial cost of heat pumps over its replacement is more than that of the conventional heating systems, especially air sourcing and ground-source units, which may require remodeling of electrical systems, hydronic systems, installing ground loops and new emitters.
- Retrofit Compatibility Constraints: The existing building structure can act as an obstacle to implementation due to old radiators, inadequate wiring, poor insulation and requirement of high temperature in heating process which cannot be achieved by using regular heat pump without further modifications.
- Cold-Weather Efficiency Challenges: The efficiency of operation and seasonal efficiency may drop if ambient temperatures become very low, whereas the need to defrost will result in higher electricity use and strain the compressor and the refrigerant circuit.
- Limited Skilled Installation Capacity: The lack of adequately qualified technicians who have knowledge of heat pump sizing, refrigerant management, hydronic coupling, commissioning and digital controls can result in delays during installation and poor performance of the equipment.
- Low-GWP Refrigerant Conversion Challenges: Transition from HFC refrigerants to other lower GWP such as propane and carbon dioxide entails the need for redesigning of equipment, safety regulations and servicing capabilities, among others.
Heat Pump Market Recent Developments
- Robert Bosch GmbH - September 2026: The new generation of heat-pump systems Compress 3800i AW, Compress 6800i AW and Compress 8800i AW was presented by Bosch Home Comfort. It features the 4–13 kW Compress 3800i AW and the high temperature model Compress 8800i AW intended for new buildings and refurbishments.
- Flamingo Heat Pumps - September 2026: Flamingo launched a range of heat pumps based on R290, R32 and CO₂ technology which would be suitable for use with existing floor heating, radiator and fan coil systems.
- Danfoss - September 2026: Danfoss launched a variable speed vapor injection compressor for R290 applications aimed at increasing heating capacity and seasonal performance under low ambient temperatures. It also launched components for hydrocarbon heat pump applications in up to 130°C.
- Glen Dimplex Group - August 2026: The company Glen Dimplex made an investment of around €1.6 million for the installation of a central R290 Propane refrigerant supply plant at its Kulmbach manufacturing facility in Germany.
- Mitsubishi Electric Corporation - July 2026: Mitsubishi Electric released its new air-to-water heat-pump line MEHP-iB-G09 R290 featuring models ranging from 12 to 38 kW. They run on refrigerant R290 with the GWP value of 0.02, can be cascaded in up to four units and feature ease of installation.
Analyst View / Opinion on Heat Pump Market
- Electrification Is Reshaping Heating Demand: The trend now is towards electrification of both heating and hot-water systems and hence chances for air-source, air-to-water and hybrid heat pumps are becoming more evident due to widespread replacement of gas and oil equipment.
- Cold-Climate Performance Will Define Competitive Leadership: Manufacturers who can keep their heating capacity and season efficiency during freezing weather will get the larger market share, which makes compressor design, refrigeration circuit design, vapor injection and defrosting system design competitive advantages.
- Low-GWP Refrigerants Are Becoming a Product-Portfolio Requirement: In the process of moving from the current refrigerants to new products that include propane, CO₂ and others with low global warming potential, companies must develop solutions that will take into consideration their environmental requirements, energy efficiency, safety and operating temperatures.
- Retrofit Economics Will Determine Mass-Market Adoption: Future success of the market will depend not only on how efficient the heat pumps become but also on their ability to be retrofitted into older buildings with radiators, electrical system inadequacies and insufficient insulation.
- Heat Pumps Are Evolving Into Energy-Management Assets: The upcoming competitive edge will probably move on from the stage of mere heating devices into the realm of connected devices where heat pumps will work alongside solar PV panels, thermal storage, smart meters, electricity pricing schemes and demand response initiatives.
Target Audience of Heat Pump Market
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| HVAC & Heat Pump Manufacturers | Heat Pump OEMs, HVAC Manufacturers, System Integrators | Identify high-growth heat-pump types, energy sources, capacities, refrigerants and end-user segments for product portfolio expansion. |
| Building & Construction | Real Estate Developers, Building Contractors, EPC Companies | Assess heat-pump adoption opportunities in new construction, building electrification and energy-efficient retrofit projects. |
| Energy & Utilities | Utilities, Energy Companies, District Heating Providers | Evaluate the impact of heating electrification and heat-pump deployment on electricity demand, grid flexibility and distributed energy systems. |
| Industrial Manufacturing | Industrial Heating Companies, Process Equipment Manufacturers | Identify opportunities for high-temperature heat pumps replacing gas- and oil-fired process heating across industrial applications. |
| Refrigeration & Components | Compressor, Heat Exchanger, Valve, Inverter & Refrigerant Suppliers | Understand technology shifts toward variable-speed systems and low-GWP refrigerants such as R290, CO₂ and ammonia. |
| Technology & Digital Solutions | Smart HVAC, IoT, AI & Energy-Management Providers | Identify opportunities for connected heat pumps, predictive controls, remote diagnostics, demand response and AI-based optimization. |
| Financial Services & Investors | Private Equity Firms, Venture Capital Funds, Infrastructure Investors | Assess market growth, technology opportunities, competitive positioning, investment priorities and regional expansion potential. |
| Government & Regulatory Bodies | Energy Ministries, Environmental Agencies, Policy Makers | Evaluate the market impact of heat-pump incentives, building-efficiency standards, refrigerant regulations and heating-electrification policies. |
| Installation & Service Providers | HVAC Installers, Maintenance Companies, Service Networks | Identify demand hotspots, retrofit opportunities, installer requirements and emerging service opportunities across residential and commercial markets. |
| Corporate Strategy & Consulting | Strategy Teams, Management Consultants, Market Intelligence Firms | Benchmark leading companies, evaluate competitive threats, identify white-space opportunities and support market-entry and expansion strategies. |
Why Choose DATAM?
- Data-Driven insights: Dive into detailed analyses with granular insights such as pricing, market shares and value chain evaluations, enriched by interviews with industry leaders and disruptors.
- Post-Purchase Support and Expert Analyst Consultations: As a valued client, gain direct access to our expert analysts for personalized advice and strategic guidance, tailored to your specific needs and challenges.
- White Papers and Case Studies: Benefit quarterly from our in-depth studies related to your purchased titles, tailored to refine your operational and marketing strategies for maximum impact.
- Annual Updates on Purchased Reports: As an existing customer, enjoy the privilege of annual updates to your reports, ensuring you stay abreast of the latest market insights and technological advancements. Terms and conditions apply.
- Specialized Focus on Emerging Markets: DataM differentiates itself by delivering in-depth, specialized insights specifically for emerging markets, rather than offering generalized geographic overviews. The approach equips our clients with a nuanced understanding and actionable intelligence that are essential for navigating and succeeding in high-growth regions.
- Value of DataM Reports: Our reports offer specialized insights tailored to the latest trends and specific business inquiries. The personalized approach provides a deeper, strategic perspective, ensuring you receive the precise information necessary to make informed decisions. The insights complement and go beyond what is typically available in generic databases.
What DATAM Uniquely Provides
- Heat-Source and Configuration-Level Market Intelligence: DATAM categorizes the demand for heat pumps according to air-to-air, air-to-water, ground-based, geothermal and other configurations, thereby allowing our customers to understand which heat sources are being adopted in particular applications and geographies.
- Refrigerant Transition Intelligence: DATAM analyzes the changeover from high global warming potential hydrofluorocarbons to low global warming potential refrigerants such as CO2, propane, ammonia and others and considers the different ramifications of refrigerant choices during processes of design, efficiency, safety establishment, compliance with regulations and manufacturer’s strategies of production.
- Application-Level Demand Assessment: Through the use of DATAM, it is possible to determine suitable ways of heat pumps in residential, industrial and commercial applications and to gain knowledge on the areas of its use like space heating, air conditioning, domestic hot water heating, building retrofitting and the requirements of heat process.
- Technology and Manufacturer Benchmarking: DATAM helps in comparing companies in terms of performance in cold climates, inverters used, heating capability, performance at high temperatures, smart controls used, refrigerants used and extent of product range.
- Opportunity Prioritization by Market Segment: DATAM associates type of product, kind of energy, the refrigerant used in manufacturing a product, product category, its capacity, power, end-user and regional market demand to determine market segments with maximum potential and assess their importance for further product development, geographical expansion, partnerships and investments.




























































