


Clean Room Technologies Market Size and Overview
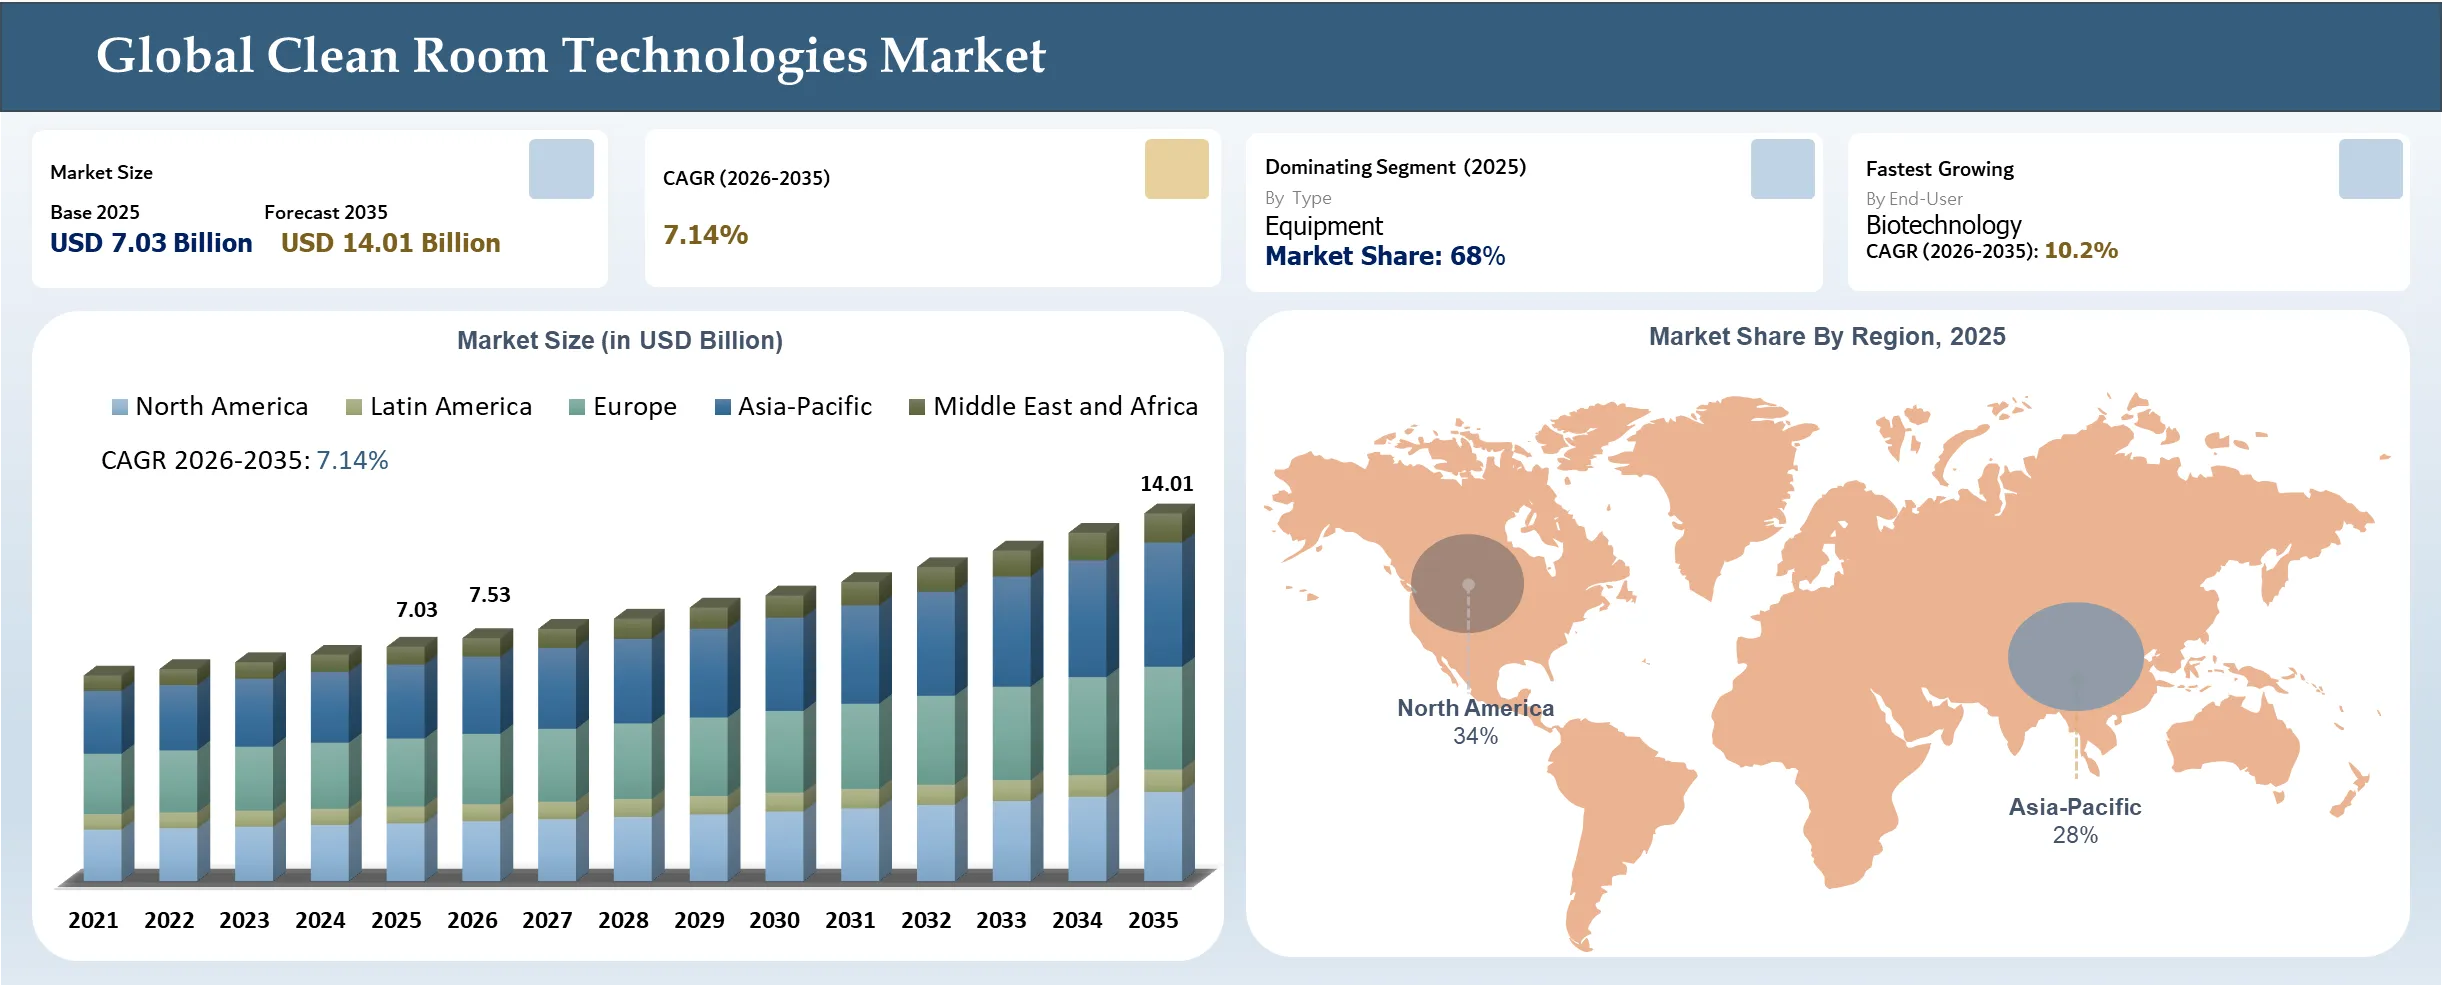
The global cleanroom technologies market reached USD 7.03 billion in 2025 and is expected to reach USD 14.01 billion by 2035, growing with a CAGR of 7.14% during the forecast period 2026-2035. The market is being shaped by increasing requirements for tightly controlled manufacturing environments across pharmaceuticals, biotechnology, medical devices, semiconductors, and other contamination-sensitive industries. Increased regulatory standards and rules in industries such as pharmaceuticals, biotechnology, healthcare and semiconductor production are driving demand for cleanroom technologies. Compliance with product quality, safety and contamination control laws involves the use of cleanroom facilities and equipment.
Cleanrooms are governed by strict norms and standards set by regulatory authorities such as the U.S. Food and Drug Administration, the European Medicines Agency and the International Organisation for Standardisation. In April 2026, VON ARDENNE GmbH, a Germany-based manufacturer of precision coating systems, commissioned its OPTA X300 deposition equipment at a newly established ISO 5 cleanroom facility in Dresden, Germany. The cleanroom is equipped with 200 m² of ISO 5 (Class 100) assembly and test bays with AMC capability and 400 m² of ISO 7 manufacturing floor space, totalling 600 m² of cleanroom space available for use in the semiconductor, optical, and space industries.
White-Space Opportunities for Semiconductor Cleanroom Infrastructure Investment
In May 2025, Idaho had approximately USD 27.8 billion of under-construction projects, with the semiconductor sector taking the largest investment share at USD 25 billion, led by Micron Technology’s semiconductor fabrication expansion in Boise. The project is supported by up to USD 6.1 billion in CHIPS and Science Act funding and involves more than 1 million square feet of new buildings, including a new cleanroom, water-treatment facility, gas plant, central utilities, and administrative facilities, creating substantial opportunities for cleanroom construction, HVAC and environmental-control systems, ultra-pure water, speciality gases, contamination-control equipment, filtration, monitoring, and facility-management technologies.
The semiconductor investment is accompanied by approximately USD 2.8 billion in other Idaho projects, with the dairy sector representing nearly USD 800 million of construction spending. The investment is expected to benefit companies across several cleanroom-related areas, with Micron Technology benefiting as the semiconductor fab owner and operator, while Exyte US benefits directly through cleanroom and advanced-facility engineering and construction, as it serves as the general contractor for the Boise project.
Air Liquide is benefiting from the semiconductor expansion through construction of a Boise production plant for ultra-pure nitrogen and other semiconductor gases, demonstrating additional investment opportunities in speciality-gas infrastructure and process utilities.
Clean Room Technologies Market Key Takeaways
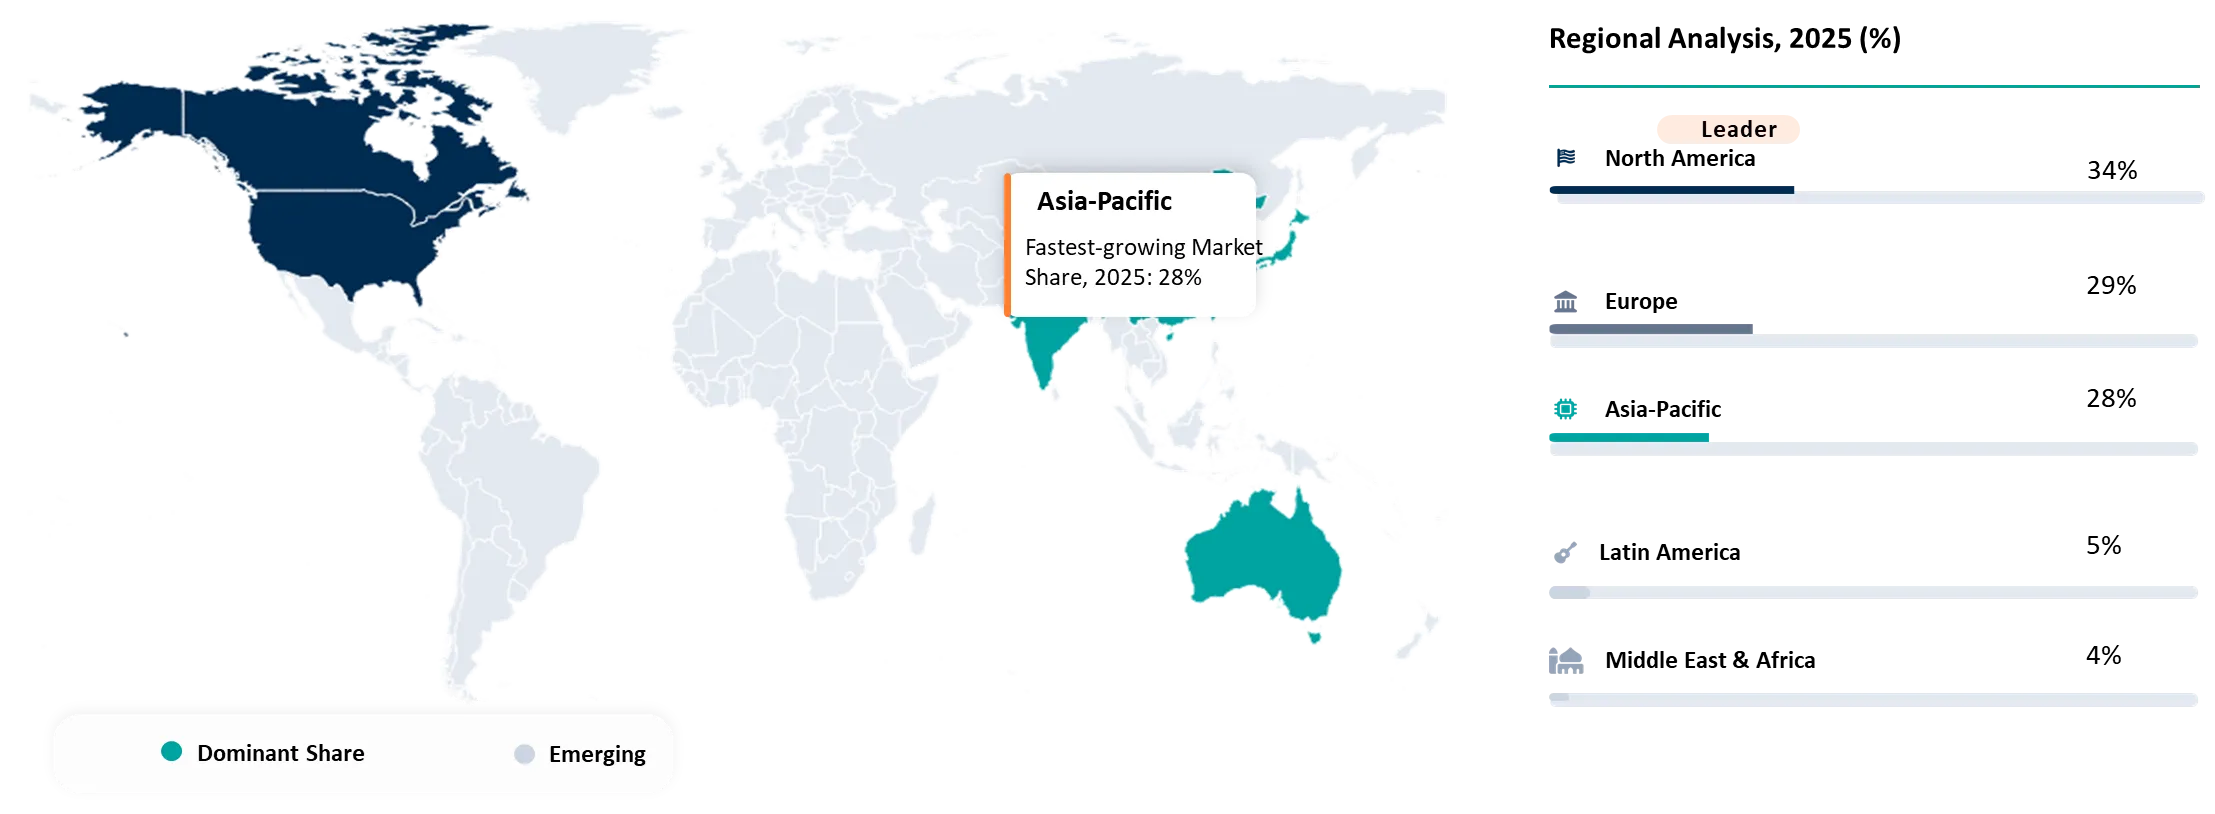
- North America held the largest share of the market in 2025, accounting for 34% of total revenue. Meanwhile, Asia-Pacific is expected to be the fastest-growing region with a 28% market share in 2025.
- Equipment dominated the product segment in 2025, capturing a 68% market share. The dominance is driven by high demand for HVAC systems, laminar flow units, and HEPA/ULPA filtration.
- Intel Corporation committed to a €5 billion (USD 5.7 billion) capital expansion at its Leixlip campus in Ireland in July 2026. It brings Intel's total regional investment to over €30 billion (USD 33.8 billion) since 1989.
- In Idaho, semiconductor investments represent USD 25 billion of a USD 27.8 billion project pipeline as of May 2025. The expansion includes Micron's project, supported by up to USD 6.1 billion in CHIPS Act funding.
Clean Room Technologies Market Industry Trends and Strategic Insight
- AI-enabled cleanroom control is shifting the market from fixed environmental management toward adaptive contamination control, with edge AI, sensor fusion, and real-time analytics increasingly supporting anomaly detection, predictive maintenance, and automated process decisions.
- Autonomous cleanroom operations are becoming a strategic priority, particularly in semiconductor manufacturing, where robotics, automated material handling, and intelligent inspection are being integrated to reduce human intervention and contamination exposure.
- Dynamic airflow management is replacing purely fixed ventilation strategies, with real-time particle measurements and operational conditions increasingly being used to adjust airflow and reduce unnecessary HVAC energy consumption while maintaining cleanliness requirements.
- Cleanroom cleaning and sanitization practices are becoming more structured and risk-based, with updated industry guidance addressing equipment-specific cleaning, decontamination, recovery planning, and monitoring effectiveness.
- The strategic value of cleanroom technologies is shifting from facility support to manufacturing-enabling infrastructure, because contamination-control performance increasingly influences yield, product quality, process reliability, regulatory compliance, and production continuity.
Clean Room Technologies Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 7.03 Billion | |
| 2035 Projected Market Size | USD 14.01 Billion | |
| CAGR (2026-2035) | 7.14% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Type | Equipment, Consumables | |
| By Construction Type | Standard/Drywall Cleanrooms, Hardwall Cleanrooms, Softwall Cleanrooms | |
| By Cleanliness | ISO 1 Cleanrooms, ISO 2 Cleanrooms, ISO 3 Cleanrooms, ISO 4 Cleanrooms, ISO 5 Cleanrooms, ISO 6 Cleanrooms, ISO 7 Cleanrooms, ISO 8 Cleanrooms, ISO 9 Cleanrooms | |
| By Certification | Class 1, Class 10, Class 100, Class 1000, Class 10000, Class 100000 | |
| By End-User | Pharmaceutical Industry, Semiconductor and Electronic, Biotechnology, Medical Devices Manufacturers, Automotive, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Clean Room Technologies Market Disruption Analysis
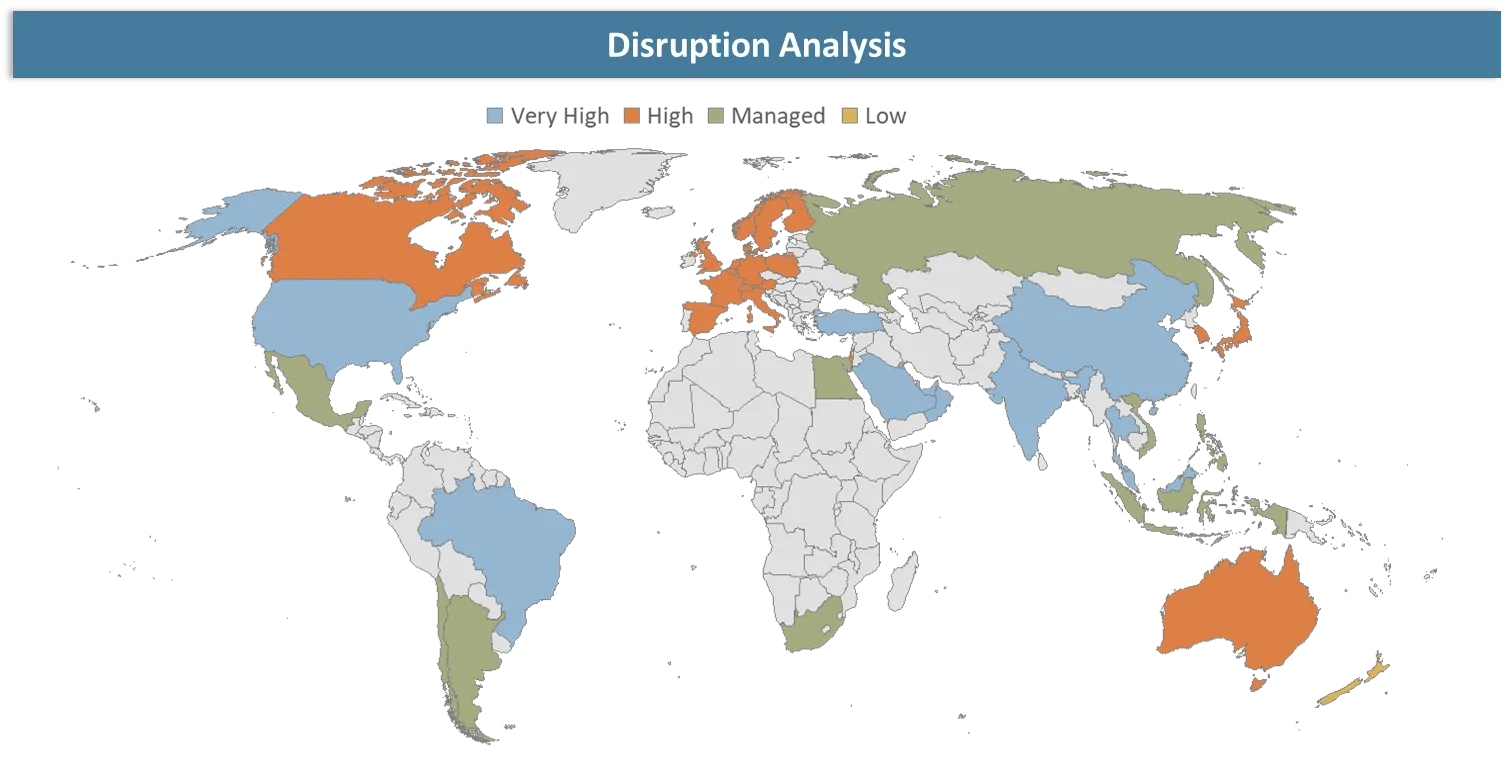
Shift Toward Intelligent, Modular, and Energy-Optimized Cleanroom Infrastructure Reshaping the Cleanroom Technologies Market
The disruption in the cleanroom technologies market is primarily associated with the transition from conventional, fixed cleanroom infrastructure toward modular, digitally monitored, AI-enabled, and energy-optimised contamination-control environments. Cleanrooms have moved away from being considered standard controlled areas and are now being designed based on certain process considerations. As a consequence, there is a move towards continuous monitoring of contamination in terms of particles and chemicals, digital HVAC control, automated airflows, and digital qualification, among others.
The shift is particularly evident in advanced semiconductor manufacturing, where large-scale production facilities are demanding substantially greater controlled environments and more sophisticated contamination management. In February 2026, Micron Technology, Inc. opened its semiconductor assembly and test facility in Sanand, Gujarat, with the first phase designed to include more than 500,000 square feet of cleanroom space. The facility represents a combined investment of approximately USD 2.75 billion by Micron and its government partners and is expected to assemble and test tens of millions of chips in 2026, scaling to hundreds of millions in 2027.
Clean Room Technologies Market BCG Matrix: Company Evaluation
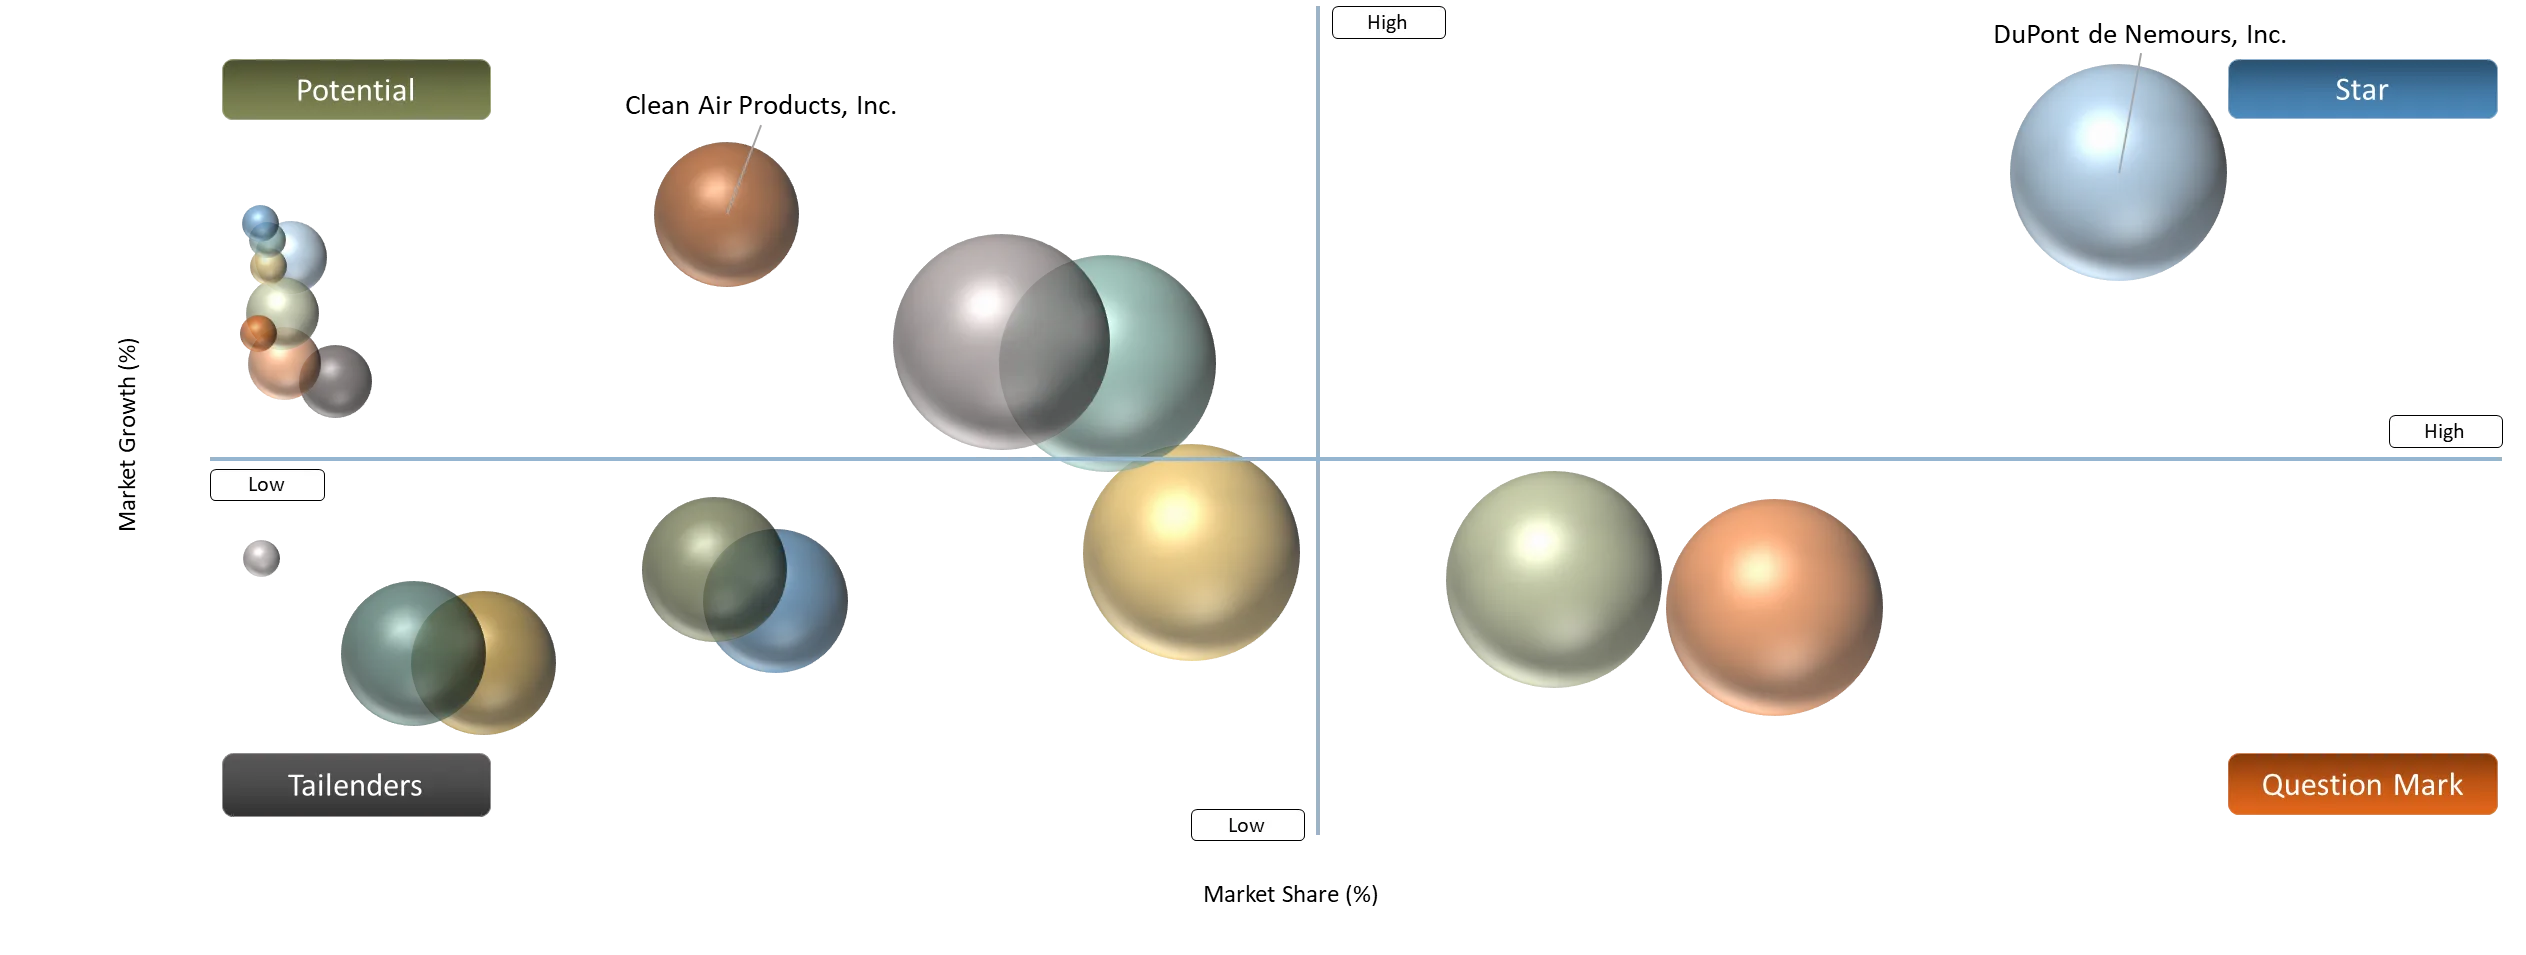
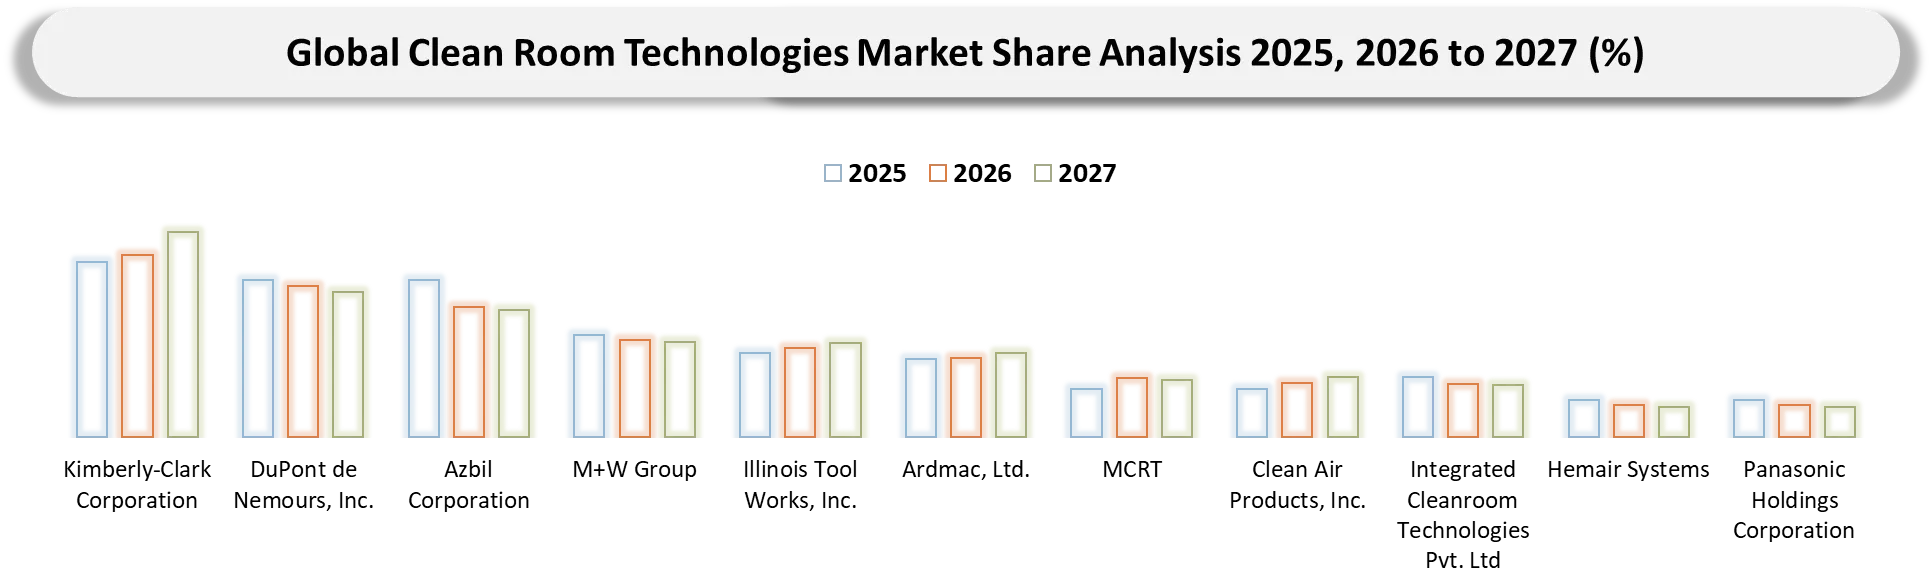
Stars include DuPont de Nemours, Inc., Azbil Corporation, and Kimberly-Clark Corporation, supported by their established positions in contamination-control materials, cleanroom monitoring and automation, and cleanroom consumables. Question Marks include M+W Group, Illinois Tool Works, Inc., Ardmac, Ltd., and MCRT. These companies have established capabilities in cleanroom design, construction, engineering, process equipment, and controlled-environment solutions, but compete in a fragmented market against larger integrated cleanroom technology providers.
Potential includes Clean Air Products, Inc., Integrated Cleanroom Technologies Pvt. Ltd., and Hemair Systems. The tailenders include Panasonic Holdings Corporation, whose cleanroom-related activities are more closely associated with specific electronics, manufacturing, and environmental-control applications rather than a broad cleanroom technology portfolio.
Clean Room Technologies Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
| High Prevalence of Chronic Diseases Globally | 24% | North America, Europe, Asia-Pacific | Pharmaceutical manufacturing, sterile injectable production, biologics, medical devices | Sustained demand for medicines, biologics, and sterile medical products increases investment in contamination-controlled manufacturing environments, including validated cleanrooms, HEPA/ULPA filtration, environmental monitoring, and controlled HVAC systems. |
Rapid growth of semiconductor and advanced electronics manufacturing is driving investments in high-precision cleanrooms. | 30% | Asia-Pacific, North America, East Asia | Semiconductor fabs, advanced packaging, MEMS, display manufacturing | Increases demand for ultra-clean environments, advanced filtration, molecular contamination control, precision HVAC, and continuous environmental monitoring. |
Increasing regulatory requirements for contamination control and product sterility are compelling pharmaceutical and medical-device manufacturers to upgrade cleanrooms. | 25% | North America, Europe, Asia-Pacific | Sterile drug manufacturing, aseptic processing, injectable production, medical devices | Accelerates cleanroom modernization, qualification, environmental monitoring, pressure control, and contamination-prevention investments. |
Expansion of biotechnology and advanced-therapy production is accelerating demand for specialised cleanrooms. | 21% | North America, Europe, Asia-Pacific | Cell and gene therapy, biologics, viral-vector manufacturing, advanced laboratories | Supports modular and flexible cleanrooms, closed processing environments, specialized containment, and real-time monitoring systems. |
Rapid growth of semiconductor and advanced electronics manufacturing is driving investments in high-precision cleanrooms
The rapid expansion of semiconductors and advanced electronics is increasing the investments being made into cleanroom facilities, since there is a need for highly controlled environments so that particles and chemicals do not contaminate the advanced chips being manufactured. The increased use of AI, advanced computing, 5G and 6G technologies, healthcare electronics, and defence systems is increasing the demand for semiconductor production and, therefore, the need for advanced cleanroom facilities.
In parallel, the Semiconductor Industry Association (SIA) reported that global semiconductor sales reached a record USD 795.6 billion in 2025 and are projected to reach USD 1.5 trillion in 2026. The report also states that semiconductor companies have announced more than USD 770 billion in private-sector investments across 160 projects in 30 U.S. states since 2020, covering manufacturing, equipment, materials, packaging, and research. The investments are strengthening the semiconductor manufacturing ecosystem and creating additional requirements for high-specification cleanrooms capable of supporting increasingly advanced production processes.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High upfront investment for advanced cleanroom infrastructure can restrict adoption. | 32% | Capital expenditure and facility expansion | Semiconductor fabs, pharmaceutical manufacturing, biotechnology facilities, medical-device production | Raises entry barriers and lengthens investment cycles, encouraging manufacturers to prioritise phased upgrades, cleanroom retrofits, modular designs, and reuse of existing controlled environments. |
High energy consumption of cleanroom HVAC and airflow systems remains a major restraint. | 28% | Operating costs and energy efficiency | Semiconductor fabs, pharmaceutical cleanrooms, laboratories, sterile manufacturing facilities | Increases operating expenditure and sustainability pressures, accelerating demand for energy-efficient HVAC, optimised airflow, variable-speed systems, heat recovery, and intelligent environmental controls. |
Stringent qualification, validation, and contamination-control requirements increase the complexity. | 23% | Regulatory compliance and facility qualification | Aseptic pharmaceutical production, biologics, medical devices, semiconductor manufacturing | Extends commissioning and validation timelines and increases compliance costs, strengthening demand for automated monitoring, continuous environmental control, documented qualification, and integrated contamination-management systems. |
Shortage of specialised cleanroom engineering and technical personnel can constrain the expansion and efficient operation of advanced facilities. | 17% | Workforce availability and operational expertise | Cleanroom design and construction, facility commissioning, maintenance, environmental monitoring, semiconductor and biopharma production | Limits the speed of facility deployment and increases reliance on specialised contractors, automation, remote monitoring, standardised designs, and integrated technology platforms. |
High upfront investment for advanced cleanroom infrastructure can restrict adoption
One of the primary restraints limiting the adoption of advanced cleanroom technology is the capital required to implement it in the first place. Advanced cleanrooms entail special HVAC, filtration, pressure control, cleanroom materials, utility and monitoring systems, as well as qualification. It making the facilities aspect an important part of the capital requirement, especially for companies involved in biotechnology and pharmaceuticals that have to provide GMP facilities.
Advanced semiconductor manufacturing requires substantial capital investment to upgrade cleanroom infrastructure, fabrication equipment, and automated production systems. In July 2026, Intel Corporation announced a €5 billion (USD 5.7 billion) capital investment at its Leixlip campus in Ireland to expand advanced semiconductor manufacturing. The project includes upgrading existing fabrication facilities, installing leading-edge manufacturing equipment, and expanding the automated track system, while utilising existing cleanroom space. Intel stated that it has invested more than €30 billion (USD 33.8 billion) in Ireland since 1989, and the Leixlip campus employs 4,900 people.
Clean Room Technologies Market Segment Analysis
The global cleanroom technologies market is segmented based on type, construction type, cleanliness, certification, end-user, and region.
Advanced Equipment Deployment Supporting the Dominance of Equipment in Cleanroom Technologies
The equipment segment dominates the cleanroom technologies market, with a 68% market share in 2025, owing to the essential requirement of cleanroom air showers, HVAC systems, laminar flow systems, high-efficiency filters, desiccator cabinets and fan filter units for creating and maintaining controlled manufacturing processes. In contrast to cleanroom consumables, cleanroom equipment is the primary component needed to control particulate matter, airflow, temperature, humidity, pressure, and contamination.
Demand is also being reinforced by pharmaceutical manufacturers upgrading existing production facilities to meet stricter quality and manufacturing requirements. In February 2026, India's Department of Pharmaceuticals reported that the Revised Pharmaceutical Technology Upgradation Assistance Scheme (RPTUAS) had an outlay of ₹300.10 crore (USD 31.12 million) for FY2024-25 to FY2025-26, providing for incentives in the amount of 10% - 20% of the qualifying investment, not exceeding ₹2 crore (USD 0.21 million) per unit. The technology upgradation which is encouraged includes the HVACs and cleanrooms.
Clean Room Technologies Market Geographical Penetration
North America: Established Semiconductor and Pharmaceutical Manufacturing Base Sustaining Regional Leadership
North America dominates the cleanroom technologies market, with a 34% market share in 2025, owing to its mature semiconductor, pharmaceutical, biotech, medical devices, and advanced manufacturing industry. The region has a well-established industrial base of manufacturing plants where there is a need for precise particle management, HVAC systems, HEPA/ULPA filters, environmental monitoring systems, and contamination control systems. Reshoring of semiconductor and other manufacturing processes will only increase the demand in the future.
The expansion highlights the growing specialisation of cleanroom providers toward highly regulated pharmaceutical and biotechnology manufacturing environments. In June 2025, Angstrom Technology, a U.S.-based cleanroom design, construction, and maintenance company, established Angstrom Life Science Solutions as a separate business unit focused on pharmaceutical, biotechnology, and advanced life-science manufacturing. The new unit specialises in cleanroom design, construction, certification, and regulatory support, with expertise covering FDA, EU, and Health Canada requirements, strengthening the company’s offering for regulated controlled environments.
U.S. Clean Room Technologies Market Trends
The U.S. holds a dominant position in the cleanroom technologies market because of its robust pharmaceuticals, biotech, semiconductors, medical devices, and advanced electronics manufacturing industry. Reshoring efforts and capacity building in crucial manufacturing operations in the country are fueling the demand for controlled manufacturing environments. Investments in semiconductor foundries, pharmaceutical manufacturing plants, and other advanced manufacturing facilities are thus helping boost demand for cleanroom HVAC, efficient air filters, airflow control equipment, environmental monitoring solutions, and contamination control systems.
The U.S. expansion reflects rising demand for specialised cleanroom infrastructure across pharmaceutical and biotechnology manufacturing. In October 2025, KEMMLIT-Bauelemente GmbH, a Germany-based cleanroom and furnishing systems manufacturer, launched KEMMLIT Cleanroom USA to expand its cleanroom design and engineering capabilities into the U.S. market. The company introduced the new division at the ISPE Annual Meeting & Expo 2025 in Charlotte, targeting pharmaceutical, biotechnology, and other regulated manufacturing environments.
Canada Clean Room Technologies Market Outlook
Canada is an important country within North America's cleanroom technologies market, supported by its growing semiconductor, biotechnology, pharmaceutical, photonics, and advanced medical-device manufacturing base. The country's focus on strengthening domestic production of critical technologies is encouraging investment in specialised manufacturing facilities that require controlled environments, advanced filtration, HVAC systems, environmental monitoring, and contamination-control infrastructure.
The launch strengthens the availability of specialised airflow and contamination-control solutions for controlled environments across Canada. In October 2025, DENIOS SE, a Germany-based manufacturer and provider of workplace safety, environmental protection, and hazardous-material management solutions, introduced advanced airflow and containment technologies for Canadian workplaces through DENIOS Ltd., its Canadian subsidiary based in Newmarket, Ontario. The portfolio includes fume hoods, laboratory workstations, downflow containment booths, and laminar-flow hoods, with laminar-flow systems using HEPA filtration and capable of supporting ISO 5 cleanroom conditions for pharmaceutical, biotechnology, healthcare, and food applications.
Rapid Semiconductor Capacity Expansion and Advanced Manufacturing Investment Strengthening Asia-Pacific
The Asia-Pacific is the fastest-growing region in the cleanroom technologies market, accounting for a 28% market share in 2025, supported by its extensive semiconductor, electronics, pharmaceutical, biotechnology, and medical-device manufacturing base. The region's concentration of advanced manufacturing clusters in Singapore, Taiwan, South Korea, Japan, and China creates sustained demand for controlled production environments, including high-efficiency filtration, HVAC systems, fan filter units, laminar airflow systems, and contamination-monitoring technologies.
The product launch highlights continued innovation in advanced airflow and contamination-control technologies across Asia-Pacific’s high-precision manufacturing sector. In April 2026, Shinsung E&G Co., Ltd., a South Korea-based cleanroom, dry-room, and renewable-energy technology company, showcased its new FFU-based cleanroom technologies at AIR FAIR 2026 in Seoul. The company presented the V-Master, which removes more than 95% of airborne VOCs, along with the ICF (Internal Chemical Filter FFU) and ILF (Integrated Lighting FFU) for semiconductor, display, and secondary-battery manufacturing environments.
Japan Clean Room Technologies Market Trends
Japan is one of the key countries in the Asia-Pacific cleanroom technologies market, supported by its established semiconductor, electronics, pharmaceutical, biotechnology, and precision-manufacturing ecosystem. The country's renewed focus on domestic advanced-semiconductor production is increasing the development of highly controlled manufacturing environments requiring sophisticated HVAC, filtration, airflow management, contamination monitoring, and cleanroom equipment.
The development reflects rising demand for specialised GMP-compliant cleanroom infrastructure supporting Japan’s cell and gene therapy manufacturing ecosystem. In May 2025, iPark Institute Co., Ltd., a Japan-based life-science innovation park operator, announced the development of a 1,200 m² rental Cell Processing Centre (CPC) at Shonan Health Innovation Park, scheduled to begin operations in November 2025. The facility will comprise two independent modular cleanroom units with Grade A, B, and C areas and will support early-stage manufacturing of cell therapies and regenerative-medicine products, including cell-bank production and Phase 1/2 clinical-trial manufacturing.
Clean Room Technologies Market Competitive Landscape
- The cleanroom technologies market is characterised by four key participant groups: cleanroom consumables and contamination-control suppliers, cleanroom engineering and construction companies, environmental-control and automation specialists, and modular cleanroom solution providers. DuPont de Nemours, Inc., Kimberly-Clark Corporation, and Illinois Tool Works, Inc. have historically participated through contamination-control, wipes, apparel, and industrial products, while Azbil Corporation focuses on measurement, automation, and environmental control technologies. M+W Group, Ardmac Ltd., and MCRT compete primarily through cleanroom engineering, construction, facility integration, and controlled-environment solutions, while Clean Air Products, Inc., Integrated Cleanroom Technologies Pvt. Ltd., and Hemair Systems provide modular cleanroom systems, equipment, and contamination-control solutions. Panasonic Holdings Corporation has exposure to controlled manufacturing environments through its electronics and advanced manufacturing activities.
- Key players include Kimberly-Clark Corporation (United States), DuPont de Nemours, Inc. (United States), Azbil Corporation (Japan), M+W Group (Germany), Illinois Tool Works, Inc. (United States), Ardmac Ltd. (Ireland), MCRT (United States), Clean Air Products, Inc. (United States), Integrated Cleanroom Technologies Pvt. Ltd. (India), Hemair Systems (India), and Panasonic Holdings Corporation (Japan).
Key Developments
- April 2026: Freudenberg Medical, a Germany-based medical-device and biopharmaceutical contract development and manufacturing organisation (CDMO), launched CleanAssure, an ISO Class 5 controlled cleanroom for cleaning and sterilising single-use assemblies used in biopharmaceutical manufacturing.
- January 2026: Cleanova, a U.S.-based industrial filtration solutions manufacturer, announced the strategic acquisition of Airflotek and TES-Clean Air Systems, both U.S.-based cleanroom and air-filtration companies.
- July 2025: Greylane LLC, a U.S.-based holding company, acquired AirCare Automation, a U.S.-based cleanroom controls and monitoring technology company.
- July 2026: Klaritex Cleanroom Solutions Inc., a Canada-based privately held cleanroom personal protective equipment (PPE) company, launched enhanced fog-resistant cleanroom protective eyewear designed for regulated environments.
- October 2025: CleanSpace, a U.S.-based design-build company specialising in cleanrooms, controlled environments, life sciences, healthcare, and advanced manufacturing, acquired TECHspace, a U.S.-based Special Project Delivery (SPD) firm and certified Women's Business Enterprise (WBE).
Key Procurement Priorities and Buyer Evaluation Criteria
- Organisations investing in the cleanroom technologies market increasingly select suppliers based on their ability to provide integrated cleanroom solutions that deliver stringent contamination control, stable airflow, precise temperature and humidity management, and reliable operation across pharmaceutical, semiconductor, biotechnology, and medical-device manufacturing environments.
- The procurement decision-making process is increasingly influenced by the need for energy-efficient HVAC systems, advanced filtration, automated environmental monitoring, modular cleanroom designs, and scalable infrastructure, particularly as manufacturers seek to expand production capacity while controlling operating costs and maintaining stringent cleanliness requirements.
- Buyers consider factors such as ISO cleanliness performance, HEPA/ULPA filtration efficiency, airflow uniformity, pressure control, temperature and humidity stability, energy consumption, equipment reliability, maintenance requirements, validation capability, and total cost of ownership when selecting cleanroom technology suppliers.
Why Choose DataM?
- Technological Innovations: Explores advancements in cleanroom technologies, including HEPA/ULPA filtration, advanced HVAC systems, fan filter units, laminar airflow systems, modular cleanrooms, automated environmental monitoring, and digitally controlled contamination-management solutions, enabling higher cleanliness, energy efficiency, and process stability across semiconductor, pharmaceutical, biotechnology, and medical-device applications.
- Product Performance & Market Positioning: Evaluates how different players deliver cleanroom solutions based on particle-control efficiency, airflow uniformity, temperature and humidity stability, pressure control, energy consumption, modularity, and operational reliability, highlighting how leading companies differentiate through integrated systems, customisation, scalability, and compliance with stringent cleanliness requirements.
- Real-World Evidence: Highlights adoption of cleanroom technologies across semiconductor fabs, pharmaceutical manufacturing facilities, biotechnology laboratories, medical-device production, and advanced electronics facilities, demonstrating benefits such as reduced contamination risk, improved process yields, enhanced product quality, regulatory compliance, and controlled manufacturing conditions.
- Market Updates & Industry Changes: Tracks key developments such as cleanroom capacity expansions, semiconductor and pharmaceutical facility investments, modular cleanroom deployments, advanced filtration innovations, energy-efficient HVAC systems, and regional manufacturing investments across Asia-Pacific, North America, and Europe, supporting the transition toward higher-performance and digitally managed controlled environments.
- Competitive Strategies: Analyses how leading companies expand through technology innovation, facility-scale projects, modular construction, strategic partnerships, automation, and integration of filtration, HVAC, monitoring, and contamination-control technologies to address increasing requirements from semiconductor, pharmaceutical, biotechnology, and medical-device industries.
- Pricing & Market Access: Explains pricing variations based on cleanroom classification, facility size, construction type, filtration requirements, HVAC complexity, monitoring systems, and degree of automation, along with market access through cleanroom technology manufacturers, engineering and construction companies, system integrators, distributors, and specialised contamination-control providers.
- Market Entry & Expansion: Identifies growth opportunities driven by semiconductor capacity expansion, pharmaceutical and biologics manufacturing, biotechnology development, medical-device production, advanced electronics, and high-purity manufacturing, while outlining strategies such as regional production expansion, modular cleanroom deployment, energy-efficient system development, technology differentiation, and partnerships with facility operators and engineering firms.
Target Audience 2026
- Cleanroom Technology Manufacturers
- Cleanroom Construction & Engineering Companies
- Pharmaceutical & Biopharmaceutical Companies
- Semiconductor & Electronics Manufacturers
- Biotechnology & Advanced-Research Organizations
- Medical Device Manufacturers
- Automotive, Aerospace & Advanced Manufacturing Companies





























































