


Executive CI Snapshot
The global mRNA vaccine landscape is entering a new phase of commercialization, moving beyond COVID-19 toward RSV, seasonal influenza, combination respiratory vaccines, pandemic preparedness, emerging infectious diseases and therapeutic oncology. The market is estimated at approximately US$6.3 billion in 2025, with future growth increasingly supported by non-COVID indications. Moderna and Pfizer/BioNTech remain the leading commercial players, while GSK, Arcturus Therapeutics, Daiichi Sankyo and other developers are intensifying competition through differentiated platforms and pipeline expansion. Approved products including COMIRNATY, SPIKEVAX, MRESVIA, MNEXSPIKE, KOSTAIVE, DAICHIRONA and MFLUSIVA demonstrate growing regulatory validation across multiple vaccine categories. Competitive differentiation is shifting toward efficacy, durability, safety, antigen breadth, dose efficiency, thermostability, combination potential and manufacturing economics. Self-amplifying RNA, advanced LNP systems and multivalent formulations could reshape future competition. Long-term leadership will depend on building scalable, multi-indication mRNA franchises with strong clinical and commercial differentiation.
Key Highlights
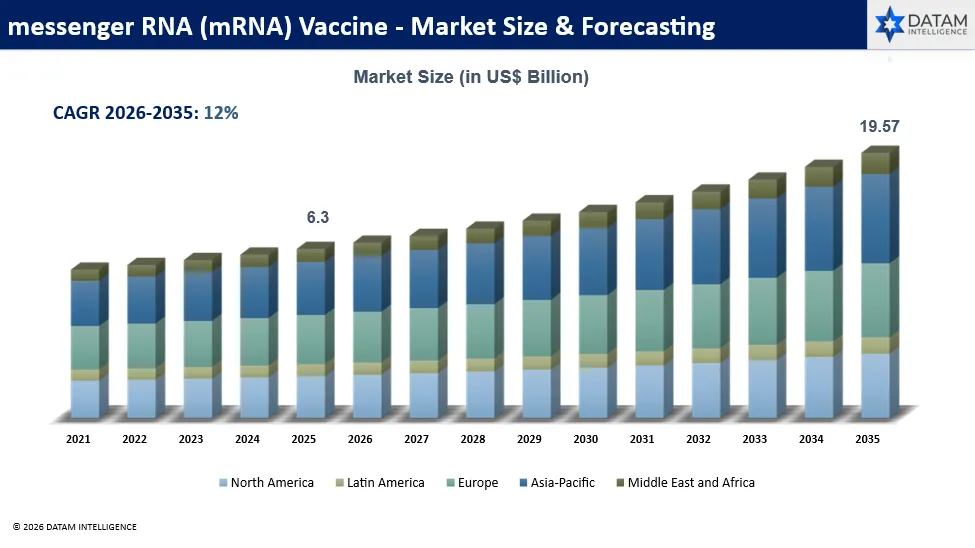
- The global mRNA vaccine market reached approximately US$6.3 billion in 2025 and is projected to reach US$19.57 billion by 2035, expanding at a 12% CAGR during 2026-2035.
- The market is transitioning from a COVID-19-centric model toward a multi-indication platform spanning RSV, seasonal and pandemic influenza, combination respiratory vaccines, emerging infectious diseases and therapeutic oncology.
- Commercial validation has broadened through approved products including COMIRNATY, SPIKEVAX, DAICHIRONA, KOSTAIVE, MRESVIA, MNEXSPIKE and MFLUSIVA, demonstrating regulatory acceptance across COVID-19, RSV and seasonal influenza.
- Moderna and Pfizer/BioNTech remain the principal strategic leaders, supported by commercial franchises, global regulatory experience and broad pipelines, while GSK, Arcturus Therapeutics and Daiichi Sankyo are strengthening competitive pressure.
- Pipeline activity is expanding into norovirus, CMV, EBV, Lyme disease, mpox, pandemic influenza and therapeutic cancer vaccines, with Moderna maintaining one of the broadest development portfolios.
- Competitive differentiation is shifting toward efficacy, durability, safety, antigen breadth, dose efficiency, thermostability, combination-vaccine potential and manufacturing economics, rather than platform novelty alone.
- Self-amplifying RNA, advanced LNP delivery, multivalent constructs and thermostable formulations are emerging as important next-generation technologies capable of reshaping competitive positioning.
- Long-term market leadership will depend on the ability to convert flexible RNA platforms into clinically differentiated, scalable and commercially sustainable products across multiple indications.
mRNA Vaccine Landscape Overview
The mRNA vaccine landscape has evolved from a COVID-19-focused market into a broader multi-indication platform spanning RSV, seasonal influenza, combination respiratory vaccines, pandemic preparedness and emerging infectious diseases. Commercial validation through COMIRNATY, SPIKEVAX, MRESVIA, MNEXSPIKE and MFLUSIVA has strengthened confidence in mRNA as a scalable vaccine technology. Competition is increasingly shifting toward broader antigen coverage, improved durability, lower-dose formulations, reduced reactogenicity, thermostability and manufacturing efficiency. Next-generation approaches including self-amplifying RNA, advanced lipid nanoparticle delivery, multivalent constructs and combination vaccines are emerging as important differentiators. Pipeline activity is also expanding into CMV, EBV, norovirus, HIV, tuberculosis, malaria and therapeutic oncology. Future market leadership will depend on the ability to translate flexible mRNA platforms into clinically differentiated, cost-efficient products across multiple indications while maintaining rapid development timelines, scalable manufacturing and strong regulatory execution.
Approved Product Intelligence
| Brand and Generic Name | Sponsor | Disease / Indication | Approval Date | MOA |
COMIRNATY (BNT162b2) | BioNTech Manufacturing GmbH / Pfizer | COVID-19 | August 23, 2021- U.S. FDA | Nucleoside-modified mRNA delivered through LNPs encodes the SARS-CoV-2 spike antigen, inducing neutralizing antibody and cellular immune responses. |
SPIKEVAX (mRNA-1273) | ModernaTX, Inc. | COVID-19 | January 31, 2022 - U.S. FDA | Nucleoside-modified mRNA in LNPs encodes the prefusion-stabilized SARS-CoV-2 spike protein, stimulating humoral and cellular immunity. |
DAICHIRONA (DS-5670 / Ufrenmeran) | Daiichi Sankyo Co., Ltd. | COVID-19 | August 2023 - Japan MHLW | LNP-formulated mRNA directs host cells to produce SARS-CoV-2 spike antigen, generating an adaptive immune response against COVID-19. |
KOSTAIVE (ARCT-154 / Zapomeran) | Meiji Seika Pharma / CSL / Arcturus Therapeutics | COVID-19 | November 28, 2023 -Japan MHLW | Self-amplifying mRNA encodes SARS-CoV-2 antigen with replication machinery that amplifies RNA intracellularly, enabling antigen production at comparatively low doses. |
MRESVIA (mRNA-1345) | ModernaTX, Inc. | Respiratory Syncytial Virus (RSV) | May 31, 2024 - U.S. FDA | LNP-encapsulated nucleoside-modified mRNA encodes prefusion-stabilized RSV F glycoprotein, inducing neutralizing immunity against RSV-associated disease. |
MNEXSPIKE (mRNA-1283) | ModernaTX, Inc. | COVID-19 | May 30, 2025 - U.S. FDA | Nucleoside-modified mRNA encodes selected N-terminal and receptor-binding domains of the SARS-CoV-2 spike protein. |
MFLUSIVA (mRNA-1010) | ModernaTX, Inc. | Seasonal Influenza A and B | August 5, 2026 - U.S. FDA | Trivalent LNP-formulated mRNA vaccine encoding influenza hemagglutinin antigens from represented influenza A and B strains. |
Commercial Performance and Geographic Expansion of COMIRNATY
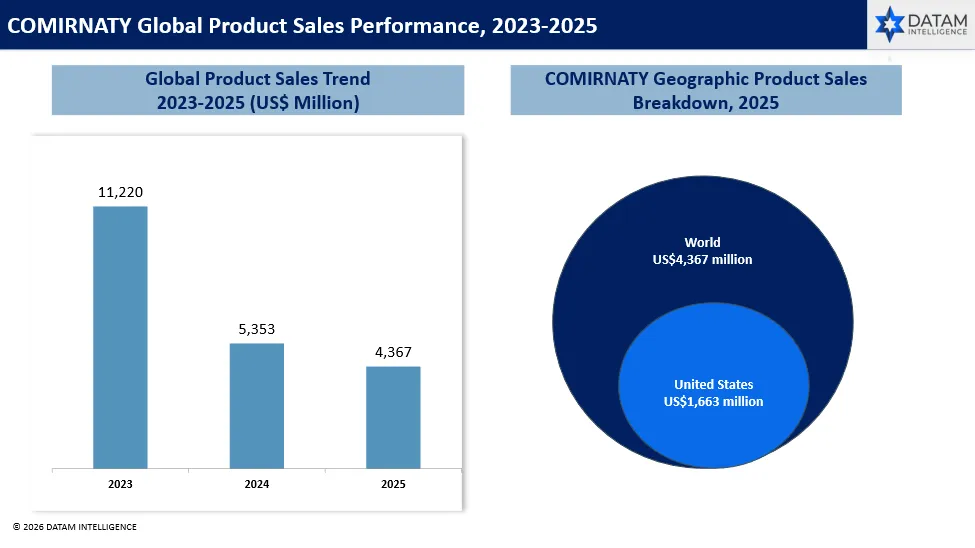
COMIRNATY recorded a sharp normalization in global product sales between 2023 and 2025, reflecting the transition from pandemic-driven demand toward a more seasonal COVID-19 vaccination market. Global revenue declined from US$11,220 million in 2023 to US$5,353 million in 2024, representing a year-on-year contraction of approximately 52.3%. Sales decreased further to US$4,367 million in 2025, down about 18.4% compared with 2024. Overall, revenue fell by nearly 61.1% over the 2023-2025 period. In 2025, the United States generated US$1,663 million, accounting for approximately 38.1% of worldwide COMIRNATY revenue. The remaining US$2,705 million, or approximately 61.9%, was generated across international markets. The geographic mix therefore indicates that COMIRNATY continues to maintain a broad international commercial presence despite declining overall sales. Future performance will depend increasingly on seasonal vaccination uptake, variant-adapted formulations, government procurement, reimbursement dynamics and competitive positioning within the evolving COVID-19 vaccine landscape.
Competitive Evolution of the mRNA Vaccine Landscape
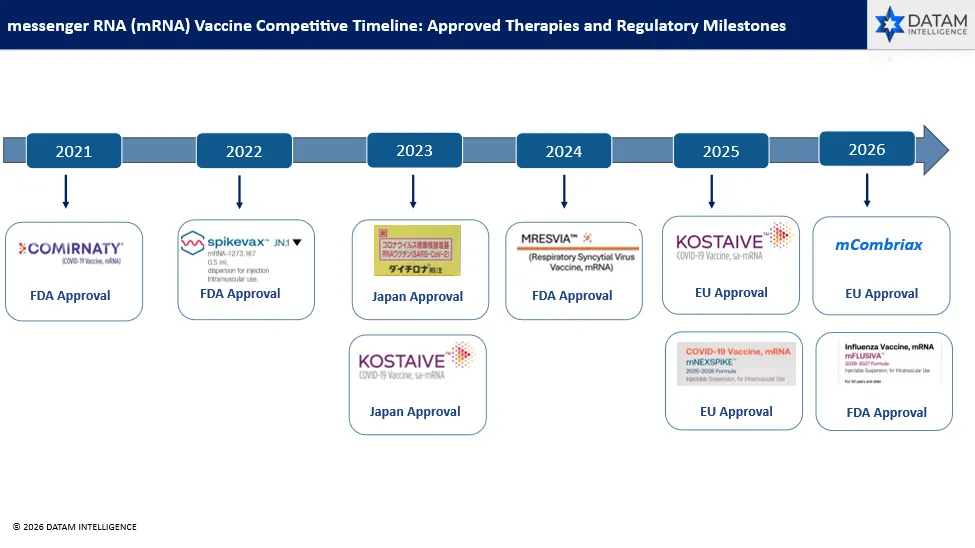
The mRNA vaccine competitive landscape has expanded rapidly from COVID-19-focused products toward broader respiratory vaccine applications and next-generation RNA platforms. COMIRNATY received FDA approval in 2021, followed by SPIKEVAX in 2022, establishing commercial and regulatory validation for conventional mRNA vaccines. In 2023, Japan strengthened its domestic and next-generation mRNA ecosystem through approval of DAICHIRONA and the self-amplifying mRNA vaccine KOSTAIVE. The landscape diversified further in 2024 with FDA approval of MRESVIA, extending mRNA technology beyond COVID-19 into RSV prevention. During 2025, regulatory expansion continued through European approvals involving KOSTAIVE and newer mRNA vaccine formulations. In 2026, mCOMBRIAX marked an important milestone for combination influenza and COVID-19 vaccination in Europe, while mFLUSIVA expanded the technology into seasonal influenza following FDA approval. Overall, the timeline demonstrates a clear shift toward multi-indication commercialization, geographic expansion and next-generation mRNA innovation.
Pipeline Intelligence
The mRNA vaccine pipeline is expanding beyond COVID-19 into seasonal and pandemic influenza, norovirus, CMV, EBV, Lyme disease, mpox, RSV and therapeutic oncology. Moderna maintains one of the broadest pipelines, with late-stage programs such as mRNA-1018 for pandemic influenza and mRNA-1403 for norovirus, alongside multiple Phase II infectious-disease candidates. GSK is advancing its next-generation mRNA seasonal influenza vaccine, while Pfizer continues development of standalone influenza, COVID-19 plus influenza combination and self-amplifying RNA candidates. Arcturus Therapeutics is strengthening the next-generation platform landscape through ARCT-2304, a self-amplifying mRNA vaccine targeting H5N1 influenza. Oncology represents another major growth frontier, led by Moderna and Merck’s mRNA-4157 personalized cancer vaccine and BioNTech programs including BNT113, BNT116 and BNT122. Overall, competitive differentiation is increasingly centered on broader indication coverage, lower-dose platforms, combination vaccines, clinical durability and successful translation of mRNA technology into therapeutic cancer applications:
| Sponsor / Company | Candidate | Indication | Clinical Stage | mRNA Platform | Current Pipeline Status | |||
| Moderna | mRNA-1018 | Pandemic Influenza | Phase III | Nucleoside-Modified mRNA | One of Moderna’s most advanced non-commercial infectious-disease vaccine programs. | |||
| Moderna | mRNA-1403 | Norovirus | Phase III | mRNA | Phase III interim analysis did not meet statistical criteria for early success. | |||
| Moderna | mRNA-1405 | Norovirus | Phase II | mRNA | Alternative norovirus candidate supporting Moderna’s enteric-virus franchise. | |||
| Moderna | mRNA-1647 | CMV in Transplant Recipients | Phase II | Multivalent mRNA | Current development is focused on transplant-recipient prevention rather than the earlier broader CMV program. | |||
| Moderna | mRNA-1189 | EBV / Infectious Mononucleosis Prevention | Phase II | mRNA | Targets prevention of primary EBV-associated infectious mononucleosis. | |||
| Moderna | mRNA-1195 | EBV Long-Term Sequelae | Phase II | mRNA | Designed to address longer-term complications associated with EBV infection. | |||
| Moderna | mRNA-1975 | Lyme Disease | Phase II | mRNA | Part of Moderna’s two-candidate Lyme vaccine strategy. | |||
| Moderna | mRNA-1982 | Lyme Disease | Phase II | mRNA | Parallel Lyme disease vaccine candidate supporting antigen/platform optimization. | |||
| Moderna | mRNA-1769 | Mpox | Phase II | mRNA | Important public-health vaccine program expanding mRNA into orthopoxvirus prevention. | |||
| Moderna | mRNA-1345 | Pediatric RSV | Phase II | Nucleoside-Modified mRNA | Pediatric development extends the commercial MRESVIA platform into younger populations. | |||
| GSK | GSK4382276 / mRNA Seasonal Flu | Seasonal Influenza | Phase II; Phase III planned September 2026 | Second-Generation mRNA | Positive Phase II results showed stronger immune responses versus licensed comparators. | |||
| GSK | mRNA COVID-19 Candidate | COVID-19 | Phase II | Second-Generation mRNA | Originated from the CureVac collaboration; GSK now holds global development and commercialization rights. | |||
| GSK | mRNA Flu H5N1 | Pre-Pandemic Influenza A/H5N1 | Phase I/II | mRNA | Pandemic-preparedness program targeting avian influenza. | |||
Therapeutic mRNA Cancer Vaccine Pipeline
| Sponsor / Company | Candidate | Indication | Clinical Stage | mRNA Platform | Current Pipeline Status | |||
| Moderna / Merck | mRNA-4157 | Adjuvant Melanoma | Phase III | Individualized Neoantigen mRNA | One of the most advanced personalized mRNA cancer vaccine programs globally. | |||
| Adjuvant NSCLC | Multiple Phase III NSCLC programs broaden its potential beyond melanoma. | |||||||
| BioNTech | BNT113 | HPV16+, PD-L1+ Head and Neck Cancer | Phase III | FixVac Off-the-Shelf mRNA | Late-stage oncology asset encoding HPV16 E6/E7 antigens. | |||
| BNT116 | Advanced NSCLC | Phase I | FixVac mRNA | Recruiting trial evaluating BNT116 alone and in multiple combination regimens. | ||||
| BioNTech / Genentech | Autogene Cevumeran / BNT122 | Adjuvant Pancreatic Cancer | Phase II | Individualized Neoantigen-Specific Immunotherapy | Remains an important individualized mRNA cancer-vaccine program in pancreatic cancer. | |||
Market Size & Forecasting
The global Messenger RNA (mRNA) Vaccine market stood at US$6.3 billion in 2025 and is expected to reach US$19.57 billion by 2035, growing with a CAGR of 12% during the forecast period 2026-2035.
Request for Exclusive Sample: https://www.datamintelligence.com/download-sample/messenger-rna-mrna-vaccine-market
Competitive Landscape and Market Positioning
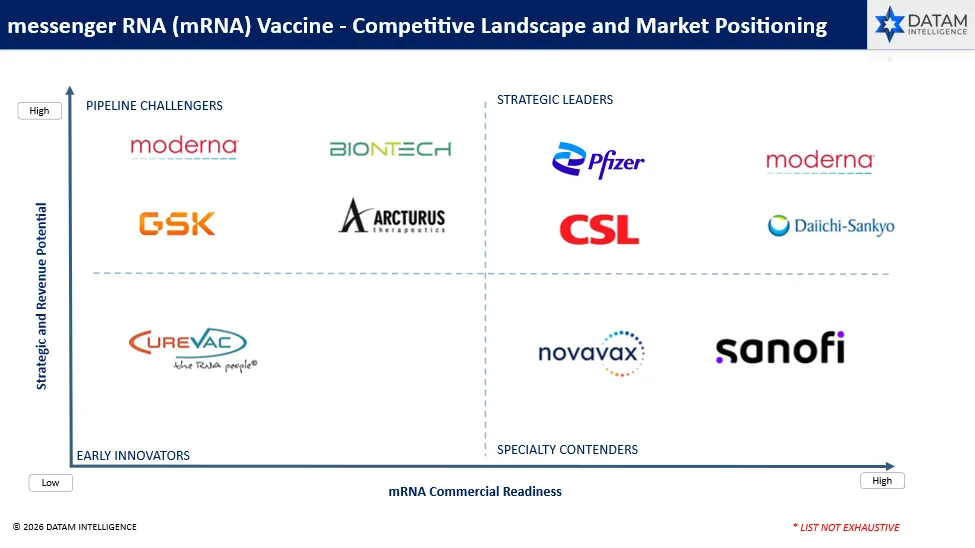
The mRNA vaccine competitive landscape is increasingly differentiated by commercial readiness, platform maturity, pipeline breadth and long-term revenue potential. Moderna and Pfizer/BioNTech remain the strongest strategic leaders, supported by commercially validated COVID-19 franchises, extensive regulatory experience, global commercialization capabilities and expanding pipelines across respiratory and therapeutic indications. Moderna has further strengthened its position through RSV and influenza approvals, reducing dependence on COVID-19 alone. GSK represents an important pipeline challenger as it advances next-generation mRNA influenza and pandemic-preparedness programs. Arcturus Therapeutics is differentiated through its self-amplifying mRNA platform, while CSL strengthens commercialization and geographic reach through KOSTAIVE. Daiichi Sankyo maintains a strategically important regional position through DAICHIRONA and domestic mRNA capabilities in Japan. Overall, competition is shifting from first-generation COVID-19 vaccines toward multi-indication portfolios, combination respiratory vaccines, lower-dose RNA technologies, improved manufacturing economics and differentiated delivery platforms, which will determine future leadership.
Target Opportunity Profile (TOP)
To compete effectively in the evolving mRNA vaccine landscape, next-generation products must demonstrate a differentiated Target Opportunity Profile beyond established commercial benchmarks such as COMIRNATY, SPIKEVAX, MRESVIA, MNEXSPIKE and MFLUSIVA. Future leaders will need to deliver meaningful differentiation across efficacy, durability of protection, safety and reactogenicity, dose efficiency, antigen breadth, age-group coverage, storage stability and administration convenience. High-value products should provide consistent protection against circulating strains, sustain immune responses for longer periods and reduce dependence on frequent boosting while maintaining scalable and cost-efficient manufacturing.
The strongest opportunities are expected across seasonal and pandemic influenza, combination respiratory vaccines, CMV, EBV, norovirus, HIV, tuberculosis, malaria and therapeutic oncology. Competitive differentiation will increasingly depend on self-amplifying RNA, advanced LNP delivery, multivalent antigen design, thermostable formulations and combination-vaccine platforms. Products capable of delivering lower RNA doses, improved tolerability, broader immune coverage and rapid adaptation to emerging pathogens will be best positioned to challenge established mRNA franchises and capture long-term clinical and commercial value.
Target Opportunity Profile (TOP) - Competitive Attributes
| Dimension | Desired Profile for Emerging Therapies | Rationale |
| Safety |
| mRNA vaccines may require recurrent administration, particularly for respiratory diseases. Improved tolerability can strengthen vaccine acceptance, adherence and competitive positioning across broader populations. |
| Efficacy |
| Approved vaccines establish increasingly high efficacy benchmarks. Emerging products must demonstrate meaningful clinical differentiation rather than technological novelty alone. |
| Durability |
| Waning immunity remains an important limitation in several respiratory vaccine categories. Longer protection could improve convenience, uptake and overall cost effectiveness. |
| Antigen Breadth |
| Rapid viral evolution and antigenic diversity can reduce vaccine effectiveness. Broader antigen coverage can provide greater resilience against future strain changes. |
| Dose Efficiency |
| Lower doses can reduce manufacturing requirements, improve production capacity and potentially decrease reactogenicity and cost per dose. |
| Thermostability |
| Improved stability can simplify distribution, reduce logistics costs and strengthen access across emerging and resource-constrained markets. |
Unmet Needs & Market Dynamics
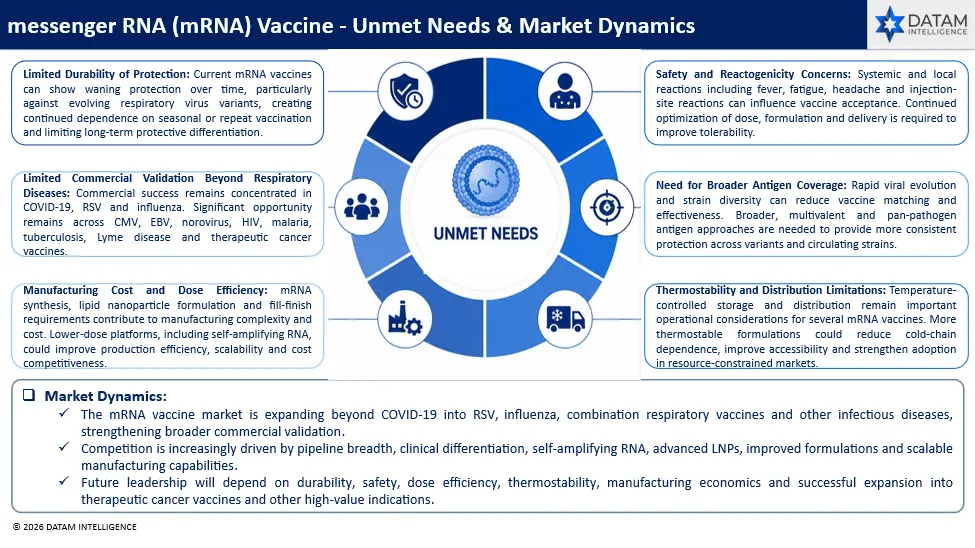
The mRNA vaccine market is transitioning from COVID-19 dependence toward a broader multi-indication platform spanning RSV, seasonal influenza, combination respiratory vaccines and other infectious diseases. Competitive intensity is increasing as Moderna, Pfizer/BioNTech and emerging developers differentiate through pipeline breadth, clinical performance, self-amplifying RNA, advanced LNP systems and scalable manufacturing. Commercial validation beyond COVID-19 is strengthening confidence in the platform’s long-term potential. Future leadership will depend on durability of protection, safety, dose efficiency, thermostability and manufacturing economics. Therapeutic cancer vaccines also represent an important long-term growth opportunity, particularly through personalized neoantigen and off-the-shelf mRNA approaches.
Strategic Summary
The mRNA vaccine landscape is progressing from a COVID-19-centric market toward a broader multi-indication vaccine and therapeutic platform spanning RSV, seasonal and pandemic influenza, combination respiratory vaccines, CMV, EBV, norovirus and oncology. Competitive leadership is currently concentrated among companies with commercially validated products, scalable manufacturing and broad clinical pipelines. Moderna and Pfizer/BioNTech remain key strategic leaders, while emerging developers are differentiating through self-amplifying RNA, improved LNP delivery, lower-dose formulations and next-generation antigen design.
Future competition will increasingly depend on durability of protection, safety and reactogenicity, antigen breadth, dose efficiency, thermostability, manufacturing economics and combination-vaccine capability. High-value opportunities are expected in indications where current prevention remains limited or where mRNA can offer faster development and broader immune coverage. Companies capable of translating a single RNA platform across multiple diseases, while maintaining clinical differentiation and cost-efficient manufacturing, will be best positioned to capture long-term strategic and commercial value.
Why Buy Our Messenger RNA (mRNA) Vaccine Competitive Intelligence Report?
Identify Where Competition Is Intensifying
Understand the evolving mRNA vaccine landscape across COVID-19, RSV, seasonal and pandemic influenza, combination respiratory vaccines, CMV, EBV, norovirus and therapeutic oncology, while tracking approved products, late-stage candidates and emerging RNA platforms competing for future market leadership.
Prioritize the Most Attractive Indications
Assess high-value opportunities across respiratory infections, latent viral diseases, pandemic preparedness and cancer vaccines, identifying indications with strong unmet need, limited commercial competition and meaningful potential for mRNA-based differentiation.
Benchmark Leading Companies and Platforms
Compare Moderna, Pfizer/BioNTech, GSK, Arcturus and other developers across pipeline breadth, clinical stage, mRNA technology, delivery systems, regulatory progress, manufacturing capabilities and commercial readiness.
Evaluate Product and Clinical Differentiation
Benchmark approved and pipeline vaccines across efficacy, durability, safety, reactogenicity, dose efficiency, antigen breadth, storage requirements and administration convenience to identify competitive advantages and development gaps.
Track Next-Generation mRNA Innovation
Monitor advances in self-amplifying RNA, improved LNP delivery, multivalent antigen design, thermostable formulations and combination vaccines that could disrupt established mRNA platforms.
Anticipate Upcoming Competitive Catalysts
Track Phase II and Phase III readouts, regulatory submissions, approvals, label expansions, commercial launches and strategic partnerships that could materially change competitive positioning.
Identify White-Space Opportunities
Evaluate underserved opportunities across CMV, EBV, norovirus, HIV, tuberculosis, malaria, pandemic influenza and therapeutic oncology, where successful clinical validation could create substantial long-term value.
Support Strategic Decision-Making
Leverage integrated competitive intelligence covering approved products, clinical pipelines, company strategies, technology benchmarking, commercial performance and market dynamics to support portfolio prioritization, partnership evaluation and long-term growth strategy.
