


The U.S. and EU biosimilars landscape is entering a more mature and strategically competitive phase, driven by expanding approvals, accelerating loss of exclusivity across major biologics and increasing pressure on healthcare systems to reduce biologic treatment costs. Competition is strongest across established molecules such as adalimumab, ustekinumab, aflibercept, denosumab, rituximab and ranibizumab, while the next development wave is shifting toward high-value biologics including pembrolizumab, nivolumab, daratumumab, ocrelizumab and secukinumab.
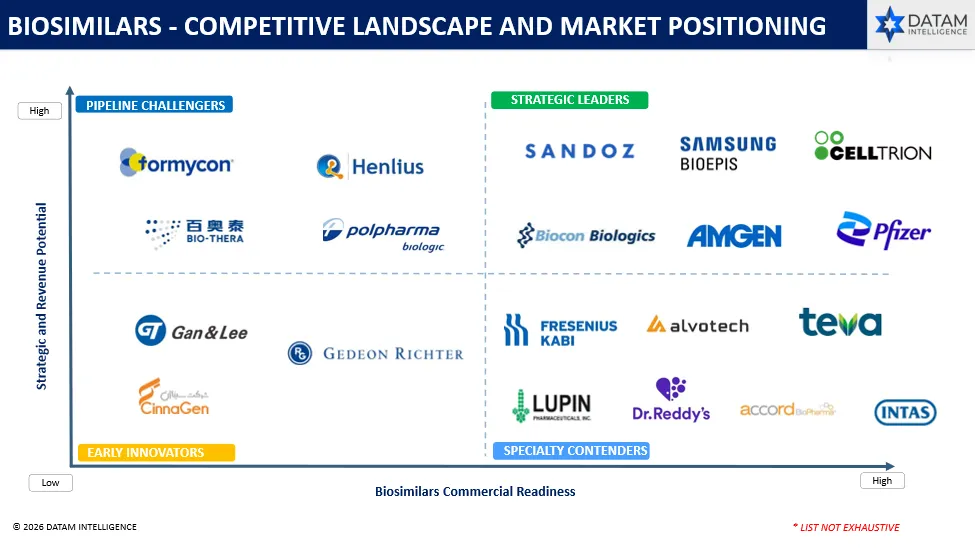
Competitive leadership is increasingly determined by more than regulatory approval. Launch timing, manufacturing scale, supply reliability, pricing flexibility, payer access, tender participation and commercialization partnerships are becoming critical differentiators. Sandoz, Samsung Bioepis, Celltrion, Amgen, Biocon Biologics and Pfizer remain strongly positioned, while Formycon, Henlius, Bio-Thera and Polpharma Biologics are building relevance through next-generation pipelines.
The U.S. remains more dependent on payer contracting, formulary access and interchangeability dynamics, whereas EU uptake is shaped by national tenders, switching policies and procurement structures. Future leadership will favor developers that enter early, target less-crowded high-value molecules and combine regulatory execution with scalable manufacturing and strong U.S. and EU market-access capabilities.
Key Highlights
- The U.S. and EU biosimilars market is moving into a more mature competitive phase, with competition increasingly concentrated around high-value molecules such as adalimumab, ustekinumab, aflibercept, denosumab, rituximab and ranibizumab.
- U.S. regulatory momentum remains strong, with 89 FDA-approved biosimilars through July 2026, compared with 81 approvals across 20 reference products at the end of 2025, expanding competition across oncology, immunology, ophthalmology, diabetes and supportive care.
- The EU remains the more mature biosimilar environment, supported by a regulatory pathway operating since 2006; competitive success increasingly depends on national tender access, switching policies, procurement structures and reliable supply rather than regulatory approval alone.
- The next competitive wave is shifting toward blockbuster biologics approaching loss of exclusivity, particularly Keytruda, Opdivo, Darzalex and Repatha, creating important opportunities through the late 2020s and early 2030s.
- Pembrolizumab is emerging as one of the most crowded future biosimilar opportunities, while nivolumab, daratumumab, ocrelizumab and secukinumab are also attracting significant development activity; several programs have already progressed to Phase III.
- Sandoz, Samsung Bioepis, Celltrion, Amgen, Biocon Biologics and Pfizer form the strategic leadership cluster, supported by broader approved portfolios, commercialization capabilities and continued pipeline expansion. Formycon, Henlius, Bio-Thera and Polpharma Biologics are strengthening their positions through next-generation pipelines.
- Commercial differentiation is moving beyond approval toward launch execution, pricing, manufacturing scalability and market access. U.S. success is increasingly linked to payer contracting, formulary positioning and interchangeability, while EU uptake remains more dependent on tenders, procurement and national switching frameworks.
- Future leadership will favor developers capable of combining early market entry, scalable manufacturing, competitive cost structures and strong U.S./EU commercialization infrastructure, particularly in high-value molecules with lower pipe
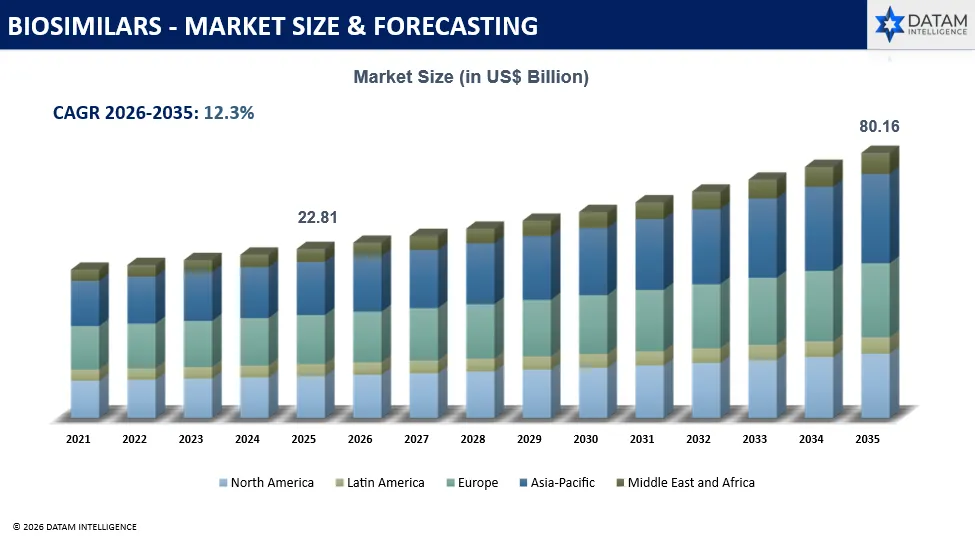
- The report projects the global biosimilars market from US$22.81 billion in 2025 to US$80.16 billion by 2035, at a 12.3% CAGR, reinforcing the long-term commercial opportunity created by expanding approvals and biologic loss of exclusivity.
Biosimilars Market Overview
The biosimilars market is becoming increasingly competitive across the U.S. and EU as patent expiries of major biologic therapies create opportunities for lower-cost alternatives. Market activity is expanding across oncology, immunology, ophthalmology, endocrinology and supportive care, supported by growing regulatory approvals and broader physician acceptance. Competition is increasingly influenced by launch timing, pricing strategies, interchangeability, payer access, tender participation and manufacturing scale. Leading biosimilar developers are strengthening portfolios through internal development, licensing and commercialization partnerships. Future market positioning will depend on portfolio breadth, regulatory execution, supply reliability, competitive pricing and successful penetration of high-value biologic categories.
U.S. and EU Regulatory Landscape
The U.S. and EU biosimilar regulatory environments are converging around a more science-led, analytics-first development model, but important commercial differences remain. In the U.S., biosimilars are approved through the 351(k) pathway under the BPCI Act, with FDA increasingly emphasizing comparative analytical assessment and reducing reliance on large comparative efficacy studies where scientifically justified. FDA’s 2025–2026 guidance updates also signal further streamlining of clinical development and pharmacokinetic requirements, potentially lowering development cost and shortening timelines.
The EU remains the more mature regulatory environment, with biosimilars approved since 2006 through a stepwise comparability framework focused on quality, biological activity, safety and efficacy. EMA has also adopted a tailored clinical approach intended to reduce unnecessary clinical data requirements. EU-approved biosimilars are considered scientifically interchangeable with reference products, although pharmacy-level substitution and procurement decisions remain country-specific.
From a competitive perspective, regulatory advantage is shifting toward developers with strong analytical platforms, efficient CMC execution, early FDA/EMA engagement and launch strategies aligned with practical patent-expiry windows.
Approved Biosimilars Landscape
The approved biosimilars landscape in the U.S. and EU is expanding rapidly across oncology, immunology, ophthalmology, diabetes and supportive care. In the U.S., FDA approvals continue to broaden competition around major reference biologics such as Rituxan, Novolog, Lucentis, Simponi, Neulasta, Lantus and Prolia, with new approvals continuing through July 2026. U.S. competition is increasingly shaped by interchangeability, payer access, formulary positioning and commercial launch timing.
The EU represents a more mature biosimilar environment, having approved its first biosimilar in 2006. EMA’s regulatory framework supports biosimilars that demonstrate high similarity to reference medicines in structure, biological activity, efficacy, safety and immunogenicity. Competition is well established across cancer, diabetes and autoimmune diseases, while national tendering, substitution policies and procurement systems strongly influence uptake. Overall, both markets are moving toward broader biosimilar availability, stronger price competition and increasing portfolio diversification among developers.
FDA-Approved Biosimilars in the U.S.
The U.S. biosimilars market has transitioned from an early-stage regulatory framework into a broad and increasingly competitive biologics landscape. Since the FDA approved Zarxio (filgrastim-sndz) as the first U.S. biosimilar in March 2015, the approval base has expanded steadily across oncology, immunology, ophthalmology, diabetes and supportive care. By the end of 2025, the FDA had approved 81 biosimilars across 20 reference products, establishing a significantly broader competitive set around several high-value biologics. During 2026, additional approvals through July increased the cumulative total to 89 FDA-approved biosimilars. Recent approvals include products referencing Rituxan, Novolog, Lucentis, Simponi, Neulasta, Lantus and Prolia. From a competitive intelligence perspective, the market is moving beyond approval volume alone, with future differentiation increasingly determined by commercial launch execution, interchangeability, payer access, formulary positioning, pricing strategy and the ability to secure meaningful share against both reference biologics and established biosimilar competitors.
| Biosimilar | Approval Date | Reference Product | Modality | Company | Therapeutic Area |
Zimrixby (rituximab-cdxx) | July, 2026 | Rituxan (rituximab) | Monoclonal Antibody | Dr. Reddy's Laboratories SA | Oncology and Immunology |
Garzulys (insulin aspart-fsan) | July, 2026 | Novolog (insulin aspart) | Rapid-Acting Insulin Analogue | Emerge Bioscience Pte. Ltd. | Diabetes |
Ranluspec (ranibizumab-hkdz) | June, 2026 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Lupin Limited | Ophthalmology |
Immgolis and Immgolis Intri (golimumab-sldi) | May, 2026 | Simponi and Simponi Aria (golimumab) | Monoclonal Antibody | Accord BioPharma Inc. | Immunology |
Ennumo (pegfilgrastim-pccg) | May, 2026 | Neulasta (pegfilgrastim) | Recombinant Growth Factor | Accord BioPharma Inc. | Oncology Supportive Care |
Langlara (insulin glargine-aldy) | April, 2026 | Lantus (insulin glargine) | Long-Acting Insulin Analogue | Sunshine Lake Pharma Co., Ltd. | Diabetes |
Ponlimsi (denosumab-adet) | March, 2026 | Prolia (denosumab) | Monoclonal Antibody | Teva Pharmaceuticals, Inc. | Osteoporosis and Bone Health |
| Filkri (filgrastim-laha) | January, 2026 | Neupogen (filgrastim) | Recombinant Growth Factor | Accord BioPharma Inc. | Oncology Supportive Care |
Boncresa and Oziltus (denosumab-mobz) | December, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Amneal Pharmaceuticals LLC | Bone Health and Oncology |
Nufymco (ranibizumab-leyk) | December, 2025 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Zydus Lifesciences Global FZE | Ophthalmology |
Armlupeg (pegfilgrastim-unne) | November, 2025 | Neulasta (pegfilgrastim) | Recombinant Growth Factor | Lupin Limited | Oncology Supportive Care |
Poherdy (pertuzumab-dpzb) | November, 2025 | Perjeta (pertuzumab) | Monoclonal Antibody | Shanghai Henlius Biotech, Inc. | Oncology |
Osvyrti and Jubereq (denosumab-desu) | October, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Accord BioPharma Inc. | Bone Health and Oncology |
Eydenzelt (aflibercept-boav) | October, 2025 | Eylea (aflibercept) | Recombinant Fusion Protein | Celltrion, Inc. | Ophthalmology |
Enoby and Xtrenbo (denosumab-qbde) | September, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Hikma Pharmaceuticals USA Inc. | Bone Health and Oncology |
Aukelso and Bosaya (denosumab-kyqq) | September, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Biocon Biologics Inc. | Bone Health and Oncology |
Bildyos and Bilprevda (denosumab-nxxp) | August, 2025 | Prolia and Xgeva (denosumab) | Monoclonal Antibody | Shanghai Henlius Biotech, Inc. | Bone Health and Oncology |
Kirsty (insulin aspart-xjhz) | July, 2025 | Novolog (insulin aspart) | Rapid-Acting Insulin Analogue | Biocon Biologics Inc. | Diabetes |
Starjemza (ustekinumab-hmny) | May, 2025 | Stelara (ustekinumab) | Monoclonal Antibody | Bio-Thera Solutions, Ltd. | Immunology |
Jobevne (bevacizumab-nwgd) | April, 2025 | Avastin (bevacizumab) | Monoclonal Antibody | Biocon Biologics Inc. | Oncology |
LIST NOT EXHAUSTIVE
EMA-Approved Biosimilars in the EU
The EU remains the most established biosimilar regulatory market, having authorised Omnitrope (somatropin) as the first biosimilar on 12 April 2006. Since then, the approved landscape has broadened significantly across immunology, oncology, diabetes, ophthalmology, endocrinology and supportive care. By the end of 2025, EMA reported that the CHMP had assessed 181 biosimilar applications and approved 165 biosimilars, including a record 41 biosimilar approvals during 2025 alone. During January–July 2026, the CHMP issued 11 additional positive opinions for biosimilars, taking the cumulative CHMP-approved/recommended base to approximately 176 biosimilars. From a competitive intelligence perspective, EU market success increasingly depends on timely regulatory execution, national tender access, pricing competitiveness, switching policies, supply reliability and the ability to secure volume across country-specific procurement systems, rather than approval alone.
| Biosimilar | Approval Date | Reference Product | Modality | Company | Therapeutic Area |
| Vislyfa (ranibizumab) | July, 2026 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Lupin Europe GmbH | Ophthalmology |
| Rexatilux (ranibizumab) | June, 2026 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Intas Third Party Sales 2005 S.L. | Ophthalmology |
| Bysumlog (insulin lispro) | May, 2026 | Humalog (insulin lispro) | Rapid-Acting Insulin Analogue | Gan & Lee Pharmaceuticals Europe GmbH | Diabetes |
| Dazparda (insulin aspart) | April, 2026 | NovoRapid (insulin aspart) | Rapid-Acting Insulin Analogue | Gan & Lee Pharmaceuticals Europe GmbH | Diabetes = |
| Zandoriah (teriparatide) | April, 2026 | Forsteo (teriparatide) | Recombinant Parathyroid Hormone Analogue | CinnaGen Co Unipessoal LDA | Osteoporosis / Bone Health |
| Tuyory (tocilizumab) | April, 2026 | RoActemra (tocilizumab) | Monoclonal Antibody | Gedeon Richter Plc. | Immunology |
| Fubelv (etanercept) | April, 2026 | Enbrel (etanercept) | TNF-Receptor Fusion Protein | Biosimilar Collaborations Ireland Limited | Immunology |
| Gotenfia (golimumab) | February, 2026 | Simponi (golimumab) | Monoclonal Antibody | STADA Arzneimittel AG | Immunology |
| Ranluspec (ranibizumab) | February, 2026 | Lucentis (ranibizumab) | Monoclonal Antibody Fragment | Lupin Europe GmbH | Ophthalmology |
| Ondibta (insulin glargine) | January, 2026 | Lantus (insulin glargine) | Long-Acting Insulin Analogue | Sandoz GmbH | Diabetes |
LIST NOT EXHAUSTIVE
Reference Biologics and Loss of Exclusivity Analysis
Loss of exclusivity among major reference biologics is creating successive biosimilar entry opportunities across the U.S. and EU. Mature molecules such as Humira, Stelara, Eylea and Prolia/Xgeva have already entered active biosimilar competition, while Keytruda, Opdivo, Darzalex and Repatha represent important next-wave opportunities through the late 2020s and early 2030s. Competitive timing differs between the U.S. and EU due to patent structures, supplementary protection certificates, litigation settlements and secondary formulation or method-of-use patents. From a strategic perspective, early identification of realistic launch windows is critical for prioritizing development programs, regulatory filings, manufacturing readiness and commercialization investments.Loss of exclusivity among major reference biologics is creating successive biosimilar entry opportunities across the U.S. and EU. Mature molecules such as Humira, Stelara, Eylea and Prolia/Xgeva have already entered active biosimilar competition, while Keytruda, Opdivo, Darzalex and Repatha represent important next-wave opportunities through the late 2020s and early 2030s. Competitive timing differs between the U.S. and EU due to patent structures, supplementary protection certificates, litigation settlements and secondary formulation or method-of-use patents. From a strategic perspective, early identification of realistic launch windows is critical for prioritizing development programs, regulatory filings, manufacturing readiness and commercialization investments.
| Reference Biologic | Molecule | Therapeutic Area | U.S. Loss of Exclusivity / Key Milestone | EU Loss of Exclusivity / Key Milestone |
| Humira | Adalimumab | Immunology | Core patent expired 2016; biosimilar entry began January 2023 | Core protection expired October 2018; biosimilar entry began October 2018 |
| Stelara | Ustekinumab | Immunology | Core patent expired September 2023; biosimilar launches began January 2025 | Core protection expired during 2024; biosimilar competition began in 2024 |
| Eylea | Aflibercept | Ophthalmology | Core patent expired June 2023; secondary patents extend into 2027-2032 | Core protection extended to around May 2025; secondary patents remain beyond 2025 |
| Prolia / Xgeva | Denosumab | Bone Health and Oncology | Core protection reached expiry in 2025; biosimilar competition expanded during 2025-2026 | Core protection reached expiry in 2025 across major EU markets |
| Keytruda | Pembrolizumab | Oncology | Key composition protection expected to expire around 2028-2029 | Key protection expected to extend to around 2031 |
| Opdivo | Nivolumab | Oncology | Major exclusivity expected to extend to around 2028 | Major exclusivity expected to extend to around 2030 |
| Darzalex | Daratumumab | Oncology | Key patent protection expected to expire around 2029 | Key protection expected to extend into approximately 2031-2032 |
| Repatha | Evolocumab | Cardiovascular | Core antibody protection extends to around 2029, with secondary patents beyond 2030 | Core protection extends to around 2028, with secondary protection into 2032-2033 |
Pipeline Analysis
The U.S. and EU biosimilar pipeline is increasingly shifting toward the next wave of high-value biologics, with late-stage development concentrated in oncology, immunology and neurology. Pembrolizumab is emerging as one of the most competitive future opportunities, with multiple developers progressing active programs, while nivolumab, daratumumab, ocrelizumab and secukinumab are also attracting significant pipeline activity. Celltrion currently lists Phase III programs for daratumumab, pembrolizumab, ocrelizumab and secukinumab, highlighting growing competitive intensity across upcoming loss-of-exclusivity opportunities. Formycon has also completed clinical development of its pembrolizumab biosimilar FYB206, indicating that selected developers are moving closer to regulatory submission and commercialization readiness. Strategically, future competitive advantage will depend on development speed, regulatory execution, manufacturing scalability, partnership strength and launch timing relative to practical U.S. and EU exclusivity windows.
| Company / Biosimilar Candidate | Reference Biologic | Molecule | Current Phase / Status | Therapeutic Area |
| Samsung Bioepis - SB27 | Keytruda | Pembrolizumab | Phase III | Oncology |
| Amgen - ABP 234 | Keytruda | Pembrolizumab | Phase III | Oncology |
| Celltrion - CT-P51 | Keytruda | Pembrolizumab | Phase III | Oncology |
| Amgen - ABP 206 | Opdivo | Nivolumab | Phase III | Oncology |
| Celltrion - CT-P44 | Darzalex | Daratumumab | Phase III | Oncology / Multiple Myeloma |
| Celltrion - CT-P53 | Ocrevus | Ocrelizumab | Phase III | Neurology / Multiple Sclerosis |
| Amgen - ABP 692 | Ocrevus | Ocrelizumab | Phase III | Neurology / Multiple Sclerosis |
| Celltrion - CT-P55 | Cosentyx | Secukinumab | Phase III | Immunology / Dermatology |
| Amgen - ABP 938 8 mg | Eylea HD | Aflibercept 8 mg | Phase III | Ophthalmology |
| Bio-Thera - BAT2306 | Cosentyx | Secukinumab | Phase III-Completed | Immunology / Dermatology |
| Bio-Thera - BAT3306 | Keytruda | Pembrolizumab | Phase I | Oncology |
| Henlius - HLX17 | Keytruda | Pembrolizumab | Phase I | Oncology |
| Henlius - HLX18 | Opdivo | Nivolumab | Phase I | Oncology |
| Henlius - HLX15-SC | Darzalex / Darzalex Faspro | Daratumumab | Phase I | Oncology / Multiple Myeloma |
Market Size & Forecasting
The global Biosimilars market stood at US$22.81 billion in 2025 and is expected to reach US$80.16 billion by 2035, growing with a CAGR of 12.3% during the forecast period 2026-2035.
Competitive Landscape and Market Positioning
The U.S. and EU biosimilars competitive landscape reflects a clear separation between established commercial leaders, pipeline-focused challengers and molecule-specific contenders. Sandoz, Samsung Bioepis, Celltrion, Amgen, Biocon Biologics and Pfizer occupy the strategic leadership cluster, supported by broader approved portfolios, established commercialization capabilities and continued pipeline expansion. Formycon, Henlius Biotech, Bio-Thera Solutions and Polpharma Biologics represent pipeline challengers, with development programs targeting high-value next-generation biologics but comparatively lower commercial penetration across the two regions. Fresenius Kabi, Alvotech, Teva, Lupin, Dr. Reddy’s Laboratories, Accord BioPharma and Intas Pharmaceuticals are positioned as specialty contenders, reflecting focused portfolios and selective commercialization strengths. Meanwhile, Gan & Lee Pharmaceuticals, Gedeon Richter, CinnaGen and Sunshine Lake Pharma represent emerging developers. Overall, competitive advantage is increasingly shaped by portfolio breadth, regulatory execution, pipeline timing, manufacturing scalability, pricing capability and access to established U.S. and EU commercialization channels.
Target Opportunity Profile (TOP)
To compete effectively in the U.S. and EU biosimilars landscape, next-generation biosimilar programs must demonstrate a strong Target Opportunity Profile across regulatory, clinical, manufacturing and commercial dimensions. Competitive differentiation will increasingly depend on selecting high-value reference biologics with clear loss-of-exclusivity windows, manageable development complexity, limited pipeline crowding and meaningful pricing headroom. High-potential candidates should demonstrate robust analytical similarity, comparable pharmacokinetics, efficacy, safety and immunogenicity while supporting efficient FDA and EMA regulatory pathways. Greater commercial value will come from programs that combine scalable manufacturing, reliable supply, competitive cost structures and the ability to launch close to practical patent expiry. In the U.S., interchangeability potential, payer access and formulary positioning can materially strengthen uptake, while in the EU, tender competitiveness, country-level switching practices and procurement access remain critical. Biosimilars combining early market entry, strong commercialization partnerships, manufacturing readiness and attractive reference-product economics will be best positioned to capture sustainable share.
Target Opportunity Profile (TOP) - Competitive Attributes
| Dimension | Desired Profile for Emerging Therapies | Rationale |
Analytical and Clinical Similarity |
| Strong similarity evidence is fundamental for FDA and EMA approval and supports confidence in clinical performance relative to the reference biologic. |
| Safety and Immunogenicity |
| Comparable safety and immunogenicity are essential for regulatory acceptance, physician confidence and switching from established reference biologics. |
Regulatory and Loss of Exclusivity Readiness |
| Early regulatory preparation and clear patent positioning can improve first-wave entry and reduce the risk of delayed commercialization. |
Manufacturing and Supply Scalability |
| Biosimilars operate under significant price pressure, making manufacturing efficiency, quality consistency and uninterrupted supply critical competitive advantages. |
Commercial and Market Access Potential |
| Commercial success depends on converting approval into uptake through competitive pricing, payer contracting, tender access and favorable positioning against other biosimilars. |
Unmet Needs & Market Dynamics
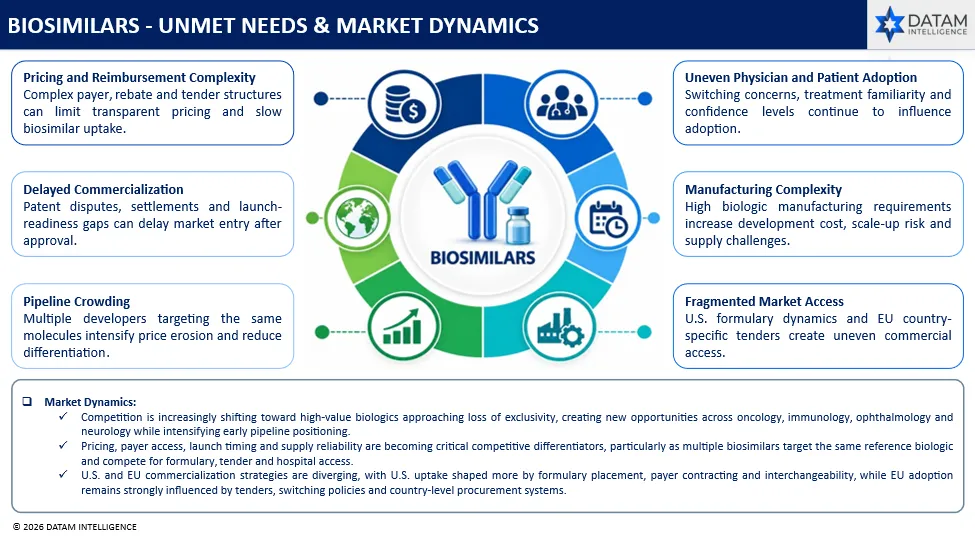
The U.S. and EU biosimilars landscape continues to face several structural and commercial challenges despite the steady expansion of approved products. Pricing and reimbursement complexity can limit the expected cost advantage of biosimilars, particularly where rebate structures, formulary positioning and tender mechanisms influence realized pricing. Physician and patient adoption also remains uneven, with switching confidence, treatment familiarity and therapeutic-area-specific acceptance affecting uptake. Commercialization can be delayed by patent disputes, settlement agreements, launch sequencing and market-access requirements even after regulatory approval. Manufacturing remains another critical challenge because biosimilars require highly consistent biologic production, scalable capacity and reliable supply. At the same time, pipeline crowding is intensifying as multiple developers target the same high-value reference products, increasing price erosion and reducing differentiation. Future competitive success will increasingly depend on early launch timing, disciplined pricing, payer and tender access, manufacturing reliability and strong commercialization partnerships across both regions.
Strategic Summary
Biosimilars are becoming an increasingly important component of the U.S. and EU biologics landscape as major reference products lose exclusivity and healthcare systems seek broader access to high-cost biologic therapies. Competitive intensity is rising across oncology, immunology, ophthalmology, diabetes and supportive care, while commercial performance remains highly dependent on regulatory timing, payer access, tender participation, physician acceptance and reliable supply.
Competitive differentiation is increasingly shifting beyond regulatory approval toward launch execution, pricing strategy, interchangeability, contracting strength and portfolio breadth. In the U.S., formulary positioning, payer negotiations and substitution dynamics play a central role in uptake, while the EU remains strongly influenced by national tenders, switching policies and procurement frameworks. Companies able to combine competitive pricing with dependable supply and strong market-access execution are better positioned to capture sustainable share.
The pipeline is progressively moving toward next-generation high-value biologics approaching loss of exclusivity, including pembrolizumab, nivolumab, daratumumab, ocrelizumab and secukinumab. Growing pipeline crowding is increasing pressure on developers to select attractive molecules early, accelerate regulatory development and establish manufacturing readiness ahead of practical launch windows. Partnerships and licensing agreements are also becoming more important for extending geographic reach and strengthening commercialization capabilities.
Future leadership will depend on combining early market entry, scalable manufacturing, regulatory execution, competitive cost structures and strong U.S. and EU commercialization infrastructure. Biosimilar developers that target less-crowded, high-value reference products and secure payer, formulary and tender access are likely to achieve the strongest long-term competitive positioning.
Why Buy Our Biosimilars Competitive Intelligence Report?
The biosimilars market is entering a more competitive and commercially complex phase across the U.S. and EU, driven by accelerating biologic loss of exclusivity, expanding regulatory approvals, increasing pipeline crowding and stronger pricing pressure. Companies require clear intelligence on approved portfolios, launch timing, patent exposure, pipeline depth, interchangeability, payer access, tender participation and commercialization strategies. Our report translates these evolving dynamics into actionable portfolio, market-entry and competitive strategies.
Identify where competition is intensifying
Understand which reference biologics are attracting the highest number of approved and pipeline biosimilars and where competitive crowding is likely to accelerate.
Prioritize high-value molecule opportunities
Assess reference biologics based on loss of exclusivity, commercial value, development complexity, pipeline density and potential U.S. and EU launch windows.
Benchmark competitor positioning
Compare leading and emerging biosimilar developers across approved products, pipeline strength, manufacturing capabilities, partnerships and commercial readiness.
Evaluate pricing and market access dynamics
Track U.S. payer and formulary strategies alongside EU tendering, procurement and switching policies that influence biosimilar uptake.
Assess pipeline and launch readiness
Identify Phase III, Phase II and Phase I programs approaching commercialization and evaluate their potential impact on future competitive intensity.
Support portfolio and market-entry strategy
Use competitive intelligence to guide molecule selection, development prioritization, licensing, partnerships, manufacturing investment and U.S. and EU commercialization planning.
