


U.S. Data Center Motors and Drives Market Size
The U.S. Data Center Motors and Drives Market was valued at US$ 0.86 Billion in 2025 and is projected to reach US$ 2.08 Billion by 2031, growing at 15.91% annually. Cooling systems account for much of the demand. Large facilities use motors to run chilled-water pumps, cooling towers, fans and compressors. Variable-frequency drives adjust the equipment speed as operating loads change.
New AI data centers need larger cooling plants and more liquid-cooling equipment. Existing facilities are also replacing older fan and pump systems to reduce electricity use. Buyers place a high value on motor reliability, drive compatibility and service support because cooling interruptions can affect server operations.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2025-2031) |
| US$ 0.86 Billion | US$ 2.08 Billion | 15.91% |
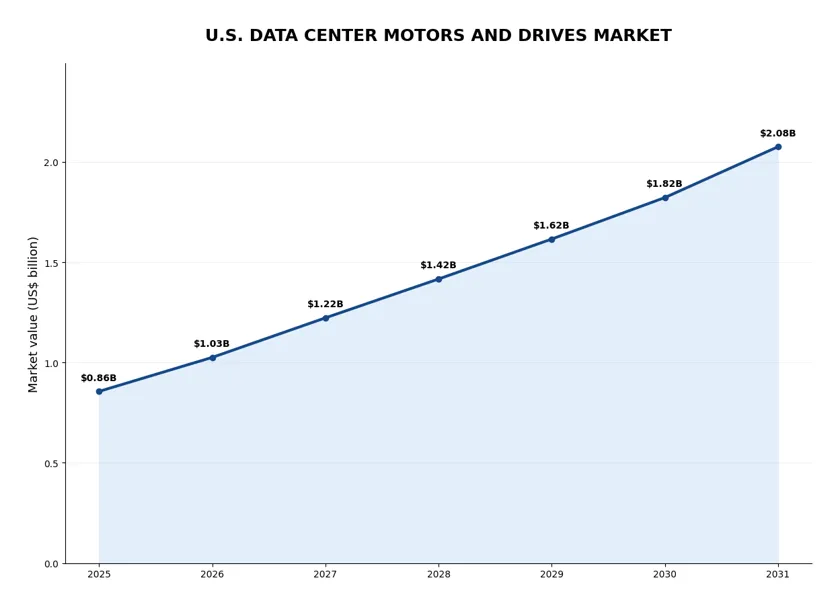
• Market value is expected to increase from US$ 0.86 Billion in 2025 to US$ 2.08 Billion in 2031.
• Cooling towers, chilled-water pumps and air handling systems are key sources of motor and drive demand.
• Liquid cooling adds demand for smaller, precision-controlled pumps in coolant distribution units.
• Variable-frequency drives help operators match fan and pump output to changing heat loads.
• Hyperscale projects increasingly order motors and drives through chiller, pump and cooling-system suppliers.
• Spare parts and local service matter because cooling equipment needs to operate continuously.
U.S. Data Center Motors and Drives Industry Trends and Strategic Insights
• AI server racks generate more heat. Operators are buying larger chilled-water systems and adding liquid-cooling loops where needed.
• High-efficiency motors are gaining attention for continuous-duty pumps and fans. Electricity savings depend on the duty cycle and equipment settings.
• Drive specifications increasingly require building management system integration, simple commissioning and remote diagnostics.
• Standard motor and drive packages help data center builders repeat cooling designs across multiple campuses.
U.S. Data Center Motors and Drives Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 0.86 Billion |
| 2031 Projected Market Size | US$ 2.08 Billion |
| CAGR (2025-2031) | 15.91% |
| By Product Type | Electric motors and variable-frequency drives for data center cooling |
| By Motor Type | Induction, synchronous reluctance, permanent magnet and integrated pump motors |
| By Drive Type | HVAC drives, pump drives, low-voltage VFDs and selected medium-voltage drives |
| By Power Rating | Fractional-horsepower CDU pumps through large chiller plant motors |
| By Application | Chillers, chilled-water pumps, cooling towers, CRAC/CRAH fans and liquid-cooling systems |
| By Industry | Hyperscale, colocation, enterprise and edge data centers |
| By Sales Channel | OEMs, mechanical contractors, electrical contractors and system integrators |
| By Project Type | New data centers, cooling plant expansions, modernization and replacement |
| Competitive Landscape | 10 motor and drive suppliers relevant to U.S. data centers |
Coverage: United States. Products include electric motors for cooling pumps, fans, compressors and cooling distribution systems plus low- and medium-voltage variable-frequency drives. The study covers hyperscale, colocation, enterprise and edge data centers. Motors and drives supplied as part of HVAC and cooling equipment are included.
U.S. Data Center Motors and Drives White Space & Investment Opportunities
• Cooling plant orders: work with chiller and pump OEMs supplying new hyperscale campuses.
• Liquid cooling: supply compact motors and precision-controlled drives for coolant distribution units.
• Retrofit work: replace fixed-speed fan and pump motors with efficient motor and drive packages where the load profile supports savings.
Suppliers that can ship standard packages quickly and provide local service have an advantage. Early involvement with cooling-system designers can help secure repeat orders.
Driver Impact Analysis
New hyperscale campuses need central cooling plants, air handling equipment and backup cooling capacity. Each project can require multiple pump motors, cooling tower motors and variable-speed drives.
| DRIVER | INTENSITY | AFFECTED EQUIPMENT | COMMERCIAL IMPACT |
| New data center construction | High | Pump, fan and compressor motors | New equipment packages for large cooling plants |
| AI cooling requirements | High | Liquid cooling pumps and precision drives | More coolant circulation and heat-rejection equipment |
| Cooling energy efficiency | High | Variable-frequency drives and efficient motors | Retrofit and specification opportunities |
| Cooling system redundancy | Medium | Duty and standby motor-drive packages | More equipment per facility and service contracts |
AI computing creates higher heat loads at many sites. This is increasing interest in liquid cooling, higher-capacity chillers and better fan and pump control.
Restraint Impact Analysis
Large cooling packages can face long equipment lead times. Drive panels, motors and chillers need to arrive in the correct sequence to meet commissioning dates.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Lead times for cooling equipment | Cooling plant construction | High | Early ordering needed for large motor and drive packages |
| Complex controls integration | Cooling automation | High | More testing before start-up |
| Cost pressure | Retrofits and smaller facilities | Medium | Longer approval process |
| Service coverage | Critical cooling components | Medium | Preference for suppliers with local support |
Cooling systems often have strict redundancy and controls requirements. Drive replacements may need electrical testing, control-system changes and scheduled shutdowns.
U.S. Data Center Motors and Drives Competitive Landscape
Competition comes from motor manufacturers, drive specialists and suppliers with strong relationships among U.S. cooling-equipment OEMs. Buyers compare efficiency, lead times, controls support and repair services.
| COMPANY | INDUSTRIAL MOTORS AND DRIVES POSITIONING |
| ABB | Cooling tower motors, SynRM motors and ACH HVAC drives |
| Nidec Motor Corporation | U.S. MOTORS cooling motors, integrated drive systems and Nidec Drives |
| Siemens | SIMOTICS motors, SINAMICS drives and building controls |
| Danfoss Drives | VLT HVAC and low-harmonic drives for cooling pumps and fans |
| WEG | High-efficiency motors and variable-speed drive packages |
| Schneider Electric | Altivar drives and data center cooling controls |
| Rockwell Automation | PowerFlex drives and automation integration |
| Yaskawa America | AC drives and industrial motor control |
| Mitsubishi Electric Automation | Variable-frequency drives and building equipment controls |
| Regal Rexnord | Marathon and Leeson motors for HVAC and pumping applications |
ABB, Nidec and WEG supply motors for fans and pumps. Danfoss, Siemens and Schneider Electric supply drives used in cooling plants. Rockwell Automation, Yaskawa and Mitsubishi Electric also serve building and industrial control applications.
U.S. Data Center Motors and Drives Recent Developments
• March 31, 2026: Nidec presented new cooling motors and drives for Data Center World. Its range included the SynRA Unimount motor, ID300 integrated motor and drive and Commander AC drives.
• April 2026: ABB showed cooling tower motors, direct-drive motors and ACH-series drives at Data Center World in Washington, D.C.
• April 28, 2026: ABB introduced a water-cooled permanent magnet motor range rated up to 5 MW for applications that need high power in a smaller space.
• June 8, 2026: Nidec announced a 300 kW in-rack coolant distribution unit prototype that uses pumps for liquid cooling.
• September 21, 2026: ABB launched its Infinitus direct-current portfolio for AI data centers. The range includes cooling options with variable-speed drives and motors.
• September 23, 2026: Schneider Electric introduced a new Motivair coolant distribution unit with integrated pumps and heat exchangers. U.S. pre-orders are planned for 2027.


























































