


U.S. Power Transformer Market Size and Overview
The U.S. Power Transformer Market is valued at US$ 8.94 billion in 2025 and is forecast to reach US$ 10.82 billion by 2031, growing at 3.22% annually. The quantified series corresponds to the workbook category LV/MV Transformers; higher-voltage and large-power transformer applications are assessed qualitatively in the market scope.
Demand is shaped by utility transformer replacements, distribution capacity additions, electrification of commercial and industrial sites, and new substation connections for data centers. Supplier qualification increasingly depends on temperature-rise performance, guaranteed losses, delivery slots, testing capacity and service readiness.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 8.94 Billion | US$ 10.82 Billion | 3.22% |
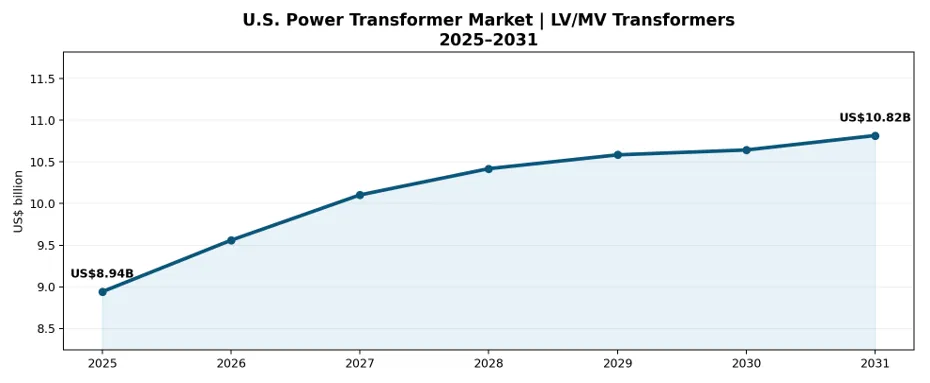
U.S. LV/MV transformer demand rises from US$ 8.94 billion in 2025 to US$ 10.82 billion in 2031.
The quantified product category grows 3.22% annually on the 2025–2031 endpoints.
Replacement of aging distribution transformers supports recurring demand from investor-owned and municipal utilities.
Large-load interconnections and AI-data-center substations increase project interest in medium-power and large-power transformer capability.
Lead times, test-bay availability and domestic content requirements are increasingly decisive in the sourcing process.
Low-loss designs, alternative dielectric fluids and digital transformer monitoring present premium product opportunities.
U.S. Power Transformer Industry Trends and Strategic Insights
Utility distribution replacement combines with grid hardening, voltage regulation and capacity reinforcement programs.
Data-center campuses increasingly require transformer capacity reservations early in electrical infrastructure design.
Expansion of U.S. transformer assembly, core, winding and test capacity is reshaping competitive positions.
Utilities increasingly evaluate life-cycle losses, thermally upgraded insulation, fire safety and condition monitoring.
U.S. Power Transformer Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 8.94 Billion |
| 2031 Projected Market Size | US$ 10.82 Billion |
| CAGR (2026–2031) | 3.22% |
| By Transformer Type | Distribution; medium-power; large-power; replacement/retrofit |
| By End-Use Industry | Utilities; industrial; commercial; data centers; transportation; renewables |
| By Voltage Rating | LV; MV; HV; EHV |
| By Cooling and Insulation | Oil-immersed; ester-filled; dry-type; alternative insulation |
| By Component | Core; windings; bushings; tap changers; cooling; monitoring |
| By Phase and Installation | Single-phase; three-phase; pad/pole/ground-mounted; substations |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, market developments and partnerships |
| Market Data Coverage | Cable-family and cable-subtype market values, 2025–2031 (US$ million); segmentation, competition and market dynamics |
Coverage: United States. Quantitative revenue series: LV/MV Transformers. Broader analysis addresses distribution, medium-power and large power transformers, cooling/insulation, voltage classes, utility and industrial end uses. Large-power-only revenue is not separately quantified in the supplied category.
U.S. Power Transformer Market White Space & Investment Opportunities
Grid asset replacement: serve long-term utility purchasing programs with standardized pad-mounted and pole-mounted equipment.
Critical-load substations: secure engineering-to-order business for AI data centers, advanced manufacturing and large industrial sites.
Domestic capacity and aftermarket: expand U.S. winding, core, final assembly, test-bay and transformer monitoring services.
Suppliers can capture opportunities through early utility framework qualification, multi-year manufacturing-slot agreements, higher-efficiency product upgrades, field service and strategically located domestic production.
Driver Impact Analysis
Aging distribution equipment, severe-weather resilience initiatives and rising peak demand create demand for replacement and capacity expansion. Growth in data centers raises transformer procurement urgency, particularly where interconnection dates are fixed.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Utility replacement and grid resilience | High | Distribution asset renewal | Utility framework approvals and delivery slots |
| AI data-center electrification | High | Medium-power substation demand | Prequalify larger units and EPC solutions |
| Renewable interconnections | Medium-High | Generator step-up and distribution demand | Advance grid-compliant product designs |
| Domestic production investment | Medium-High | Supplier lead-time differentiation | Expand test bays and manufacturing |
Federal and state infrastructure programs, renewable generation, manufacturing investments and resilience upgrades encourage transformer standardization, better asset visibility and higher-efficiency designs.
Restraint Impact Analysis
Electrical-steel and copper inputs, insulation component supply, bushings and test-bay constraints can extend lead times. Long qualification cycles make it difficult for new manufacturers to secure approved utility-vendor status.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Core steel and copper inputs | High | Long-cycle pricing pressure | Index key input materials |
| Factory and test capacity | High | Equipment delivery delays | Reserve slots early |
| Utility supplier qualification | Medium-High | Slow new-vendor adoption | Strengthen certifications and pilot programs |
| Interconnection/project schedules | Medium | Deferred equipment release | Stage engineering and manufacturing commitments |
Grid-access delays, project reprioritization, evolving efficiency specifications and transformer transport constraints increase costs and create uncertainty for large units and remote-site deployment.
U.S. Power Transformer Market Competitive Landscape
Competition spans global transmission-transformer manufacturers, U.S. distribution-transformer specialists and integrated grid suppliers. Vendors differentiate through capacity, service quality, factory test performance and lead-time reliability.
| COMPANY | U.S. POWER TRANSFORMER POSITIONING |
| Hitachi Energy | Large power transformers; new U.S. factories in Virginia and Mississippi. |
| GE Vernova / Prolec GE | Distribution and power transformers; North American Prolec GE manufacturing. |
| Siemens Energy | Large power transformers and transmission-grid applications. |
| Hyundai Electric America | Power transformers for utilities, industry and large infrastructure. |
| Virginia Transformer | U.S. engineered-to-order power and distribution transformers. |
| Howard Industries | Distribution transformers for utility grid networks. |
| Eaton | Distribution, industrial and dry-type transformer portfolios. |
| Mitsubishi Electric Power Products | Utility power equipment and large power transformers. |
| Waukesha (SPX Transformer Solutions) | Power transformer manufacturing, rebuild and services. |
| ERMCO | Pad-mounted and pole-mounted distribution transformers. |
Competitive priorities include utility approvals, domestic production, low-loss designs, engineering support, delivery certainty and the ability to provide spare units and monitoring across the installed fleet.
U.S. Power Transformer Market Recent Developments
June 29, 2026 — Hitachi Energy broke ground on its US$457 million large power transformer facility in South Boston, Virginia; the project is expected to create approximately 825 jobs.
September 15, 2026 — Hitachi Energy announced a US$528 million transformer factory in Gallman, Mississippi, designed to more than double area production capacity and create over 700 jobs.
March 10, 2026 — GE Vernova announced a US$200 million large-power-transformer facility in Vietnam to support global HVDC requirements; its investment plan also referenced expansion of Prolec GE transformer capacity.
July 30, 2026 — GE Vernova announced a US$138 million expansion in Charleroi, Pennsylvania for transmission equipment including instrument transformers and high-voltage switching products.
2026 — Siemens Energy reported construction progress at its new Charlotte, North Carolina large power transformer production site as part of its U.S. manufacturing investment program.
October 2026 — GE Vernova was identified as a critical electrical equipment provider in Venture Global’s announced plans for gas-powered AI infrastructure in Louisiana.


























































