


U.S. Industrial Motors Market Size
The U.S. Industrial Motors Market was valued at US$ 4.26 Billion in 2025 and is expected to reach US$ 5.78 Billion in 2031, growing at 5.21% annually. Manufacturers are replacing aging motors in pumps, compressors, conveyors and other production equipment. New industrial facilities also need reliable motors for continuous operations.
Demand is strongest where motor failure disrupts production. Buyers are comparing purchase price with electricity use, maintenance needs and the cost of downtime. High-efficiency induction motors remain widely used, while permanent magnet and severe-duty models are gaining attention in selected applications.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2025-2031) |
| US$ 4.26 Billion | US$ 5.78 Billion | 5.21% |
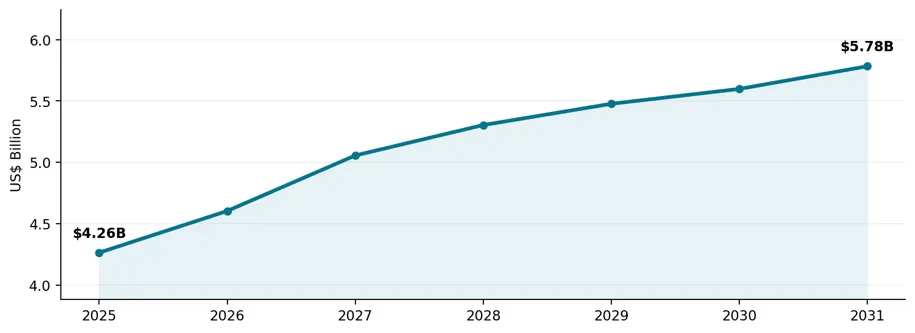
U.S. Industrial Motors Key Takeaways
U.S. industrial motor sales are forecast to rise from US$ 4.26 Billion in 2025 to US$ 5.78 Billion by 2031.
General-purpose AC motors account for much of replacement demand across factories and commercial process equipment.
Pumps, compressors, fans and conveyors remain major sources of motor purchases.
Higher motor efficiency standards are encouraging buyers to review older installed equipment.
Severe-duty and washdown motors are important for chemical, food processing and water treatment plants.
Local availability, motor repair and service support are important when equipment fails unexpectedly.
U.S. Industrial Motors Industry Trends and Strategic Insights
Companies are reviewing motor replacement plans ahead of the next U.S. efficiency requirements for certain industrial motors.
Motor users are looking at lifetime electricity costs, particularly for equipment that runs for long hours.
Plants increasingly want motor designs that fit existing mounting arrangements and avoid lengthy shutdowns.
Suppliers with local warehouses, repair shops and application support have an advantage in urgent replacement orders.
U.S. Industrial Motors Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 4.26 Billion |
| 2031 Projected Market Size | US$ 5.78 Billion |
| CAGR (2025-2031) | 5.21% |
| By Product Type | General-purpose AC induction motors |
| By Motor Type | Severe-duty and washdown motors |
| By Drive Type | Permanent magnet and synchronous motors |
| By Power Rating | Low-voltage industrial motors |
| By Application | Medium-voltage industrial motors |
| By Industry | Pumps, fans, compressors and conveyors |
| By Sales Channel | Manufacturing, water treatment, energy and chemicals |
| By Project Type | Motor replacement and new equipment installations |
| Competitive Landscape | 10 leading motor manufacturers serving U.S. industrial customers |
Coverage: United States. The market covers industrial AC and DC electric motors used in manufacturing, utilities and industrial facilities. Product groups include general-purpose induction motors, severe-duty motors, permanent magnet motors, synchronous motors and application-specific designs. The report covers low-voltage and medium-voltage products, retrofit demand and new installations.
U.S. Industrial Motors Market White Space & Investment Opportunities
Energy-efficient motor replacements for pumps, fans and conveyors at older manufacturing sites.
Severe-duty and corrosion-resistant products for chemical plants, water utilities and food production.
Motor repair, replacement stock and maintenance contracts for plants with demanding uptime targets.
Motor suppliers can strengthen customer relationships through reliable lead times and practical application advice. Fast replacements and support during shutdowns are often as important as the motor specification.
Driver Impact Analysis
New manufacturing capacity creates demand for motors on production equipment and supporting utilities. Expansion projects typically buy motors alongside pumps, compressors and material-handling systems.
| DRIVER | INTENSITY | AFFECTED EQUIPMENT | COMMERCIAL IMPACT |
| Plant capacity expansion | High | Industrial motors and drive packages | New installation orders across U.S. manufacturing |
| Motor efficiency upgrades | High | High-efficiency AC motors | Replacement work across existing factories |
| Variable-speed operation | High | motors for pumps and fans | Retrofit orders tied to electricity savings |
| Water and process investment | Medium | Pump motors and process motors | Utility and infrastructure project opportunities |
Electricity costs and new efficiency requirements encourage the replacement of older motors. Continuous-duty machines offer the clearest case for higher-efficiency products.
Restraint Impact Analysis
Capital budgets can delay motor replacement if the existing unit still works. Plants tend to schedule larger upgrades during planned maintenance shutdowns.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Capital budget delays | Replacement and retrofit projects | High | Longer purchase decisions for upgrades |
| Installation downtime | Continuous production processes | High | Require planned shutdown windows |
| Controls compatibility | Old motors and PLC systems | Medium | Additional engineering and testing |
| Supply and service gaps | Motor stock and drive spare parts | Medium | Prioritize local inventory and support |
Supply constraints and long lead times affect special-purpose and larger motors. Buyers may also need engineering checks before replacing older units with higher-efficiency designs.
U.S. Industrial Motors Market Competitive Landscape
The U.S. industrial motor market includes large international manufacturers and established American brands. Competition is based on efficiency, reliable delivery, product range, replacement compatibility and service coverage.
| COMPANY | INDUSTRIAL MOTORS POSITIONING |
| ABB | Baldor-Reliance general-purpose, SP4 and severe-duty industrial motors |
| WEG | W22 industrial induction motors, high-efficiency and special-purpose motors |
| Nidec Motor Corporation | U.S. MOTORS commercial and industrial motors, pump and cooling tower motors |
| Regal Rexnord | Industrial motor brands and power transmission systems |
| Siemens | SIMOTICS industrial motor portfolio |
| Toshiba International | Medium-voltage and large industrial motors |
| TECO-Westinghouse | Large motors and industrial AC induction motor systems |
| Mitsubishi Electric | Industrial AC and high-efficiency electric motors |
| Franklin Electric | Motors and pumping systems for water and industrial uses |
| Marathon Electric | Industrial and commercial motors for general and severe-duty applications |
ABB, WEG, Nidec and Regal Rexnord have broad industrial motor portfolios. Siemens, Toshiba and other suppliers serve larger or specialized applications. Product availability and local service can determine supplier choice.
U.S. Industrial Motors Market Recent Developments
January 2026: Nidec U.S. MOTORS introduced new cooling tower motors and premium-efficiency pump motors at the AHR Expo. The products target cooling and industrial pumping applications.
June 2, 2026: ABB announced a new Baldor-Reliance severe-duty motor platform ahead of its EASA launch in Orlando.
June 18, 2026: ABB said its Baldor-Reliance SP4 HVAC motor won a 2026 Plant Engineering Product of the Year award.
July 2026: WEG introduced the W22 Prime induction motor, with IE4 and IE5 efficiency options.
August 11, 2026: ABB introduced the SD200 SP4 severe-duty motor for customers preparing for the 2027 U.S. efficiency requirements.
- 2026: Motor suppliers continued to promote direct-replacement options and local support for industrial users replacing older equipment


























































