


U.S. Industrial Drives Market Size
The U.S. Industrial Drives Market was valued at US$ 3.16 Billion in 2025 and is expected to reach US$ 4.39 Billion in 2031, with annual growth of 5.65%. Demand comes from factories replacing older variable-frequency drives and adding speed control to pumps, fans, conveyors and compressors.
Industrial buyers use drives to control motor speed, reduce electricity use and improve equipment operation. Many projects involve replacing old units with compatible models. New equipment installations also need drives that connect easily with plant control systems.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2025-2031) |
| US$ 3.16 Billion | US$ 4.39 Billion | 5.65% |
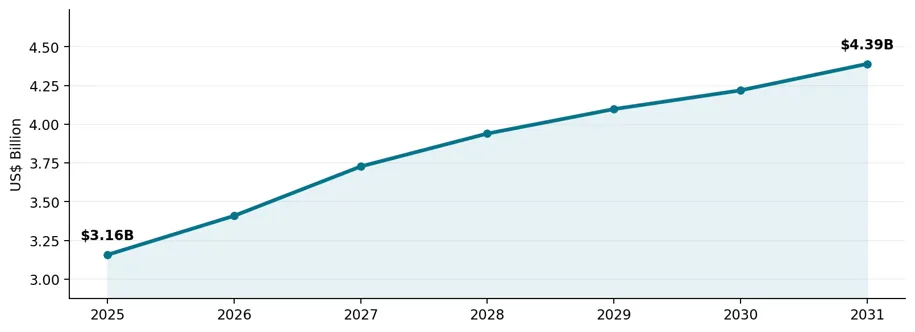
• U.S. industrial drive sales are expected to increase from US$ 3.16 Billion in 2025 to US$ 4.39 Billion by 2031.
• Variable-frequency AC drives serve the largest range of applications, particularly pumps, fans and material-handling equipment.
• Demand for medium-voltage drives is linked to larger compressors, pumps and other high-power industrial equipment.
• Water and wastewater sites are important customers because many pumps run for long periods.
• Buyers increasingly ask for low-harmonic options and better protection for equipment in demanding sites.
• Lead times, local service and compatibility with existing controls often influence buying decisions.
U.S. Industrial Drives Industry Trends and Strategic Insights
• Plant owners are replacing older VFDs when spare parts become difficult to obtain or reliability starts to fall.
• Water utilities, manufacturing plants and process operators are adding speed control to reduce energy use.
• Industrial customers want simpler commissioning and easy links to existing automation systems.
• U.S.-made drives may be preferred for some publicly funded infrastructure projects with domestic-content requirements.
U.S. Industrial Drives Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 3.16 Billion |
| 2031 Projected Market Size | US$ 4.39 Billion |
| CAGR (2025-2031) | 5.65% |
| By Product Type | Low-voltage variable-frequency drives |
| By Motor Type | Medium-voltage AC drives |
| By Drive Type | General-purpose and application-specific drives |
| By Power Rating | Low-harmonic and regenerative drives |
| By Application | Packaged drives and bypass systems |
| By Industry | Pumps, fans, conveyors and compressors |
| By Sales Channel | Manufacturing, water utilities, energy and chemicals |
| By Project Type | New equipment installations and drive retrofits |
| Competitive Landscape | 10 leading motor and drive manufacturers serving U.S. industrial customers |
Coverage: United States. The market includes industrial variable-frequency drives and other electronic motor-speed control drives used in factories, water utilities and process industries. The study covers low-voltage and medium-voltage drives, general-purpose and application-specific systems, replacement demand and new equipment installations.
U.S. Industrial Drives Market White Space & Investment Opportunities
• Drive replacement programs for aging pumps, fans and conveyors in industrial facilities.
• Low-harmonic drives and bypass packages for water treatment plants and critical process equipment.
• Local drive service, commissioning and repair support for facilities with limited maintenance staff.
Suppliers can win more projects by offering replacement guidance and short delivery times. Buyers want drives that fit the existing electrical installation and work with their plant controls.
Driver Impact Analysis
New industrial facilities need drives for pumps, material handling, ventilation and process equipment. Demand also comes from retrofits where plant owners add variable-speed operation to fixed-speed machines.
| DRIVER | INTENSITY | AFFECTED EQUIPMENT | COMMERCIAL IMPACT |
| Factory automation and modernization | New plants and production upgrades require speed control for rotating equipment. | Industrial drives and drive packages | New installation orders across U.S. manufacturing |
| Electricity savings | Variable speed operation reduces energy use in suitable pump and fan applications. | High-efficiency AC drives | Replacement work across existing factories |
| Water and wastewater investment | Treatment plants replace pumps and update control systems. | VFDs for pumps and fans | Retrofit orders tied to electricity savings |
| Old drive replacement | Limited spare parts and recurring faults increase replacement purchases. | Pump drives and process drives | Utility and infrastructure project opportunities |
Higher electricity costs encourage drive upgrades on equipment with variable flow or load. Energy savings depend on the application and operating profile.
Restraint Impact Analysis
Plants may delay drive upgrades when older equipment still works. Electrical installation and control-system changes can also add cost.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Capital spending pressure | Plants delay replacing working drives when project budgets are tight. | High | Longer purchase decisions for upgrades |
| Installation and commissioning | Control changes and shutdown time increase upgrade costs. | High | Require planned shutdown windows |
| Power quality concerns | Harmonics and electrical compatibility need engineering review. | Medium | Additional engineering and testing |
| Long lead times | Specialist medium-voltage drives may face longer delivery schedules. | Medium | Prioritize local inventory and support |
Power quality, heat and difficult site conditions can limit drive selection. Some larger drives have longer delivery times and need specialist commissioning.
U.S. Industrial Drives Market Competitive Landscape
The U.S. industrial drives market includes global drive manufacturers and automation suppliers. Buyers compare product reliability, software compatibility, support coverage and delivery schedules.
| COMPANY | INDUSTRIAL DRIVES POSITIONING |
| ABB | ACS, ACH and ACQ drives for industry, water treatment and building systems |
| Rockwell Automation | PowerFlex low-voltage and medium-voltage drives |
| Siemens | SINAMICS industrial AC drive portfolio |
| Danfoss | VLT and iC7 drives for industry and infrastructure |
| Schneider Electric | Altivar variable-speed drives and packaged drive systems |
| Yaskawa America | GA-series and industrial AC drives |
| WEG | CFW variable-frequency drive portfolio |
| Mitsubishi Electric Automation | FR-series variable-frequency drives |
| Eaton | PowerXL drive products and motor control systems |
| Toshiba International | AS3 and medium-voltage industrial adjustable-speed drives |
ABB, Rockwell Automation, Siemens and Danfoss supply broad drive ranges. Schneider Electric, Yaskawa, WEG and other suppliers serve factory automation, water treatment and HVAC-related applications.
U.S. Industrial Drives Market Recent Developments
• January 31, 2026: ABB introduced ACH580 vertical bypass drives for HVAC systems. The design helps protect drive equipment in mechanical rooms and outdoor installations.
• March 4, 2026: ABB added 315 kW and 355 kW wall-mounted drives to its ACS580, ACQ580 and ACH580 product ranges.
• April 16, 2026: Danfoss announced IEC 62443 security certification for its VLT drives.
• July 2, 2026: Danfoss announced new features for its iC7-Automation variable-frequency drive range.
• July 21, 2026: ABB said its drives made in New Berlin, Wisconsin received NEMA Make It American product certification.
• July 22, 2026: ABB launched the ACQ580-3P low-harmonic drive package for water and wastewater facilities.


























































