


Taiwan Data Center Cables & Wires Market Size and Overview
The Taiwan Data Center Cables & Wires Market is valued at US$ 452.40 million in 2025 and is projected to reach US$ 1046.30 million by 2031, registering 15.00% annualized growth. Demand covers high-density optical fiber, structured copper connectivity, data-center power cables, control wiring and specialty cable assemblies installed at cloud, AI, colocation and enterprise facilities.
Taipei and New Taipei serve enterprise and interconnection demand, while Taoyuan, Hsinchu, Taichung and Kaohsiung attract high-performance computing, cloud infrastructure and electronics-industry deployments. AI compute density increases fiber counts per rack, low-loss connections and redundant electrical feeds. The pace of investment depends on power availability, phased facility construction, cable installation readiness and resilience requirements.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 452.40 Million | US$ 1046.30 Million | 15.00% |
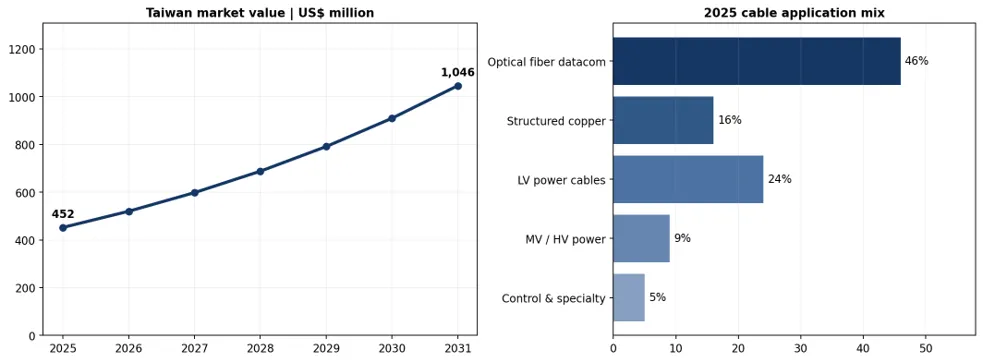
Taiwan Data Center Cables & Wires Market grows from US$ 452.40 million in 2025 to US$ 1046.30 million in 2031, adding US$ 593.90 million in annual demand.
The 15.00% annualized growth outlook reflects expansion of cloud capacity, AI computing systems and bandwidth-intensive networking.
Taipei–New Taipei and Taoyuan remain major commercial clusters, with opportunities also in Hsinchu, Taichung and Kaohsiung.
High-density optical-fiber trunks and factory-terminated assemblies help manage higher port counts and shorten data-hall fit-outs.
Redundant LV/MV feeder systems, fire-rated cables and dual-route designs remain essential to resilient data-center electrical infrastructure.
Early identification of power-ready sites, cloud tenant commitments and project contractors improves the accuracy of supplier opportunity targeting.
Taiwan Data Center Cables & Wires Industry Trends and Strategic Insights
AI accelerators and dense computing clusters increase optical interconnect intensity, fiber trunk concentration and technical testing demands.
Data-hall redundancy and energy-efficiency requirements favor qualified power cables, safe routing and documented installation performance.
Modular server-hall deployment encourages factory-terminated fiber solutions and pre-engineered cable assemblies.
Grid access, transformer delivery, local specialist contractors and site resilience shape design freezes and cable delivery timing.
Taiwan Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 452.40 Million |
| 2031 Projected Market Size | US$ 1046.30 Million |
| CAGR (2026–2031) | 15.00% |
| Geographic Coverage | Taiwan: Taipei, New Taipei, Taoyuan, Hsinchu, Taichung, Kaohsiung and other data-center hubs |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
Taiwan-wide coverage includes hyperscale, colocation, cloud, AI computing and enterprise data centers. The market is segmented by cable type, facility function, transmission medium, voltage class, insulation and sheathing materials, installation configuration and data-center end use. Key geographic hubs include Taipei, New Taipei, Taoyuan, Hsinchu, Taichung and Kaohsiung.
Taiwan Data Center Cables & Wires Market White Space & Investment Opportunities
AI-scale optical connectivity: dense trunk fiber, low-loss assemblies and short-reach high-bandwidth links offer premium opportunities around AI data-hall fit-outs.
Critical electrical distribution: upgraded LV/MV feeders, fire-safety cabling and redundancy routes create demand for certified power-cable suppliers.
Installation productivity: prefabricated cable harnesses, preterminated fibers and local inventory can reduce commissioning delays.
Cable manufacturers and integrators should prioritize funded phases associated with cloud and AI campus builds and establish early links with EPC/MEP contractors, connectivity system designers and local network integrators. Telecom interconnection routes and retrofits create recurring upgrade opportunities.
Driver Impact Analysis
AI-cloud expansion and growth in dense GPU infrastructure raise requirements for fiber counts, cable performance and faster cable deployment. Early product qualification supports higher-value optical connections and campus interconnect demand.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Cloud and AI campus expansion | High-density fiber trunks and assemblies | High | Qualify cabling early with cloud and AI integrators. |
| Redundant facility electrical design | LV/MV feeders and controls | High | Engage power-system EPC contractors. |
| Interconnection density and upgrades | Low-loss optic cabling | High | Target cross-connects and facility retrofits. |
| Modular infrastructure procurement | Preterminated fiber and copper | Medium | Develop fast-turn assemblies and local stock. |
Redundant power paths, phased expansion of colocation campuses and energy-critical data-hall upgrades drive demand for certified LV/MV cabling, control cables and emergency infrastructure wiring.
Restraint Impact Analysis
Electrical-grid connection constraints, permitting, energy requirements and changes in server deployment timing may defer cable orders. Procurement risk is reduced by following confirmed power availability and commissioning milestones.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Power connection and site approval delays | Timing of cable installation awards | High | Track approved site energization. |
| Fiber and copper input cost volatility | Tender costs and bid margins | High | Use project-aligned procurement. |
| Skilled installation and test capacity | Facility commissioning reliability | Medium | Partner with certified integrators. |
| Fire safety and electrical qualification | Available product shortlist | Medium | Maintain certifications and documentation. |
Volatility in fiber, copper and material costs plus fire-performance certification and skilled installation capacity can raise project costs. Imported premium connectivity competes with domestic cable production.
Taiwan Data Center Cables & Wires Market Competitive Landscape
Taiwanese cable manufacturers such as Walsin Lihwa, Ta Ya Electric Wire & Cable, Hua Eng Wire & Cable and Tai-I Electric Wire & Cable serve facility power distribution and industrial wiring. Corning, CommScope, Belden and Prysmian compete in optical and structured cable systems, while Legrand and Schneider Electric support integrated critical-infrastructure connectivity.
| COMPANY | TAIWAN DATA CENTER CABLES & WIRES POSITIONING |
| Walsin Lihwa | Taiwan power and telecommunications cable manufacturer supporting high-reliability electrical infrastructure. |
| Ta Ya Electric Wire & Cable | Taiwanese power and building-cable producer for mission-critical electrical distribution. |
| Hua Eng Wire & Cable | Domestic supplier of electrical wire and power-cable systems. |
| Tai-I Electric Wire & Cable | Taiwan wire and cable manufacturer for industrial and building applications. |
| Corning | Optical-fiber and high-density data-center connectivity products. |
| CommScope | Fiber and copper structured-cabling solutions for data halls and network interconnects. |
| Belden | Copper and optical cabling for mission-critical networks and facilities. |
| Prysmian | Optical fiber and power cables supporting data-center campus infrastructure. |
| Legrand | Copper/fiber data-center connectivity, racks and electrical distribution products. |
| Schneider Electric | Data-center electrical power distribution and connectivity infrastructure. |
Differentiation centers on low-loss optical performance, certified fire-safety construction, installation labor savings, delivery reliability, on-site engineering and qualified power-system integration. Local stocking and factory termination help suppliers execute short development windows.
Taiwan Data Center Cables & Wires Market Recent Developments
January 27, 2026 — Government investment update: Taiwan’s Executive Yuan confirmed that AWS is establishing data centers serving the Asia-Pacific region as part of growing U.S. corporate investment in Taiwan.
March 4, 2026 — Product launch: Prysmian introduced Sirocco Ultra high-density microduct optical cables using 160-micron fiber for digital networks and data centers.
March 11, 2026 — Technology licensing: Corning announced a US Conec PRIZM TMT optical-ferrule licensing collaboration to extend high-density AI data-center connectivity.
March 16, 2026 — Product portfolio launch: Corning announced multicore fiber, high-density micro-cable and 32-fiber MMC connector innovations for AI network installation.
March 17, 2026 — Taiwan-led product showcase: Foxconn unveiled details of its scalable modular data-center system and NVIDIA Vera Rubin NVL72 integration at GTC 2026.
June 15, 2026 — Strategic collaboration: Taiwan-based Foxconn and Schneider Electric announced collaboration to develop integrated, ready-to-deploy AI data-center infrastructure solutions.


























































