


Sub-Saharan Africa Data Center Cables & Wires Market Size and Overview
The Sub-Saharan Africa Data Center Cables & Wires Market was valued at US$ 21.89 million in 2025 and is projected to reach US$ 29.82 million by 2031, with 5.29% annualized growth. Quantified coverage comprises South Africa, Nigeria, Angola, Congo, Ethiopia, Ghana, Kenya and Tanzania. The market includes structured copper networking, optical-fiber trunks and interconnects, LV/MV power cables, control wiring and specialized cabling for data centers.
South Africa has the largest established carrier-neutral, cloud and colocation ecosystem in this coverage. Kenya is expanding East African interconnection and cloud hosting, while Nigeria is concentrating investment in Lagos data-center facilities. Ghana, Ethiopia, Angola, Congo and Tanzania present selective opportunities linked to connectivity, enterprise hosting and electrical-system modernization. Grid reliability, power cost and carrier density remain key location factors.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 21.89 Million | US$ 29.82 Million | 5.29% |
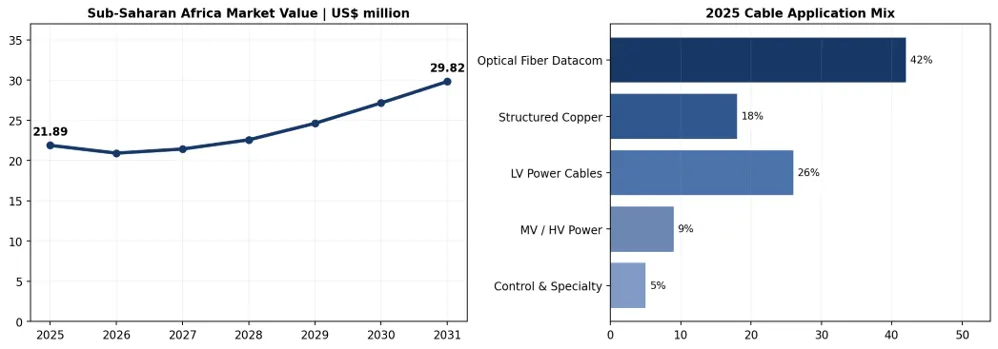
Market value rises from US$ 21.89 million in 2025 to US$ 29.82 million by 2031, an increase of US$ 7.93 million.
Annualized growth of 5.29% is supported by cloud connectivity, data-center upgrades and resilient electrical infrastructure.
South Africa is the most developed regional interconnection hub; Kenya and Nigeria represent important additional investment corridors.
High-density fiber and pre-terminated optical trunks support switching, storage, cross-connect and AI-ready network upgrades.
LV power feeders, A/B route segregation and robust low-smoke cables are key to power resilience and facility safety.
Eight markets are quantified: South Africa, Nigeria, Angola, Congo, Ethiopia, Ghana, Kenya and Tanzania.
Sub-Saharan Africa Data Center Cables & Wires Industry Trends and Strategic Insights
Colocation operators are expanding fiber-dense meet-me rooms, cloud on-ramps and multiple route connectivity.
Facilities require redundant electrical feeds, fire-compliant power cables and traceable testing of mission-critical installations.
Modular data-center construction increases demand for repeatable prefabricated cable assemblies and structured link packages.
Local grid access, skilled installers and carrier ecosystems determine achievable commissioning schedules.
Sub-Saharan Africa Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 21.89 Million |
| 2031 Projected Market Size | US$ 29.82 Million |
| CAGR (2026–2031) | 5.29% |
| Geographic Coverage | South Africa, Nigeria, Angola, Congo, Ethiopia, Ghana, Kenya and Tanzania (8 countries) |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
The report covers eight countries: South Africa, Nigeria, Angola, Congo, Ethiopia, Ghana, Kenya and Tanzania. Segmentation includes fiber-optic and structured copper cables, power feeders, control and specialty wires, conductor and transmission medium, voltage, installation type, insulation and end use. Other Sub-Saharan African markets are outside the quantified coverage.
Sub-Saharan Africa Data Center Cables & Wires Market White Space & Investment Opportunities
Optical infrastructure: Carrier-neutral growth in Johannesburg, Cape Town, Lagos and Nairobi drives demand for high-count fiber, optical cross-connect and rack-level links.
Resilient facility power: Redundant feeders and qualified fire-performance cables support new data halls and brownfield expansions.
Local supply services: Installer qualification, stocking, field testing and EPC relationships can unlock contracts for specialized cable providers.
South Africa offers a mature operator and interconnection ecosystem, while Kenya and Nigeria present important additional expansion corridors. Suppliers should follow commissioned versus planned MW, utility energization dates and approved-vendor programs rather than treat all announced projects as immediately addressable.
Driver Impact Analysis
Cloud adoption, fiber-rich carrier ecosystems and additional colocation capacity support demand for optical, structured copper and electrical power cabling. Growth is most visible around South African established campuses and emerging Nigerian and Kenyan network hubs.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Colocation and cloud capacity additions | Backbone fiber, structured cabling and dual power circuits | High | Engage campus operators and MEP firms at design stage. |
| AI-ready networking upgrades | Optical trunks and high-density interconnects | High | Offer pre-terminated scalable architectures. |
| Carrier-neutral ecosystem growth | Interconnection fiber and low-loss data links | Medium | Partner with network integrators and carriers. |
| Facility resilience upgrades | Fire-rated LV and controls cabling | Medium | Target brownfield retrofit cycles. |
Higher data throughput and rack density increase the need for low-loss optical trunks, carefully managed copper links and robust cabling around dual-feed power infrastructure. A qualified local installer and regional service presence can improve win rates.
Restraint Impact Analysis
Unreliable grid power, interconnection limits and generator dependence can constrain facility expansion. Project developers may stage campus builds until power and cooling requirements are secured, delaying cabling orders.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid power constraints | Construction timing and phased commissioning | High | Monitor confirmed utility energization. |
| Capital availability and project delays | Timing of cabling purchase orders | High | Distinguish committed capacity from announced pipeline. |
| Cross-border cable import cost | Lead times, price and margins | Medium | Build local fulfillment capability. |
| Technician and compliance gaps | Fiber commissioning and cable testing | Medium | Partner with certified installers. |
Imported fiber and copper costs, currency volatility, customs friction and a shortage of specialists in high-density networks can increase project costs. Cable vendors need verified product certificates, installation partners and delivery buffers.
Sub-Saharan Africa Data Center Cables & Wires Market Competitive Landscape
Competition includes African power-cable manufacturers and international fiber, structured cabling and data-center connectivity providers. Aberdare Cables, CBI-electric: african cables and Coleman Wires & Cables support electrical infrastructure, while Prysmian, Nexans, Corning, CommScope, Belden, Legrand and Schneider Electric provide networking and facility connectivity portfolios.
| COMPANY | Sub-Saharan Africa DATA CENTER CABLES & WIRES POSITIONING |
| Aberdare Cables | South African electrical cable manufacturer serving low- and medium-voltage facility power distribution. |
| CBI-electric: african cables | Regional power-cable producer for campus feeders and mission-critical electrical networks. |
| Coleman Wires & Cables | Nigerian producer of power and optical-fiber cables supporting national digital and power infrastructure. |
| Prysmian | Global optical-fiber and electrical cable supplier for digital-infrastructure facilities. |
| Nexans | Power and data-cabling supplier for high-performance electrical and telecom applications. |
| Corning | Optical-fiber and high-density data-center connectivity solutions supplier. |
| CommScope | Structured copper and fiber connectivity systems for colocation and hyperscale networks. |
| Belden | Network cabling and structured connectivity provider for critical facilities. |
| Legrand | Data-center rack connectivity and electrical cabling ecosystem supplier. |
| Schneider Electric | Data-center power distribution infrastructure and associated electrical connectivity provider. |
Suppliers compete on optical density, proven fire and electrical performance, cable route documentation, project stock availability and qualified commissioning. Joint engagement with data-center owners, MEP contractors and integrators can improve conversion.
Sub-Saharan Africa Data Center Cables & Wires Market Recent Developments
February 2026 — South Africa: Open Access Data Centres (OADC) agreed to acquire seven NTT DATA facilities across the country, consolidating enterprise and carrier-neutral capacity in a major regional data-center transaction.
March 2026 — Product launch: Prysmian introduced Sirocco Ultra high-density optical-fiber cabling for bandwidth-intensive digital infrastructure and compact installations.
April 28, 2026 — Regional market consolidation: A Balancing Act industry study reported that planned carrier-neutral data centers had fallen from 38 to 23, underscoring stricter project financing and operator selection.
May 28, 2026 — South Africa: NAPAfrica and ZANOG announced an interconnection initiative in Cape Town to strengthen connectivity across the growing regional digital ecosystem.
September 7, 2026 — Kenya: Digital Realty opened its 6.4 MW Nairobi Two (NBO2) facility and transitioned the iColo brand to Digital Realty in Kenya and Mozambique.
September 2026 — Kenya: NBO2 added a new Nairobi campus facility for carrier-neutral cloud and interconnection demand, expanding fiber-route and structured-cabling opportunities.


























































