Smart Meter Market Size and Overview
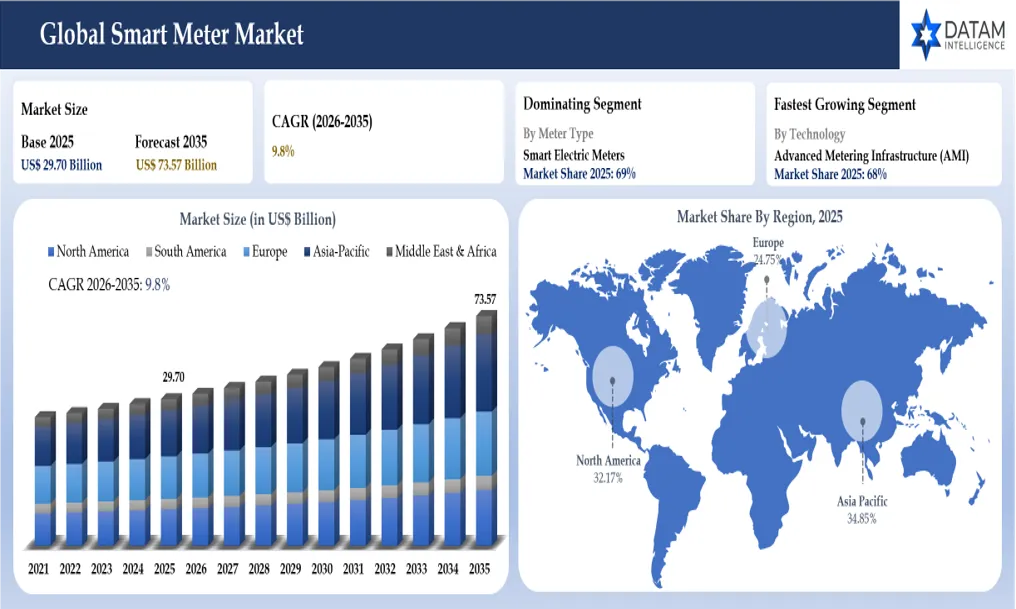
The global smart meter market reached US$ 29.70 billion in 2025 and is expected to reach US$ 73.57 billion by 2035, growing with a CAGR of 9.5% during the forecast period 2026-2035.
Apart from the general market growth, AMI has emerged as one of the most important drivers of demand as utilities progress from simple automatic meter reading towards two-way communications, remote meter management, outage detection and interval metering of energy use. The growing penetration of rooftop solar panels, battery storage, electric vehicles and other distributed energy resources is creating another need for bi-directional smart meters that can monitor variable flows of energy. The large scale deployment of smart meters is especially important in developing economies, where utilities are deploying smart metering to improve billing and minimize electricity theft.
Moreover, the growth of the market extends not only to the meter itself but to communication networks, meter data management, analytics, cybersecurity and remote asset management as well. Connectivity solutions such as NB-IoT and LTE-M and RF mesh network are becoming increasingly significant in connecting meter fleets that are dispersed geographically. Meanwhile, AI-enabled analytics have found applications in demand prediction, anomaly detection and prevention of energy theft. The transition to connected and intelligent metering solutions enabled by software is opening up new opportunities for technology vendors and AMI providers in the smart metering value chain.
Smart Meter Market Key Takeaways
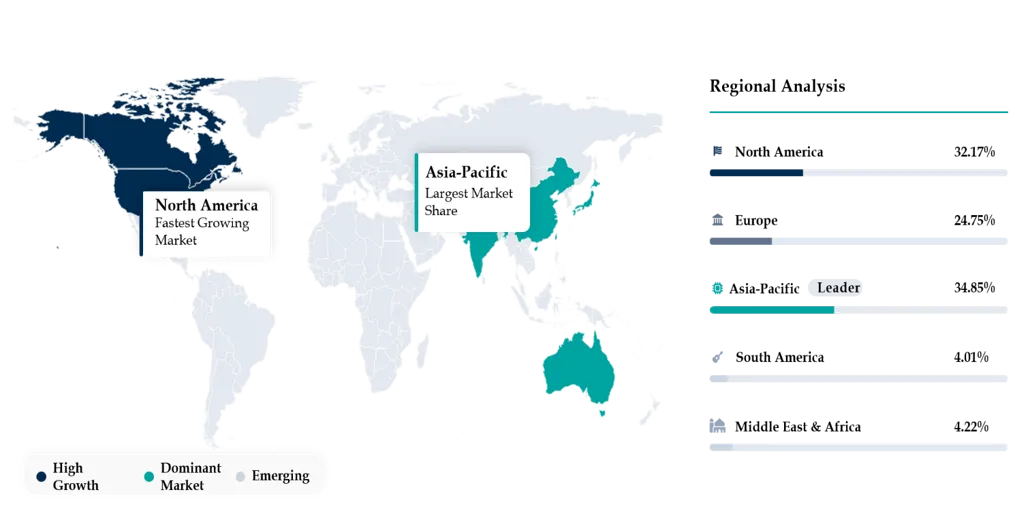
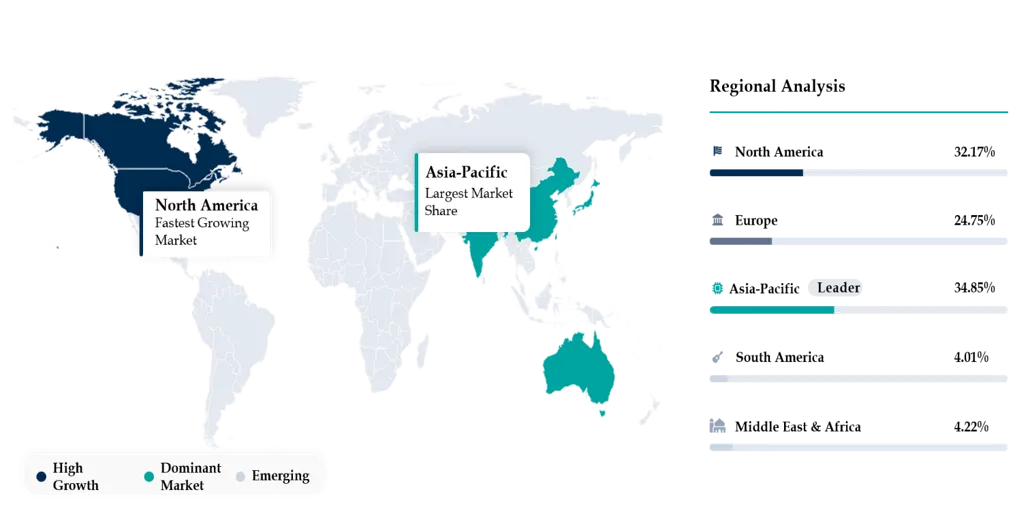
- Asia- Pacific holds the largest regional market share, supported by advanced grid infrastructure, large-scale smart grid investments and widespread deployment of advanced metering technologies.
- North America is the fastest-growing region, driven by government-led smart grid initiatives, rapid urbanization and expanding utility modernization programs.
- Smart electric meters account for more than one-third of the global market, owing to their widespread deployment in residential and commercial applications.
- Advanced Metering Infrastructure (AMI) is witnessing rapid adoption, enabling two-way communication, real-time monitoring and improved grid management.
- Rising investments in smart cities and digital utility infrastructure are accelerating global smart meter installations.
- Increasing demand for accurate billing, energy efficiency and real-time consumption monitoring continues to drive market expansion.
- Utilities are integrating AI, IoT, cloud computing and edge analytics to improve grid reliability and predictive maintenance.
- Government regulations promoting carbon reduction and energy conservation are encouraging large-scale smart meter deployment.
- Growing adoption of renewable energy sources is increasing demand for intelligent metering systems capable of managing distributed energy resources.
- Cybersecurity enhancements and advanced communication technologies are becoming critical priorities for next-generation smart meters.
- Increasing investments in water, gas and electricity metering solutions are expanding opportunities across utility sectors.
Smart Meter Industry Trends and Strategic Insights
- Utilities are moving from basic Automated Meter Reading systems to AMI systems that provide two-way communication capabilities, remote management of meters, outages detection and consumption tracking in more detail.
- Use of RF-based communication technology, as well as other wireless communication technology such as cellular technology, NB-IoT and LTE-M, is becoming common in the installation of smart meters.
- As more people are adopting rooftop solar systems, storage batteries, electric vehicles and other distributed energy resources, there is a rising need for smart meters that can measure energy in both directions and make use of interval data collection.
- Competition in the meter market is shifting focus from the hardware of the devices to the management of metering data through cloud services, analytical services, remote firmware updates and AI solutions for consumption analysis.
- With more meters being deployed on digital infrastructure, cyber security is emerging as an essential purchasing criterion for utilities, focused on encrypted communication, secure device identification, secure firmware updates and securing customer consumption information.
Smart Meter Market Scope
| Metrics | Details | |
| 2025 Market Size | US$ 29.70 Billion | |
| 2035 Projected Market Size | US$ 73.57 Billion | |
| CAGR (2026-2035) | 9.8% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | North America | |
| By Meter Type | Smart Electric Meter, Smart Gas Meter and Smart Water Meter | |
| By Technology | Advanced Metering Infrastructure (AMI) and Automated Meter Reading (AMR) | |
| By Communication | Radio Frequency (RF), Power Supply System and Cellular | |
| By Component | Hardware and Software | |
| By End-User | Residential, Commercial and Industrial | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, Russia, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Turkiye, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Why does this report matter in 2026?
Smart meters market will be especially relevant to utilities in 2026, owing to the shift from simple automated meter reading to advanced AMI and grid-edge technologies. The adoption of rooftop solar, battery storage, electric vehicles and other forms of distributed energy resource is making it necessary for utilities to have access to detailed two-way consumption information. Moreover, as utilities continue to focus on meter upgrades, loss prevention, remote operation, time-of-use tariffs and digital billing, smart meters will become increasingly essential as an infrastructure component.
Furthermore, the market is now moving to an era where there is more value attached to the platform, analytics, security and service than the meter itself. In light of the above trend, utilities and tech vendors are looking at RF and cellular connectivity, AI-powered meter data analytics, secure firmware management, interoperability and integration into existing utility systems while choosing smart meters. A study with an emphasis on 2026 will enable the target groups to determine the technologies, methods of implementation, organizations and regions, which are developing fast and where growth opportunities lie in the smart metering industry.
Smart Meter Market White Space & Investment Opportunities
- As utilities in emerging countries start substituting traditional meters with advanced AMI systems, investments will become available to companies producing smart meters, as well as communication and integration solutions vendors.
- Installation of rooftop photovoltaics, batteries and prosumer connections results in the need for smart meters allowing for two-way energy accounting and continuous monitoring of energy consumption.
- Utility needs for meter data management, cloud platforms, artificial intelligence-based consumption analytics and automated billing solutions create new opportunities other than just smart meters production.
- The advent of technologies like NB-IoT, LTE-M and many others related to cellular communications technology is giving rise to investment prospects for reliable connectivity solutions aimed at large-scale smart metering systems.
- The proliferation of smart meters is opening up prospects in cybersecurity, device authentication, firmware updates, remote diagnostics and lifecycle management of smart meters.
Smart Meter Future Market Transformation
Smart meter market would witness transformation from automated metering towards smart grid edge infrastructure that would enable flexibility and decentralization of the grid. In future, smart meters would increasingly integrate bi-directional metering, real time communication, edge computing, AI-based analysis and security for managing roof top solar, battery storage, electric vehicles, dynamic tariffs and demand response. The utilities would give more importance to interoperable platforms that integrate the meters with the distribution management system and distributed energy resources, whereas the vendors would increasingly compete based on their software, analytics and remote asset management capabilities.
Smart Meter Market Buyer Decision-Making Criteria
The utilities and energy service companies will determine the suitability of the smart meters through the reliability of AMI performance, accuracy of the meter readings, security of the two-way communication system and the ease with which it can integrate with the utility infrastructure. Decisions on purchasing the meters are being made not only based on the cost of purchasing the meter but also considering other issues such as cost per life cycle, communication range, interoperability, cybersecurity, scalability, the vendor’s ability to support large-scale deployment and long-term maintenance. Another significant factor becoming relevant due to the increasing use of rooftop solar, battery storage, EVs and dynamic tariffs is bidirectional measurement and visibility of the grid.
Major Buyer Decision-Making Criteria
- Meter Accuracy and Measurement Performance
- AMI and Two-Way Communication Capability
- RF, Cellular and IoT Connectivity
- Interoperability with Existing Utility Systems
- Cybersecurity and Data Protection
- Total Cost of Ownership
- Scalability for Large-Scale Deployments
- Bidirectional Metering for Distributed Energy Resources
- Meter Data Management and Analytics
- Remote Monitoring and Firmware Management
- Battery Life and Device Reliability
- Vendor Track Record and Utility References
- Installation, Maintenance and After-Sales Support
- Compliance with Local Metering and Communication Standards
Smart Meter Market Economic & Investment Analysis
The smart meter market is experiencing growth due to the constant investment by utility companies in distribution grid upgrade, AMI implementation, traditional meter replacement and loss reduction. Utility companies are more interested in assessing smart meter initiatives in terms of cost savings after a period of time and not the initial cost of purchase since remote meter readings, automatic billing, outage detection and lower field services can provide cost savings for smart meter projects. There are new avenues of investment that have opened up in developing countries where smart-meter installations are supported by governments and where distribution sector improvements are also occurring in order to enhance revenue collection.
The areas for investment in AMI go far beyond merely manufacturing smart meters, including communications, management of meter data, analytics, security, installations and lifecycle services. The combination of rooftop solar, battery storage, Electric Vehicle (EV) charging and dynamic tariffs is making advanced meters more valuable as they are capable of bi-directional measurement and detailed data collection. Investors and strategy players are thus focusing on businesses that have the capacity to scale in production, relationships with utility providers, steady software and service revenues, high interoperability skills and the ability to take part in major multi-year advanced metering infrastructure deployment programs.
Smart Meter Investment Trends in the Market
- There has been increased investment in the large-scale deployment of AMI systems as an alternative to traditional metering and for remote meter reading and outage management.
- There is an increased shift in investment towards smart meters that facilitate distributed energy generation through rooftop solar and battery storage.
- There has been an increase in utility spending from smart meter devices to data management, cloud computing, machine learning algorithms and remote asset management.
- There have been investments in the RF and cellular communications technology, NB-IoT and LTE-M due to the need by the utility companies for reliable communication of geographically distributed smart metering systems.
- Cybersecurity investments have increased due to the implementation of millions of connected meters that require cybersecurity services in terms of secure communication and firmware security among others.
Strategic Indicators for Smart Meter Market
High Regulation Impact
The smart meter market is characterized by high regulatory significance due to the fact that the installation of smart meters depends on such issues as utility licensing, metering precision standards, privacy protection standards, cybersecurity standards, communications standards and government initiatives for Advanced Metering Infrastructure programs. The regulators have an impact on meter specifications, interoperability, consumer data management, remote disconnect and reconnect procedures, as well as communication technology options and public utility acquisition models may control the speed of deployment and deployment sizes. Variations in national laws and certification prerequisites may augment manufacturers’ compliance expenditures and result in barriers to entry into new markets, thus playing an important role in the smart-meter market development, buying processes and development into foreign markets.
High Investment Activity
The smart meter market is currently seeing heavy investment interest, with utilities, governments and technology firms allocating their capital towards significant deployment of AMI systems, meter replacements, grid digitization and communications infrastructure. Investment is starting to move well beyond just the meters themselves and into areas such as the RF and cellular networks, meter data management, security, AI analytics and remote asset management. There are significant opportunities available for firms with the ability to manufacture at scale, an AMI system and related services offering and recurring revenue streams.
Supply Chain Disruption
Supply chain risks to the smart meter market are presented due to the reliance of the meters on semiconductors, communications components, metering components, sensors, batteries and other electronic components needed in the manufacturing of connected meters. Geopolitical issues, component shortages, logistics interruptions and regionalization of electronics manufacturing could pose risks to the cost of meter production and delivery times especially during large utility AMI implementations that have fixed timelines. Increased reliance on dedicated communication modules due to the trend towards cellular, RF and IoT-based smart metering solutions is also being counteracted by suppliers diversification, localized production, inventory control and localization of smart metering component production.
Pricing Volatility
The pricing volatility in the smart meter market stems from fluctuations in semiconductor, copper, silver, communication module and importation of electronic components pricing and recent cost pressures are especially noticeable in India. In September 2026, rising commodity and component costs were predicted to elevate smart meter costs by anywhere between 10% and 20%, causing strain for manufacturers that are bound by fixed-price contracts. Pricing for smart meters, however, is highly variable depending on specifications. For instance, in India in 2026, a single-phase AMI-compliant meter was priced at approximately ₹2,800. In contrast, a three-phase meter or higher voltage meter would be in the price range of ₹4,100 to ₹14,850 depending on specifications and usage. Such price variability necessitates sourcing, localization and long-term procurement contracts for cost-efficient operations of AMI projects.
Procurement Pressure
Procurement pressure within the smart meter market is on the rise as utility companies move towards larger AMI deployments with higher expectations regarding meter accuracy, communication capability, security, interoperability and extended meter support. Procurement professionals are increasingly looking at cost-of-ownership, deployment capability, local production, firmware support, communication-network capability and capability to manage millions of meters instead of just focusing on the price per unit. In markets like India, the implementation of large-scale pre-paid metering systems and AMIs places even more demands on suppliers to install equipment within tight deadlines and maintain high levels of quality and post-installation services. This puts an emphasis on developing local manufacturing capability, system integration skills and utilities partnerships.
New Technology Adoption
The adoption of new technologies in the smart meters market will change the use of traditional AMR to AMI, cellular NB-IoT and LTE-M, RF Mesh, Edge Intelligence and AI-enabled meter data analysis technologies. There is an emerging trend among utilities where smart meters which are capable of measuring energy in both directions, having firmware updates, detecting outages, monitoring power quality and analyzing loads in real time to facilitate solar, batteries, EVs and dynamic rates are being adopted. The ability of AI and edge computing technologies to detect abnormal consumption, discover the possibility of energy theft, enhance demand prediction and ensure quick responses from the grid is also being harnessed. The current shift in technology is raising the demand for smart meters that have the ability to communicate and process data securely from the grid’s edge.
Regional Expansion Opportunity
The potential for regional expansion in the smart meter market lies in the emerging power grids wherein utilities are upgrading from old-fashioned metering systems to newer ones, decreasing transmission losses and increasing AMI installations. There are several growth areas for smart meters as well such as India, Southeast Asia, the Middle East, Latin America and selected African markets as utilities adopt prepaid metering, remote disconnects, time-of-use pricing and online billing systems. Further expansion will be possible with the increase in adoption of rooftop solar, distributed energy resources and electric vehicles, all of which will need two-way, interval-based metering. The vendors who can offer tailored meter designs, local communication protocols, local manufacturing, integration with the utility’s system and large-scale installations can have an edge.
Government Policy Support
The government’s support through policy will act as an important growth driver for the smart meter market, with governments and electricity regulatory bodies making use of AMI mandation policies, smart grid upgrade schemes, loss reduction objectives and utility digitization policies to hasten the adoption of alternative meters in lieu of conventional meters. The growing trend towards prepaid metering schemes, time of use tariffs, distributed energy resources, rooftop solar and remote metering are driving increased demand for smart meters that can measure both ways and communicate back to the utility. Procurement opportunities on large scales are being created due to the government-sponsored implementation of smart metering solutions in emerging economies like India, where local content and local manufacturing regulations are compelling suppliers to localize production and supply chains. Such government policies are facilitating greater visibility into deployments and demand for smart meters and AMI systems.
Pricing Intelligence
Pricing intelligence in the smart meter market has evolved from focusing only on hardware to becoming more about the configuration, communication technology, scale of deployment and life cycle considerations. Based on the 2026 market benchmarks in India, the cost of a single phase AMI-enabled smart meter would be roughly ₹2,800 and the costs of three phase and above could be between ₹4,100 and ₹14,850, according to configuration. Large utility tenders can cut effective unit pricing even further because of volume buying, although the suppliers should consider communication modules, cybersecurity, installation, system integration and maintenance. This is the reason why the cost per meter, total cost of ownership and price to performance become more important criteria for utilities when choosing smart meter suppliers.
| HS Code | Reporter | Trade Flow | 2025 Trade Value | Interpretation |
| 9028 | China | Exports | US$2.8 Billion | China is a leading global exporter of metering equipment, reflecting its large manufacturing base and strong international supply capacity. |
| 9028 | Mexico | Exports | US$1.5 Billion | Mexico is a significant exporter of metering equipment, supported by its manufacturing and North American supply-chain integration. |
| 9028 | United States | Imports | US$1.9 Billion | The United States is a major importing market, reflecting strong demand for electricity, gas and other metering equipment. |
| 9028 | Germany | Imports | US$635 Million | Germany maintains substantial import demand for metering equipment, supporting utility modernization and advanced metering deployment. |
Note: HS Code 9028 covers gas, liquid and electricity supply or production meters, including calibrating meters.
AI Impact Analysis of Smart Meter Market
AI is making smart meters more than consumption measurement tools to smart grid components. The AI algorithms can be applied on the data from the meters to discover unusual consumption behavior, detect any electricity theft, perform demand forecasting, discover outage potentials and even do predictive maintenance. There is also the possibility for the utilities to employ AI-based analytics to segregate customer consumption and optimize their tariffs, demand response plans and distributed energy resources management. It is adding value to the implementation of AMI through the ability to gain operational information from the huge amount of data collected through the meters.
There are also many applications of AI in the layer that comprises the smart-meter software and data management, namely through the use of automatic anomaly detection, load forecasting, renewable generation forecasting and recommendations on energy consumption by the customer. As distributed solar power generation, battery storage, EVs and reverse power flow become more common, AI can integrate smart meter data along with grid data for forecasting and grid balancing. Nevertheless, the growing adoption of AI technology places demands on the quality of data, data security, data protection, reliability of models and interoperable utility platforms, which become key competitive advantages for smart meter suppliers.
Disruption Analysis of Smart Meter Market
Disruption of the smart meter market occurs due to the transition from individual and automated metering to smart, connected AMI and grid edge systems. The meters are now becoming smarter in that they are increasingly equipped with two-way communications, remote firmware updating, outage detection, power quality monitoring and bi-directional measurement capabilities. The use of rooftop solar, batteries and electric vehicles, as well as distributed energy resources, is creating additional disruptions because utilities require much more detailed information about the electricity networks.
Disruption is also extending beyond the physical meter into software-defined utilities infrastructure, where cloud meter data management, artificial intelligence analysis, cyber security and connectivity via cellular or IoT are playing important roles in smart metering installations. Such disruptive trends are having an impact on the competitive landscape through the creation of new possibilities for technology suppliers, communications suppliers and software vendors in addition to metering suppliers. Suppliers who can combine dependable metering equipment with communication technologies, real-time analytics, data platforms and distributed energy management systems will have a better chance of adding value as utilities continue down the path of digitized and more flexible distribution networks.
Smart Meter Market BCG Matrix: Company Evaluation
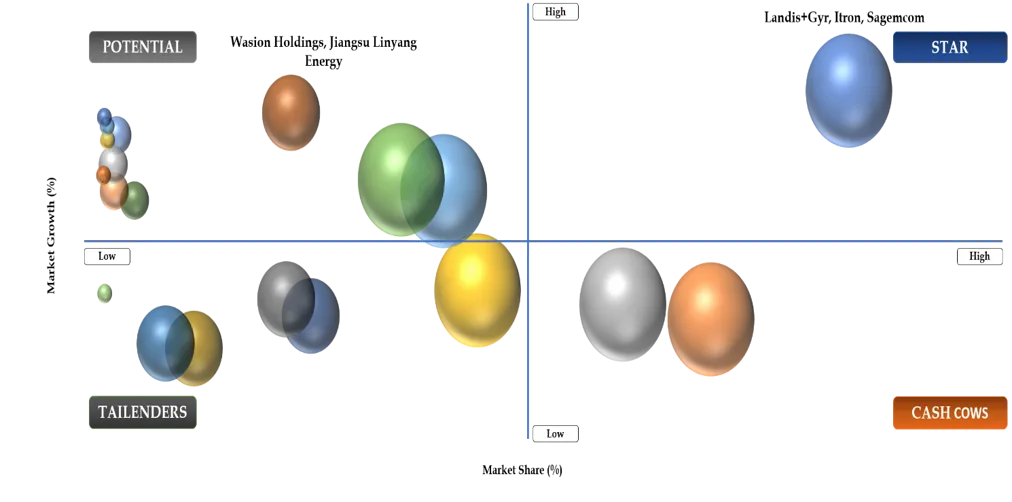
STAR
The firms that are identified as Stars within the smart meter market possess a solid market presence and are highly exposed to rapidly growing AMI, Grid Edge Intelligence and Utility Digitalization. Landis+Gyr, Itron and Sagemcom are well placed due to their wide-ranging smart meters product line, communications technology, meter data platform and increasingly sophisticated grid edge analytics solutions. Their capacity to facilitate large-scale utility deployments while simultaneously moving into monitoring of distributed energy resources, remote asset management and advanced analytics further improves their market positioning.
POTENTIAL
Organizations classified as having Potential are those which are capable of either offering strong technological prowess or established utility ties, but offer an even greater possibility of increasing their share of the smart meter market by virtue of AMI implementation, geographical expansion, or software integration. The companies Wasion Holdings, Jiangsu Linyang Energy, Hexing Electrical, Kamstrup and Genus Power show great promise in terms of being capable of making smart meters, participating in projects of utilities and operating in emerging markets such as China, India and other developing countries. Future success will be determined by how effectively they can scale up to large-scale deployments, improve communications and information management and develop smart grid technologies.
Smart Meter Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
| Smart Grid Modernization | 28% | Utilities and Distribution Networks | Grid Monitoring and Automated Metering | Accelerates AMI deployment and replacement of conventional meters |
| Government Smart Meter Deployment Programs | 24% | Residential and Utility Sectors | Automated Billing and Remote Meter Reading | Creates large-scale procurement opportunities for meter manufacturers |
| Reduction of Electricity Theft and Technical Losses | 20% | Emerging Markets and High-Loss Distribution Networks | Loss Detection and Revenue Protection | Increases demand for connected meters with real-time monitoring capabilities |
| Integration of Distributed Energy Resources | 17% | Residential, Commercial and Industrial Prosumer Segments | Bidirectional Energy Measurement | Drives advanced meters capable of supporting solar, storage and distributed generation |
Driver: Smart Grid Modernization and Large-Scale AMI Deployment
As utilities replace traditional metering infrastructure with Advanced Metering Infrastructure (AMI) to facilitate two-way data exchange, interval-based consumption monitoring, remote meter operations, outage identification and enhanced distribution-grid visibility, smart grid modernization is driving the smart meter market. Demand for bidirectional smart meters that can monitor power transfers between consumers and the grid is also being driven by the growing use of rooftop solar, battery storage, electric vehicles and other distributed energy resources. Opportunities for smart electric, gas and water meters, communication networks and meter-data management solutions are thus increasing due to extensive meter replacement and modernization initiatives, especially in emerging nations.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Initial Deployment and Infrastructure Costs | 30% | Utilities and Distribution Networks | Large-Scale Smart Meter Deployment | Favors phased deployment and long-term utility investment planning |
Cybersecurity and Data Privacy Risks | 25% | Connected Metering Infrastructure | Remote Monitoring and Data Management | Increases demand for secure communications, encryption and cybersecurity solutions |
Interoperability and Legacy-System Integration Challenges | 23% | Utility IT and Grid Infrastructure | AMI Integration and Meter Data Management | Requires standardized communication protocols and system modernization |
| Regulatory and Deployment Complexity | 22% | Utility Procurement and Installation | National and Regional Smart Meter Rollouts | Can delay deployments and increase project costs |
Restraint: High Deployment and System-Integration Costs
High deployment costs continue to be a big constraint as the implementation of smart meters involves not only installing the meters themselves but also building out communication infrastructure, head ends, meter data management solutions, installation, cybersecurity and integrating all these with existing billing systems and utilities’ systems. Utilities implementing millions of meters will have to handle large upfront investments while ensuring compatibility with existing systems. The complexity of on-site installations, lack of communication reach and the requirement of upgrading old systems will also prolong the implementation process.
Smart Meter Market Segment Analysis
The global smart meter market is segmented based on the Meter Type, Technology, Communication, Component, End-User and region.
By Meter Type
Smart Electric Meters Lead the Market as Utilities Accelerate Electricity Grid Digitalization
Smart electric meters occupied around 68.4% of the smart meter market share in 2025 owing to the wide-scale installation of utilities’ AMI, replacement of existing meters, energy loss mitigation initiatives and rising need for consumption data at interval rates. The escalating use of rooftop solar panels, energy storage solutions, EVs and time-of-use pricing is expected to fuel the need for bi-directional electric meters in the future.
By Technology
AMI Emerges as the Fastest-Growing Technology as Utilities Move Beyond Automated Meter Reading
Advanced Metering Infrastructure (AMI) is expected to have a compound annual growth rate of around 10.8% during 2026-2035, fueled by the shift from one-way automated meter reading to two-way communication and remote meter management. The growing use of distributed energy sources, pre-payment metering, dynamic rates and digital grids is propelling the AMI adoption.
Smart Meter Market Geographical Penetration
China Smart Meter Market Trends
The China smart meter market is seeing growth due to the ongoing digitization of the country’s power grids, extensive improvements of the distribution networks and deployment of advanced metering infrastructure in urban and industrial electricity networks. In particular, utilities have been using more smart meters with two-way communication and interval metering in order to enhance their load management, metering and grid visibility. In addition to that, the fast growing use of renewable power, solar energy, energy storage systems and flexible loads is also increasing the need for smart meters with bi-directional metering and real-time data about the edge of the grid. Chinese manufacturers can take advantage of the extensive procurement programs by utilities and existing supply chain in the country, whereas the market differentiators now include precise metering and analytics.
U.S. Smart Meter Market Landscape
The Smart Meter Market in the United States is propelled by utility companies continually investing in Advanced Metering Infrastructure (AMI), modernizing the grid and improving visibility at distribution level. In this context, electric utilities are consistently swapping old metering technology for smart electric meters with two-way communications, remote meter monitoring, outage detection and time-of-use pricing technological capacities amongst other features. Additionally, rising installation of rooftop solar, battery storage, electric vehicles and other sources of distributed energy has increased demand for smart meters that can measure energy in both directions. The competitive landscape is moving towards an AMI-based system that integrates meters, communications networks such as RF mesh or cellular, meter data management and security features, while utility modernization efforts are providing business opportunities to smart-meter companies.
India Smart Meter Market Analysis
The India smart meter market will be fueled by mass replacement of traditional electricity meters in various national smart metering projects, utility loss reduction efforts and grid modernization activities. Prepaid and remote metering smart meters are being adopted by utilities to enhance billing efficiency, minimize losses, increase revenues and collect detailed consumption information. With increased use of rooftop solar and distributed power generation systems, time of day tariffs, electric cars and demand side management, there is a growing need for bidirectional metering and tariff systems. India's increasing domestic manufacturing facilities will also enhance domestic manufacturing capabilities, while the competition is becoming increasingly focused on AMI systems, communication security, meter data management and deployment.
Japan Smart Meter Market Outlook
Support for the Japan smart meter market exists through the country-wide shift to smarter electricity metering systems and grids and optimized energy consumption. Utilities in Japan are investing in smart meters in order to achieve automated meter reading, remote management of services, electricity pricing based on the time of consumption and better management of distribution networks. With Japan adopting more rooftop solar, batteries, electric vehicles and distributed energy sources, there is increased need for consumption information with higher frequency and in both directions, while energy resilience is fueling demand for smarter grid monitoring. Competition revolves around AMI interoperability, secure communications, analysis of metering data and integration of smart meter infrastructure with virtual power plants and new energy management systems.
Smart Meter Market Competitive Landscape
- Leading providers of smart meters have adopted a competitive approach by incorporating the use of AMI solution packages including meters, communication systems, MDMs and utility software rather than depending on hardware alone.
- There is intensifying competition in communication capabilities as companies continue to improve RF mesh, cellular, NB-IoT, LTE-M and various other technologies to serve different utility deployment needs.
- Top players are augmenting their portfolios with smart meters for electric, gas and water, thereby making it possible to fulfill diverse utility applications and huge multi-utility projects.
- Firms are distinguishing themselves using innovative analytics, remote meter management, outages detection, demand monitoring and grid intelligence functionalities which create value for the firm other than just automated meter readings.
- Strategic partnerships, technology integration and acquisition of companies is an emerging strategy for competing as firms look for ways to enhance AMI functionalities and software solutions.
Public Company Q1-Q2 2026 Performance Comparison
The table below presents an analysis of five publicly listed firms with either direct or strategic exposure to the smart meter market. Financial data are taken at either a firm-wide or segment level, since smart-meter revenues are usually not disclosed. Performance drivers help in differentiating firm performance from smart-meter and smart grid exposure.
| Company | Q1–Q2 2026 Performance | Smart Meter Exposure | Key Performance Driver |
| Landis+Gyr Group AG | US$232.3 million Q1 FY2026 revenue, down 6.8% YoY | Direct smart-meter, AMI, grid-intelligence and connected-platform provider | Utility grid modernization, recurring software and services and timing of project deployments |
| Itron, Inc. | US$587 million Q1 2026 revenue, down 3% YoY; Adjusted EBITDA US$92 million, up 5% | Direct provider of smart meters, AMI networks, software, analytics and utility solutions | Utility investment in grid intelligence, resiliency, analytics and operational intelligence |
| Siemens AG | US$22.6 billion Q2 FY2026 revenue, approximately flat YoY; comparable revenue increased 6% | Smart Infrastructure business supports intelligent grids, energy management and metering solutions | Strong Smart Infrastructure and Digital Industries performance |
| Schneider Electric SE | US$24.5 billion H1 2026 revenue, up 14% organically | Energy-management, digital-grid, automation and connected-energy infrastructure exposure | Strong Energy Management growth driven by electrification, digitalization and data-center demand |
| Honeywell Technologies | US$5.19 billion Q2 2026 sales, up 3% reported and 4% organically | Smart metering exposure through Elster metering technologies and connected utility infrastructure | Building automation, industrial automation and connected infrastructure growth |
Note: Company-level revenue should not be interpreted as smart meter revenue unless separately disclosed. Financial periods differ because companies follow different fiscal calendars.
Key Companies of Smart Meter Market
- Landis+Gyr Group AG
- Itron, Inc.
- Siemens AG
- Schneider Electric SE
- Honeywell International Inc.
- ABB Ltd.
- Sagemcom SAS
- Kamstrup A/S
- Wasion Holdings Limited
- Sensus USA Inc. (Xylem Inc.)
- Aclara Technologies LLC
- Hexing Electrical Co., Ltd.
- Jiangsu Linyang Energy Co., Ltd.
- Ningbo Sanxing Medical & Electric Co., Ltd.
- Holley Technology Ltd.
- Genus Power Infrastructures Limited
- HPL Electric & Power Limited
- EDMI Limited
- Badger Meter, Inc.
- Secure Meters Limited
Company Profiles of Smart Meter Market
Landis+Gyr Group AG
Landis+Gyr Group AG is one of the major players in the smart metering and grid-edge technology segment. The company places emphasis on advanced metering infrastructure (AMI), grid intelligence and utility digitalization. Landis+Gyr's product range consists of smart electric meters, communication network technologies and software to enable utilities to optimize consumption visibility, outage management and distribution grid operations.
Competitive priorities consist of developing grid-edge intelligence, enhancing RF mesh and cellular connections, incorporating distributed energy resource monitoring and building software and analytics capabilities.
Itron, Inc.
Itron, Inc. is one of the world’s leading firms that offers smart metering and utility technologies by providing smart meters for electricity, gas and water along with advanced metering infrastructure networks, meter data management, analysis and grid-edge intelligence.
Competitive priorities involve the development of grid-edge intelligence capabilities, artificial intelligence-driven analytics, distributed energy resources, improved visibility into utilities’ networks and increased use of AMI software products.
Siemens AG
The Siemens AG Company is active in the smart meters market through the company’s Smart Infrastructure division that offers services related to intelligent grid, energy management, automation and digitalization technologies for infrastructure owners and utilities.
The competitive priorities of the company include improvement of the digital grid, integration of smart-meter data into grid management systems, integration of distributed energy resources, grid automation and utility digitalization solutions.
Schneider Electric SE
Schneider Electric SE is a participant in the smart metering value chain through its digitalization, automation and management technologies that facilitate utilities and energy consumers' ability to manage energy consumption.
Competitive priorities in Schneider Electric include connected energy infrastructure expansion, integration of smart meters with digital energy platforms, distributed energy resources management, analytics at the grid edge and interoperability among utility and energy management systems.
Honeywell International Inc.
The participation of Honeywell International Inc. in the smart meters market is evident in terms of the company’s metering of utilities through its electricity and gas metering technology within the company’s Elster group.
Priority areas in the competition are developing connected meters technology, enhancing communications/data management technology, enabling utility transformation and cybersecurity/ metering technology integration into automation and energy management.
ABB Ltd.
ABB Ltd. is part of the smart meters value chain through its involvement in intelligent electrification, digital grid and energy management systems that combine measurement and monitoring with distribution grid systems.
Areas of competitive importance include improved digital grid integration, distributed energy resource and electrification support, increased intelligence in power management, improved grid visibility and connected electrical infrastructure to the utility digital systems.
Smart Meter Market Major Pain Points
- The initial costs involved in the purchase of smart meters, their communication networks, installation process and incorporation into AMI pose financial problems to utilities.
- Interoperability issues may arise in the incorporation of the smart meters into old utility billing and management systems as well as customer information systems.
- Ensuring trustworthy communication connectivity in rural, remote and densely populated regions continues to be a problem, especially in areas where RF or cell phone connectivity is inconsistent.
- Smart meters generate enormous amounts of consumer consumption data that pose operational challenges in various areas such as data management, cybersecurity, data protection and secure transmission of data.
- Customer rejection, installation problems, regulatory requirements and labor shortage may hamper the transition from old meters to new ones under the utility roll-out programs.
Smart Meter Market Recent Developments
- September 2026 - Landis+Gyr: Landis+Gyr has released the Revelo E370 grid-edge meter that provides RF Mesh, Mesh IP and Wi-SUN communication capabilities, along with high-resolution sensing for detecting anomalies and power quality monitoring.
- September 2026 - Itron: Itron released its Riva IEC Grid Edge suite of products in the Asia Pacific region, with Riva S and Riva T meters that help increase visibility of the low voltage networks and integrate distributed energy resources.
- September 2026 - Sagemcom: Sagemcom's SICONIA SMARTY IQ-LTE smart meter gateway was whitelisted by Schleupen, boosting interoperability and secure meter data integration in the smart meter rollout in Germany.
- September 2026 - India Domestic Smart Meter Chips: India considered making it compulsory to use domestically made chips for smart meters by mid-2028 based on goals related to cybersecurity, supply chain security and cost savings.
- August 2026 - India Smart Meter Rollout: The Government of India instructed states and Union Territories to expedite the installation of smart meters in all categories of consumers, contributing to the massive deployment of AMI in India’s power sector modernization program.
Analyst View / Opinion on Smart Meter Market
- The smart meters market is moving from the initial automation of meter reading to full AMI adoption, increasing the need for two-way communications and remote monitoring systems.
- The greatest future demand will come from utilities upgrading their networks to incorporate roof-top solar power, battery storage, electric cars and other forms of distributed energy resources that require greater and two-way energy measurements.
- The competition in the market is shifting from meters to solutions that provide not only meters but also remote asset management capabilities and communication networks.
- Cellular connectivity technologies such as NB-IoT and LTE-M will become increasingly important where utilities need scalable connectivity without a great deal of dedicated communications infrastructure.
- Issues such as cybersecurity, interoperability and integration with existing utility systems will continue to be important differentiators, thus vendors that can deliver secure and interoperable end-to-end AMI solutions will have strong competitive positioning.
Target Audience of Smart Meter Market
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| Electricity & Power Utilities | Utility Companies & Grid Operators | Assess smart-meter deployment, AMI adoption and grid modernization opportunities |
| Metering & Electrical Equipment | Smart Meter Manufacturers | Evaluate market size, competitive positioning and technology trends |
| Energy Technology & Software | AMI Platform & Software Providers | Assess demand for meter-data management, analytics and connected-grid solutions |
| Gas & Water Utilities | Gas & Water Utility Operators | Identify opportunities in smart gas and smart water metering |
| Telecommunications & IoT | IoT & Communication Network Providers | Evaluate demand for RF, cellular and other smart-meter communication technologies |
| Electrical & Electronic Components | Component Suppliers | Assess demand for smart-meter hardware, communication modules and electronic components |
| Government & Regulatory | Energy Regulators & Policymakers | Support smart-grid planning, regulatory decisions and smart-meter rollout programs |
| Investment & Financial Services | Investors & Private Equity Firms | Evaluate market attractiveness, investment opportunities and competitive dynamics |
| Electricity & Power Utilities | Utility Companies & Grid Operators | Assess smart-meter deployment, AMI adoption and grid modernization opportunities |
| Metering & Electrical Equipment | Smart Meter Manufacturers | Evaluate market size, competitive positioning and technology trends |
Why Choose DATAM?
- Data-Driven insights: Dive into detailed analyses with granular insights such as pricing, market shares and value chain evaluations, enriched by interviews with industry leaders and disruptors.
- Post-Purchase Support and Expert Analyst Consultations: As a valued client, gain direct access to our expert analysts for personalized advice and strategic guidance, tailored to your specific needs and challenges.
- White Papers and Case Studies: Benefit quarterly from our in-depth studies related to your purchased titles, tailored to refine your operational and marketing strategies for maximum impact.
- Annual Updates on Purchased Reports: As an existing customer, enjoy the privilege of annual updates to your reports, ensuring you stay abreast of the latest market insights and technological advancements. Terms and conditions apply.
- Specialized Focus on Emerging Markets: DataM differentiates itself by delivering in-depth, specialized insights specifically for emerging markets, rather than offering generalized geographic overviews. The approach equips our clients with a nuanced understanding and actionable intelligence that are essential for navigating and succeeding in high-growth regions.
- Value of DataM Reports: Our reports offer specialized insights tailored to the latest trends and specific business inquiries. The personalized approach provides a deeper, strategic perspective, ensuring you receive the precise information necessary to make informed decisions. The insights complement and go beyond what is typically available in generic databases.
What DATAM Uniquely Provides
- DATAM offers a comprehensive analysis of smart meter penetration within electric, gas and water utilities, which helps all concerned parties recognize the trends associated with demand.
- DATAM assesses the trends regarding AMI/AMR deployment, as well as the development of RF and cellular communication technologies, which helps to recognize technology trends that will impact the demand for smart meters.
- DATAM performs a deep analysis of the utility needs in regard to distributed energy resources such as rooftop solar, energy storage and bi-directional energy metering.
- The competitive position of manufacturers of smart meters is analyzed through their product portfolios, communications, software integration and utility-centric offerings.
- DATAM provides an insight into the possible areas where growth is possible in the field of hardware, software, connectivity and services relating to smart metering.