


Poland Data Center Cables & Wires Market Size and Overview
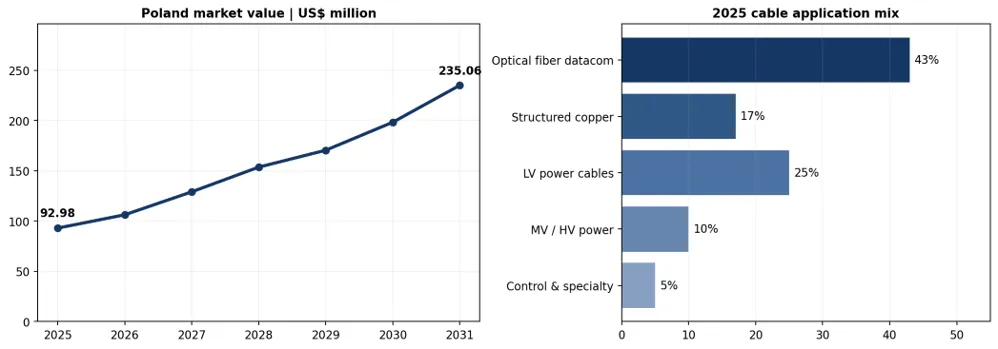
The Poland Data Center Cables & Wires Market was valued at US$ 92.98 million in 2025 and is projected to reach US$ 235.06 million by 2031, registering 16.72% annualized growth. Demand encompasses high-count optical-fiber cables, structured copper links, low- and medium-voltage electrical cables, control wiring and specialized connectivity serving mission-critical facilities.
Warsaw and surrounding Mazowieckie locations remain the core of Poland's hyperscale and colocation market, supported by cloud adoption, enterprise migration and demand for AI-ready capacity. Poznan, Krakow, Wroclaw and Gdansk offer selected enterprise, network and disaster-recovery opportunities. Fiber network density, dual power routing, grid access and phased campus fit-out directly shape cable procurement schedules.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 92.98 Million | US$ 235.06 Million | 16.72% |
Poland Data Center Cables & Wires Key Takeaways
Market demand rises from US$ 92.98 million in 2025 to US$ 235.06 million in 2031, adding US$ 142.08 million in annual cable requirements.
The 16.72% annualized growth outlook reflects cloud and AI infrastructure expansion and upgraded campus network and electrical architectures.
Greater Warsaw is the leading development hub, with carrier-neutral facilities and phased hyperscale campuses creating recurring infrastructure demand.
High-fiber-count trunks, low-loss optical links and factory-terminated cable systems improve installation productivity in dense AI networking.
Redundant A/B electrical paths, fire-performance-rated cable routes and LV/MV feeders remain integral to facility commissioning and uptime.
Procurement timing depends on confirmed utility power, approved designs, fit-out schedules and qualified local cabling and MEP contractors.
Poland Data Center Cables & Wires Industry Trends and Strategic Insights
AI compute and distributed cloud architectures support denser optical trunks, low-loss connectivity and more extensive testing and monitoring requirements.
Large colocation campuses specify dual-path electrical feeds, low-smoke and fire-rated cabling and documented cable installation quality.
Prefabricated and preterminated copper and fiber assemblies shorten on-site work and enable replication across multiple data-hall phases.
Carrier diversity, electrical connection availability, power costs and contractor access shape facility siting and cable-package selection.
Poland Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 92.98 Million |
| 2031 Projected Market Size | US$ 235.06 Million |
| CAGR (2026–2031) | 16.72% |
| Geographic Coverage | Poland: Warsaw / Mazowieckie, Poznan, Krakow, Wroclaw, Gdansk and other national markets |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
The market covers data-center cabling demand within Poland, including optical fiber and structured copper connectivity, power-distribution cabling, control wiring, transmission medium, voltage rating, insulation and sheathing, installation configuration and facility end-use. Geographic analysis focuses on Warsaw and other Polish data-center clusters.
Poland Data Center Cables & Wires Market White Space & Investment Opportunities
Hyperscale connectivity: Warsaw campus expansions support dense optical backbones, modular fiber distribution, low-loss trunks and scalable cable management.
Critical electrical power: Redundant feeds, backup systems and new halls drive demand for qualified LV/MV power cables and fire-safe installation.
Project fulfillment: Local stocking, preterminated packages and certified installers support time-sensitive construction and expansion cycles.
Suppliers should prioritize funded Warsaw and Mazowieckie campus phases while selectively tracking projects around Poznan, Krakow and Wroclaw. Early engagement with operators, EPC/MEP contractors and structured-cabling integrators improves qualification before procurement awards.
Driver Impact Analysis
New AI-capable data halls and colocation expansion increase fiber trunk density and electrical cable requirements. Early design engagement helps suppliers position tested products and factory-built connections before tender issuance.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Hyperscale and AI campus projects | Dense fiber trunks, network copper and LV/MV power circuits | High | Engage owner-operators and MEP consultants before detailed design freeze. |
| Cloud region and colocation expansion | Carrier fiber and structured cabling | High | Pursue standardized packages across campus phases. |
| Grid and backup-power requirements | Redundant feeds and compliant facility cables | High | Qualify electrical designs and installation contractors. |
| Network performance upgrades | Preterminated fiber and low-loss interconnects | Medium | Target retrofit and capacity expansion opportunities. |
Cloud adoption, local enterprise workloads and network interconnection growth stimulate redundant fiber and power-cabling architecture. Expansion of carrier access can create additional cable pathways even at operational facilities.
Restraint Impact Analysis
Grid-connection queues, site-permitting timelines and staged commissioning can defer cable releases. Procurement should follow approved campus power, fit-out milestones and construction sequencing.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid connection and site readiness | Construction phasing and cable order timing | High | Monitor energization milestones and grid permits. |
| Fire performance and qualification | Specification approval and project delivery | High | Maintain country-specific tested product documentation. |
| Input-cost and logistics changes | Cable margins and procurement reliability | Medium | Adopt disciplined price clauses and local stock. |
| Uneven regional project execution | Country risk and sales conversion | Medium | Rank sites by funding, permits and customer commitments. |
Fiber and copper input pricing, fire-performance requirements and skilled installer availability influence product selection, delivery reliability and package costs. Tender qualification can differ between operators and contractors.
Poland Data Center Cables & Wires Market Competitive Landscape
The market combines Polish power-cable manufacturing with international data-center connectivity systems. TELE-FONIKA Kable, NKT and Prysmian address facility power distribution while Corning, CommScope and Belden compete in optical and structured cabling. Nexans, Legrand, Schneider Electric and Bitner further support electrical connectivity and installation requirements.
| COMPANY | POLAND DATA CENTER CABLES & WIRES POSITIONING |
| TELE-FONIKA Kable | Poland-based power-cable producer serving low- and medium-voltage facility electrical networks. |
| Prysmian | Power cables and high-density optical fiber solutions for data-center campuses. |
| NKT | Power-cable systems with regional production and engineering support. |
| Nexans | Electrical distribution cables and connectivity systems for industrial and digital infrastructure. |
| Corning | High-density optical-fiber trunks and low-loss data-center connectivity. |
| CommScope | Structured copper, fiber cabling and factory-terminated connectivity. |
| Belden | Mission-critical copper and fiber cabling for IT and industrial networks. |
| Bitner | Polish specialty electrical and installation cables for building and infrastructure uses. |
| Legrand | Fiber and copper connectivity, racks and facility electrical cabling infrastructure. |
| Schneider Electric | Data-center critical-power infrastructure and associated distribution connectivity. |
Competition centers on compliant fire-rated electrical cables, low-loss high-density optics, factory-terminated solutions, delivery schedules and engineering support. Local qualification and Warsaw-area inventory improve response to staged campus orders.
Poland Data Center Cables & Wires Market Recent Developments
March 4, 2026 — Product launch: Prysmian introduced Sirocco Ultra, a high-density microduct cable using 160-micron optical fiber for data centers and digital networks.
March 4, 2026 — Technology collaboration: Prysmian and Relativity Networks presented next-generation hollow-core optical-fiber technology for hyperscale and AI-network applications.
April 9, 2026 — Data-center opening: Data4 inaugurated its second facility at Jawczyce near Warsaw, adding 10 MW with a campus target of up to 60 MW.
June 16, 2026 — Network expansion: Zayo Europe launched two Tier-1 IP points of presence at Equinix WA1 and Atman WAW-2 in Warsaw.
July 22, 2026 — Corporate initiative: Prysmian announced accelerated investment and commercial focus on data-center growth within its Digital Solutions activities.
August 5, 2026 — Network expansion: Core-Backbone commissioned a new point of presence at Equinix WA1 in Warsaw and migrated an existing MPLS PoP to the facility.


























































