Metal Coil Lamination Market Size and Overview
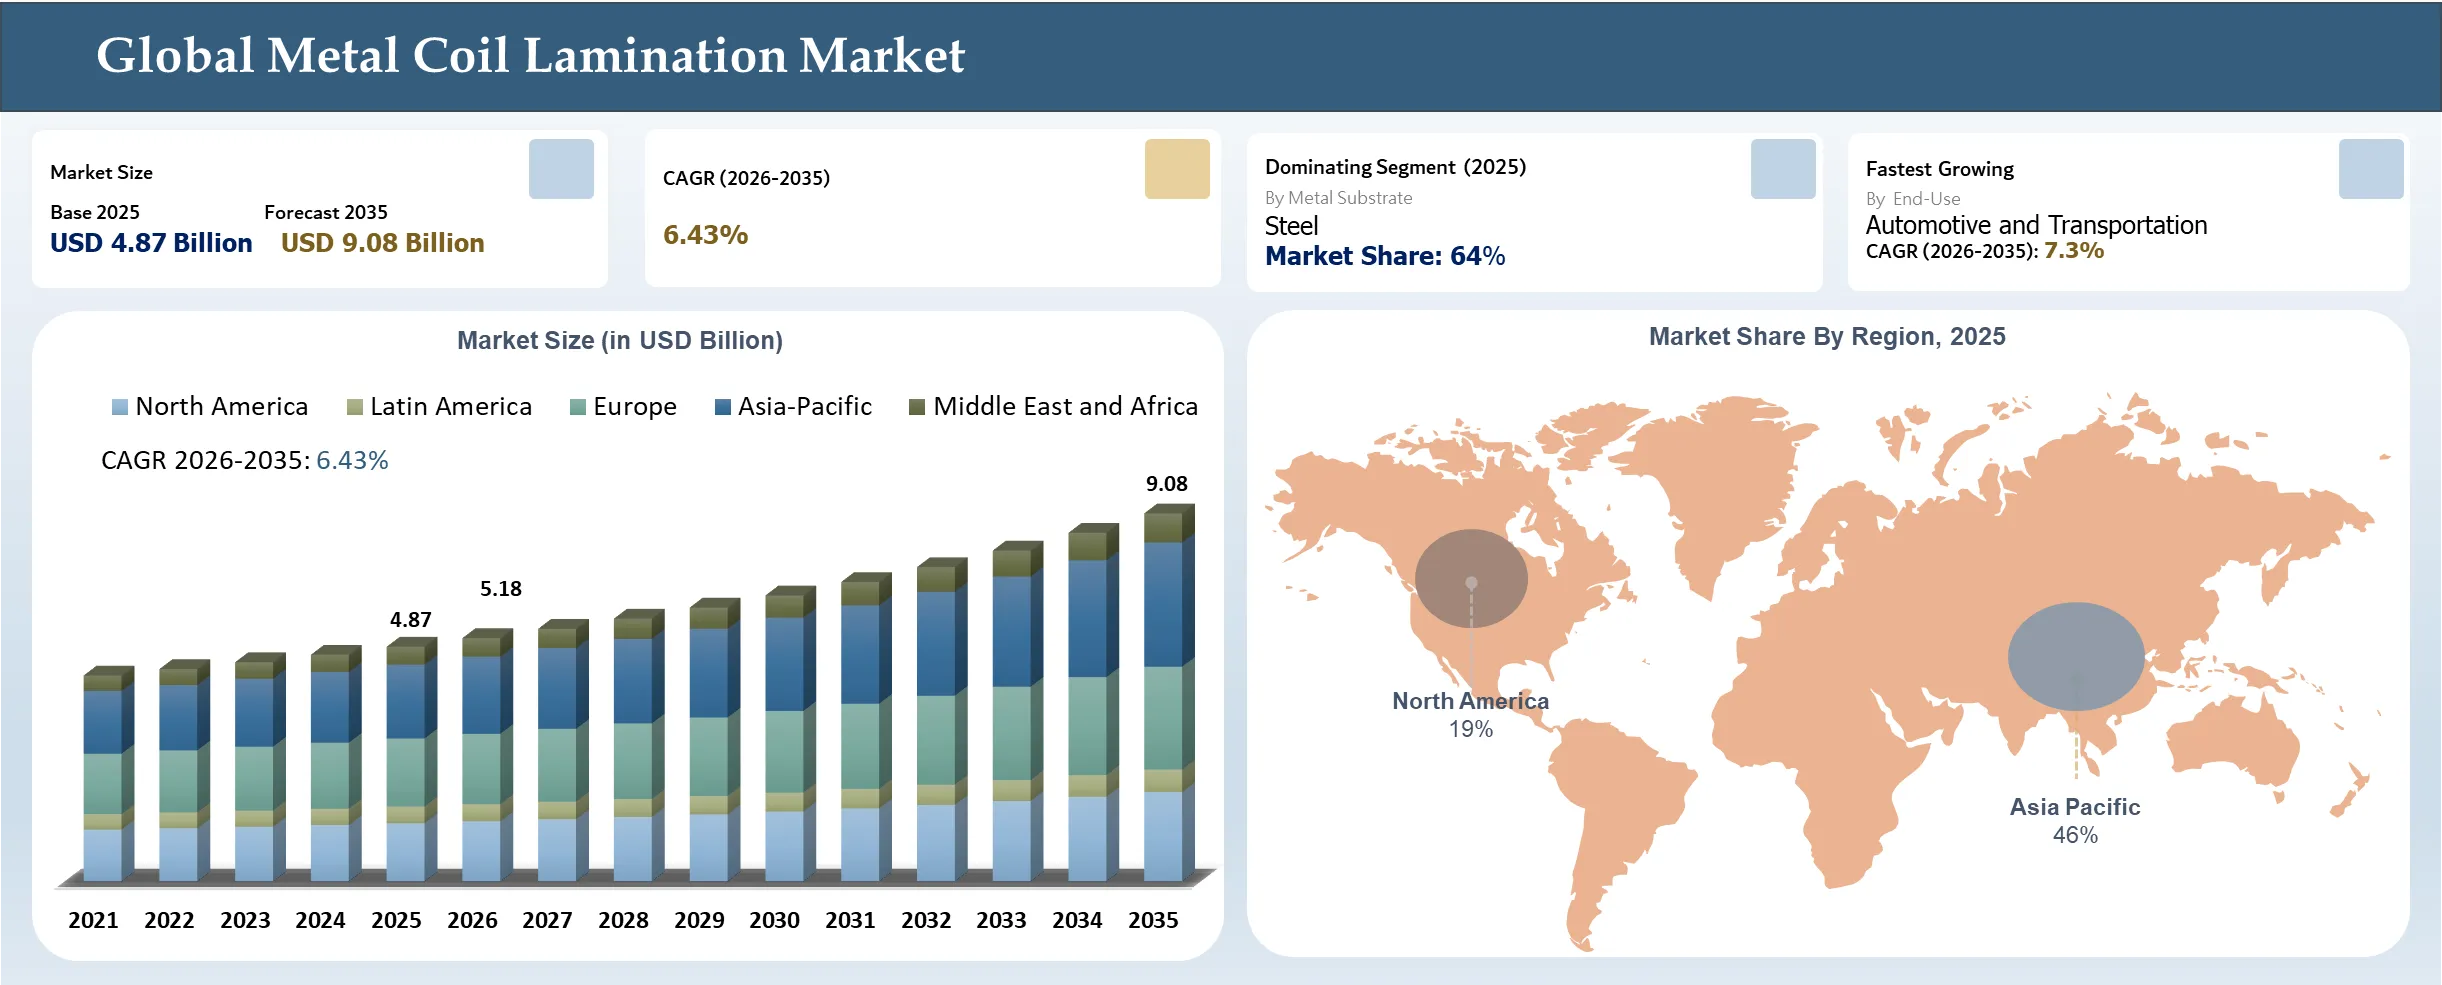
The global metal coil lamination market was valued at USD 4.87 billion in 2025 and is projected to reach USD 9.08 billion by 2035, growing at a CAGR of 6.43% from 2026 to 2035. The market expansion is supported by increasing demand for pre-laminated steel and aluminium coils used in building facades, roofing panels, household appliances, automotive components, and decorative metal surfaces. Film-lamination technologies using polyvinyl chloride (PVC) and polyethylene terephthalate (PET) are gaining commercial relevance as manufacturers seek improved corrosion resistance, scratch protection, surface durability, and decorative finishes.
Recent investments in steel manufacturing capacity are strengthening the supply of processed metal substrates required for downstream lamination applications. In November 2025, Tata Steel announced plans to transform its Kalinganagar plant in Odisha into its largest production base, targeting steel production capacity of more than 16 million tonnes per year, compared with its existing expanded capacity of 8 million tonnes per year. The company had invested approximately INR 50,000 crore (USD 5.27 billion) in the facility, increasing its capacity from 3 million to 8 million tonnes. The plant manufactures more than 100 grades of steel for automotive, infrastructure, engineering, and energy applications.
Metal Coil Lamination Market Key Takeaways
- The Asia-Pacific region led the global market in 2025 by capturing a dominant share of 46%. This strong positioning is sustained by the region's expansive steel and aluminum production hub alongside growing end-user demand.
- The World Steel Association reported global crude steel production reaching approximately 1.85 billion tonnes in 2025. China contributed 960.8 million tonnes, and India produced 164.9 million tonnes, establishing a massive substrate base for coil lamination.
- Henkel introduced a Thin Organic Coating (TOC) variant designed to form a thin surface film of only 1-2 microns. This micro-coating provides corrosion protection, adhesion, and anti-fingerprint properties on zinc- and aluminium-coated strips.
- Researchers utilizing electrical pulsed discharge (EPD) to separate multi-layer aluminum laminates achieved aluminum recovery rates of 93.6-98.7 wt%. The process consistently yielded high recovered metal purity levels spanning from 96.6 wt% to 99.7 wt%.
Metal Coil Lamination Market Trends & Disruptions Impacting Customers' Customers
Metal coil lamination manufacturers are increasingly developing multilayer polymer-film structures to improve corrosion resistance, surface durability, chemical resistance, and decorative performance across steel and aluminum substrates. On the other hand, the disruption in the metal coil lamination market is increasingly associated with the development of recyclable metal-polymer structures and advanced delamination technologies. Conventional laminated metal products combine steel or aluminum substrates with polymer films and adhesive layers, making material separation and end-of-life recycling more challenging.
In August 2025, CSIR-National Physical Laboratory published patent application IN202411004790 for a single-step recycling process designed to separate polymer layers from metal-polymer laminates through delamination and demetallization. The process uses shredded material measuring 2-4 mm, treatment temperatures of 40-60°C, and processing durations of 20-90 minutes, demonstrating a potential route for recovering polymer fractions from multilayer metal-containing materials.
Metal Coil Lamination Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) |
| Expansion of Consumer Appliance Manufacturing Increasing Demand for Decorative Laminated Coils | 25% |
| Rising Demand for Pre-Laminated Metal Sheets in Construction and Infrastructure Development | 30% |
| Growing Adoption of Lightweight Laminated Metals in Automotive Manufacturing | 15% |
Expansion of Consumer Appliance Manufacturing Increasing Demand for Decorative Laminated Coils
The expansion of refrigerator, washing machine, and air-conditioner manufacturing is strengthening demand for pre-laminated steel and aluminum coils used in decorative appliance panels, door surfaces, outer casings, and interior components. In May 2025, LG Electronics announced a USD 600 million investment in a new home-appliance factory at Sri City, India, with planned annual production capacity of 800,000 refrigerators, 850,000 washing machines, and 1.5 million air conditioners. In December 2025, Henkel introduced a new color variant of its Thin Organic Coating (TOC) technology for metal surfaces used in coil-coating processes. The coating forms a thin film of just 1–2 microns while providing corrosion protection, anti-fingerprint properties, adhesion, and lubricity on zinc, aluminum-zinc, and zinc-magnesium-aluminum-coated metal strips.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) |
| Recycling Difficulties Associated with Multi-Layer Metal and Polymer Structures | 12% |
| Complex Adhesive Bonding Requirements Increasing Film Delamination and Product Defects | 10% |
Recycling Difficulties Associated with Multi-Layer Metal and Polymer Structures
One of the major restraints affecting the metal coil lamination market is the difficulty of recycling laminated metal products that combine steel or aluminum substrates with polymer films and adhesive layers. Unlike single-material metal sheets, these structures require separation of the metal, polymer, and bonding materials before each component can be recovered. Further evidence emerged in 2026, when researchers from Waseda University, Dai Nippon Printing, and the University of Tokyo published a study in Waste Management on recovering aluminum and plastic from multilayer aluminum laminates using electrical pulsed discharge (EPD). The process achieved aluminum recovery rates of 93.6-98.7 wt% and purity levels of 96.6-99.7 wt% across successfully separated samples, while the recovered plastic resins showed almost no chemical changes.
Metal Coil Lamination Market: Commercial Use Cases Across Industries
| COMPANY | USE CASE | BENEFITS |
| ArcelorMittal supplies metallic-coated and thin-organic-coated steel solutions, including its Easyfilm range, for domestic appliances such as washing machines, dryers, dishwashers, and refrigerators, as well as construction applications including roofing, cladding, and structural components. These pre-treated metal surfaces provide a functional and decorative alternative for downstream metal processing. | Improves corrosion protection, surface durability, and processability; supports decorative finishing and reduces the need for additional surface-treatment operations; provides suitable metal surfaces for appliance and construction component manufacturing. |
 | Tata Steel supplies pre-finished and laminated steel products for domestic appliances, HVAC equipment, furniture, doors, windows, and other manufactured goods. Its Motiva range serves appliance manufacturers, while its Protact laminated steel is used in high-performance metal packaging applications. The company also operates film-lamination capabilities through its dedicated production line for packaging steel. | Provides ready-to-process metal surfaces with consistent aesthetics, formability, and surface protection; reduces downstream finishing requirements; supports efficient appliance manufacturing and enables film-laminated steel applications in packaging. |
Market Ecosystem
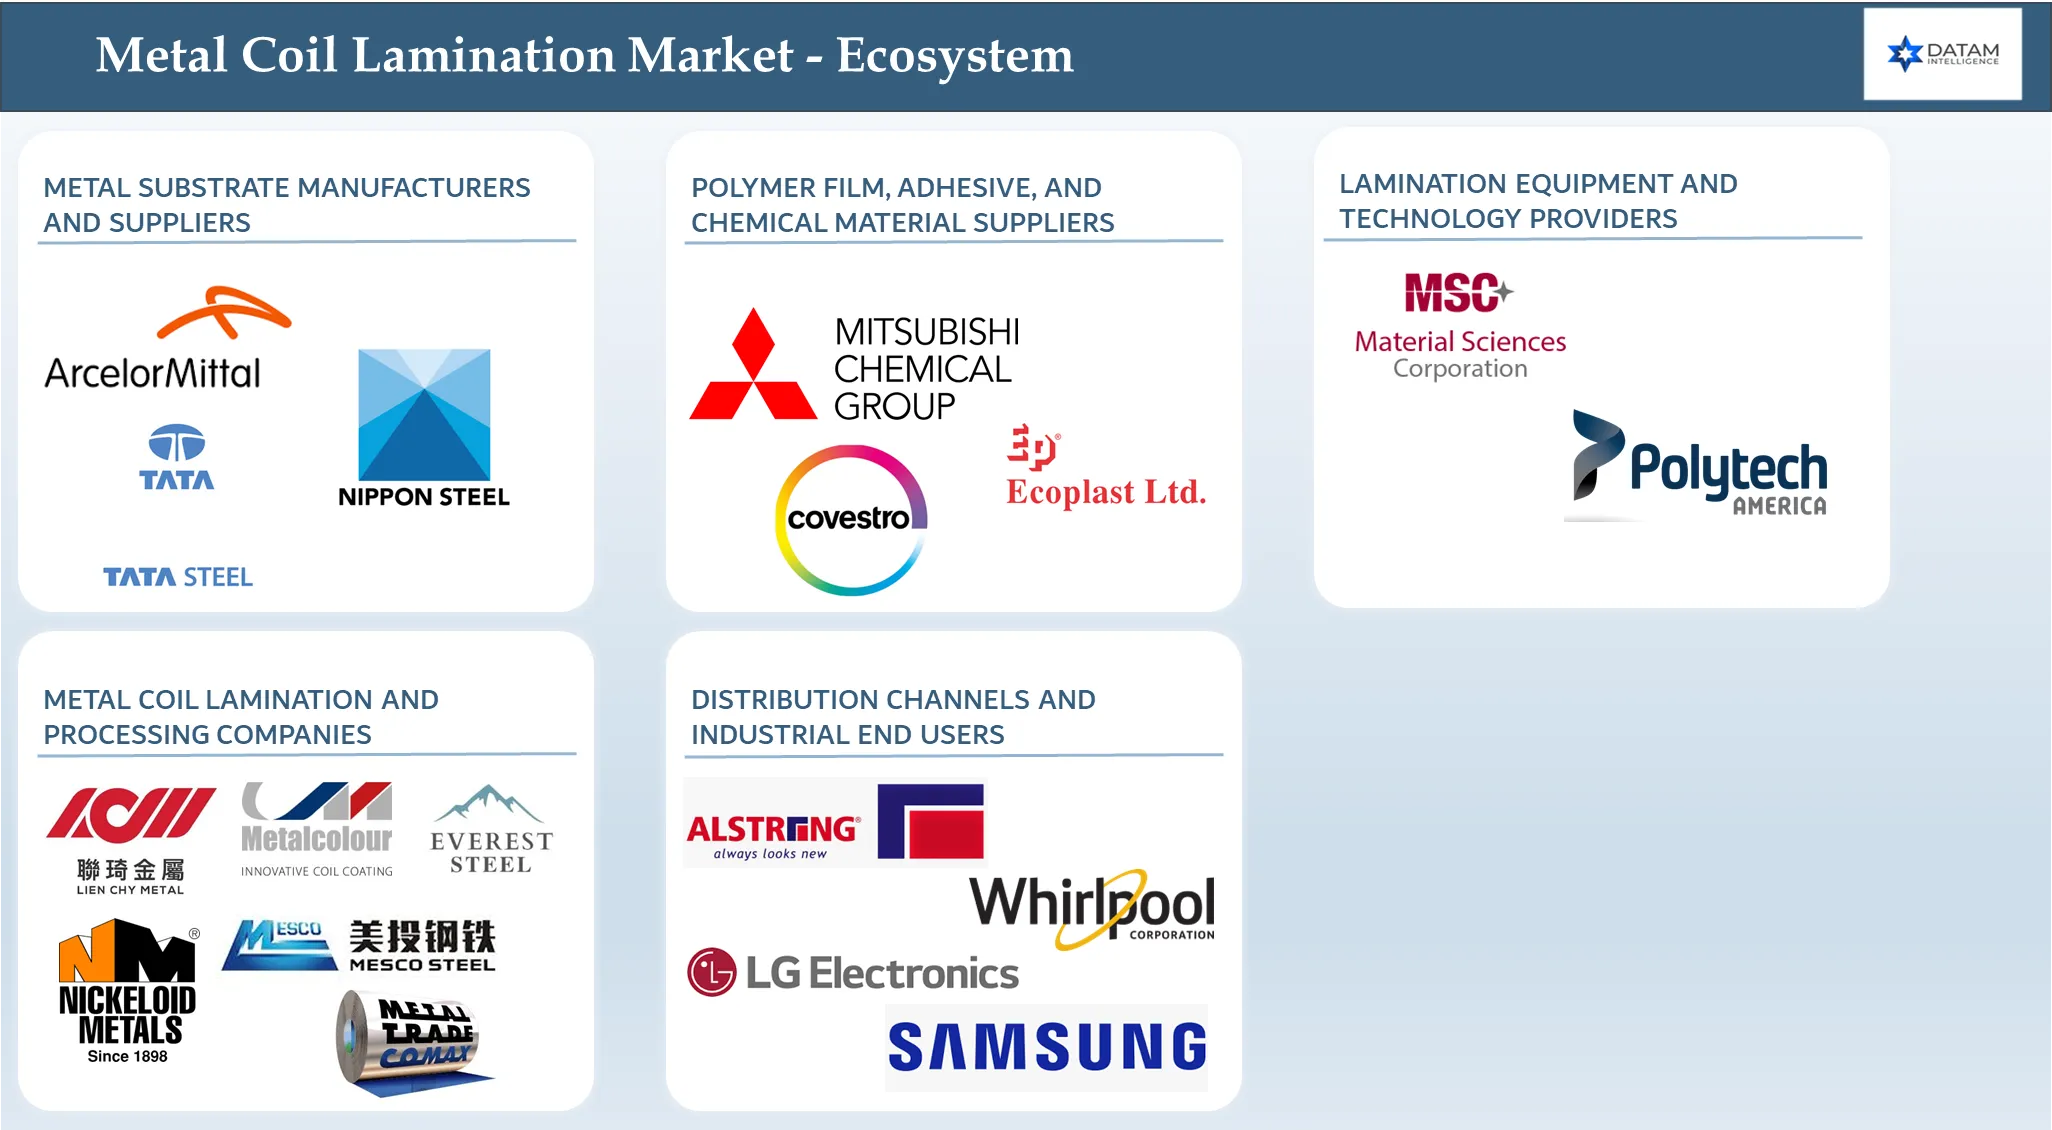
The metal coil lamination market operates through an integrated value chain involving metal producers, polymer-film and adhesive suppliers, specialized lamination companies, processing-equipment manufacturers, downstream fabricators, and end-use industries. Steel and aluminum producers supply cold-rolled, galvanized, stainless-steel, and aluminum coil substrates, while film and chemical suppliers provide PVC, PET, PP, PVF films, primers, and bonding adhesives.
Specialized laminators use continuous roll-to-roll lines to clean and pretreat metal surfaces, apply adhesives, bond decorative or protective films, and complete cooling, inspection, slitting, and cutting operations. According to the World Steel Association, the scale of the upstream supply base is significant: global crude steel production reached approximately 1.85 billion tonnes in 2025, with China producing 960.8 million tonnes and India 164.9 million tonnes, supporting the availability of metal substrates for downstream value-added processing.
Metal Coil Lamination Market Segment Analysis
By Metal Substrate
The metal coil lamination market is segmented by metal substrate into steel, stainless steel, aluminum, and other metals. Steel represents an important substrate due to its widespread availability, cost-effectiveness, structural strength, and extensive use in construction, household appliances, automotive components, and industrial equipment. Aluminum is gaining attention because of its lightweight characteristics, corrosion resistance, and suitability for transportation, architectural, and decorative applications.
By Lamination Film Material
Based on lamination film material, the market is categorized into PVC films, PET films, PP films, PVF films, and other polymer films. Polymer films play an important role in determining the surface appearance, durability, flexibility, chemical resistance, and protective performance of laminated metal products. Demand is supported by manufacturers seeking decorative and functional metal surfaces for construction materials, consumer appliances, transportation components, and industrial applications.
By Technology
The metal coil lamination market is segmented by technology into thermal lamination, adhesive lamination, extrusion lamination, and other lamination technologies. These processes determine how polymer films are bonded to metal substrates and influence production efficiency, adhesion strength, surface consistency, and final product performance.
By Thickness
Based on thickness, the market is divided into below 0.3 mm, 0.3–1 mm, and above 1 mm. Metal substrate thickness influences the flexibility, structural strength, formability, handling characteristics, and application suitability of laminated metal products. Thin laminated metal structures are relevant for applications requiring lightweight materials and complex forming operations, while medium-thickness products offer a balance between flexibility, durability, and mechanical strength.
By End-User
Based on end-use, the Metal Coil Lamination Market is categorized into building and construction, consumer appliances, automotive and transportation, electrical and electronics, furniture and interior design, industrial manufacturing, and other industries. Building and construction represents an important application area because laminated metal products provide decorative finishes, surface protection, and durability for architectural components. Consumer appliance manufacturers utilize laminated metal surfaces to improve product appearance and resistance to scratches, fingerprints, and everyday wear.
Metal Coil Lamination Market Geographical Penetration
Asia-Pacific's Strong Metal Production Base and Expanding Industrial Demand Strengthen Its Dominance in the Metal Coil Lamination Market
The Asia-Pacific region dominates the metal coil lamination market, accounting for an estimated 46% market share in 2025, supported by its extensive steel and aluminum production base, expanding manufacturing activity, and demand from construction, consumer appliances, automotive, and industrial equipment industries. China, India, Japan, South Korea, and Southeast Asian countries provide a strong ecosystem of metal substrate producers, film and adhesive suppliers, and downstream manufacturers.
For example, in April 2025, Tata BlueScope Steel launched PRISMA, a pre-painted steel solution made from 55% aluminium-zinc alloy-coated steel coils, designed for customized roofing and cladding applications. The product features a high-gloss finish, scratch resistance, and cool-comfort technology to support thermal efficiency in buildings. Its application in roofing, cladding, and industrial structures demonstrates the growing adoption of value-added coated steel solutions in India's construction sector.
Metal Coil Lamination Market BCG Matrix: Company Evaluation
Lienchy Laminated Metal Co., Ltd., a leading specialised player in the metal coil lamination market, offers a portfolio of laminated metal products with decorative finishes and protective polymer films for applications in building materials, consumer appliances, furniture, and interior design. The company strengthens its market position through specialised metal lamination capabilities, customised surface solutions, and a focus on improving the durability, appearance, and functionality of metal substrates. Another significant player in the market is Nippon Steel, positioned in the Potential category. The company leverages its extensive steel manufacturing capabilities, advanced surface-treatment technologies, and value-added steel product portfolio to serve construction, automotive, appliance, and industrial customers.
Metal Coil Lamination Market Competitive Landscape
Key Market Players
- ArcelorMittal (Luxembourg)
- Tata Steel (India)
- Nippon Steel (Japan)
- Lienchy Laminated Metal Co., Ltd. (Taiwan)
- Metalcolour A/S (Denmark)
- Material Sciences Corporation (United States)
- American Nickeloid Company (United States)
- Polytech America, LLC (United States)
- Mitsubishi Chemical Corporation (Japan)
- Everesteel (Taiwan)
- MESCO (Japan)
- METAL TRADE COMAX, a.s. (Czech Republic)
Metal Coil Lamination Market Scope
| Metrics | Details |
| 2025 Market Size | USD 4.87 Billion |
| 2035 Projected Market Size | USD 9.08 Billion |
| CAGR (2026-2035) | 6.43% |
| Years Considered | 2025 - 2035 |
| Base Year | 2025 |
| Forecast Period | 2025 - 2035 |
| Units Considered | Value (USD Billion) |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth |
| Segments Covered |
|
| Region Covered | North America, Europe, Asia-Pacific, Latin America, Middle East and Africa |
Metal Coil Lamination Market: Target Audience and Strategic Intelligence Requirements
Addressing Client Priorities Through Customized Metal Coil Lamination Research
CLIENT REQUIREMENT | RESEARCH CUSTOMIZATION PROVIDED | STRATEGIC VALUE TO CLIENTS |
Evaluating regional manufacturing and investment opportunities | Mapped metal coil lamination production capabilities, steel and aluminum substrate availability, polymer-film suppliers, and downstream manufacturing clusters across Asia-Pacific, Europe, North America, Latin America, and the Middle East & Africa. | Supports regional expansion decisions, manufacturing localization, sourcing strategies, and investment planning while improving supply-chain efficiency and market accessibility. |
Evaluating capacity expansion and manufacturing technology investments | Assessed continuous coil lamination lines, thermal and adhesive lamination technologies, extrusion processes, automation, production throughput, quality-control systems, and opportunities for manufacturing-line modernization. | Helps clients evaluate capital expenditure priorities, improve operational efficiency, increase production consistency, and scale manufacturing capabilities. |
Key Developments
- March 2026: WEG S.A., a Brazil-based multinational electrical equipment and industrial coatings manufacturer, launched Duracoil, a new coating product line for steel and aluminum coils.
- January 2026: PRO-SET Formulated Resin Systems, LLC (U.S.), a specialty formulated resin systems manufacturer, acquired Universal Chemicals & Coatings, Inc. (UNICHEM) (U.S.), an industrial coating, laminating adhesives, and coil-applied coating manufacturer headquartered in Elgin, Illinois.
- November 2025: Shandong Shinmade Technology Materials Co., Ltd., a China-based steel manufacturer specializing in cold-rolled, galvanized, and pre-painted steel coils, partnered with Primetals Technologies, a UK-based metallurgical engineering, plant technology, and automation solutions provider, to develop an intelligent electrical control and automation system for a 1,450 mm six-stand pickling and cold-rolling production line.
- April 2025: Novelis Inc., a U.S.-based global aluminum rolling and recycling company, selected Pesmel Oy, a Finland-based industrial automation and material-handling solutions provider, to supply an automated coil packing line for its new aluminum rolling and recycling facility in Bay Minette, Alabama.
- March 2025: The Sherwin-Williams Company, a U.S.-based global manufacturer and supplier of paints, coatings, and specialty industrial coating solutions, completed the acquisition of Shingels S.A., a Spain-based manufacturer and supplier of aluminum coil coatings and industrial paints.
- November 2025: Manaksia Coated Metals & Industries Limited, an India-based manufacturer and exporter of pre-painted steel coils, Alu-Zinc coated steel coils, and galvanized steel products, signed Memorandums of Understanding (MoUs) worth INR 500 crore (USD 52.75 million) with European clients for supplying up to 50,000 metric tonnes of coated steel products over the following 12 months.