


MENA Data Center Cables & Wires Market Size and Overview
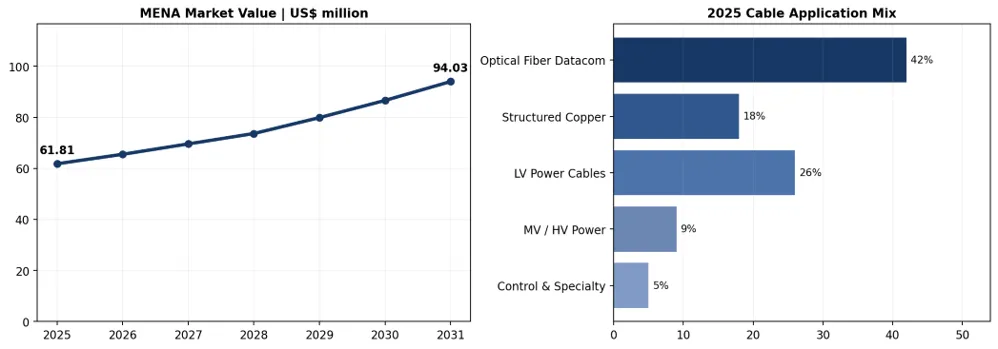
The MENA Data Center Cables & Wires Market was valued at US$ 61.81 million in 2025 and is projected to reach US$ 94.03 million by 2031, with 7.24% annualized growth across the forecast period. Coverage spans 16 markets: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain, Egypt, Iran, Iraq, Israel, Algeria, Morocco, Tunisia, Jordan, Lebanon and Yemen. Product demand comprises structured copper networks, fiber-optic links, low- and medium-voltage power cables, control wiring and specialty cable assemblies deployed in data-center campuses.
Saudi Arabia and UAE generate core Gulf demand from hyperscale, sovereign AI and cloud infrastructure development. Egypt and Morocco are attracting additional cloud and digital-infrastructure investment, while Qatar, Bahrain and Oman sustain targeted carrier, enterprise and colocation projects. Grid-connection availability, fiber-route diversity, heat resilience and locally qualified electrical contractors shape procurement decisions across different MENA markets.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 61.81 Million | US$ 94.03 Million | 7.24% |
MENA Data Center Cables & Wires Key Takeaways
The MENA Data Center Cables & Wires Market expands from US$ 61.81 million in 2025 to US$ 94.03 million by 2031, representing an additional US$ 32.22 million in annual demand.
The 7.24% annualized growth outlook reflects AI-ready networks, new colocation developments, cloud regions and higher resilient-power requirements.
Saudi Arabia and UAE concentrate major planned campus opportunities, while Egypt and Morocco provide additional regional corridors for new cloud and data-center capacity.
High-density fiber, low-loss pre-terminated trunks and modular connectivity systems support high-speed east-west traffic and expanding AI computing clusters.
A/B power-feed cabling, compliant low-smoke products and robust containment designs remain essential procurement requirements for uptime-sensitive facilities.
Project timing, electrical-grid readiness, importer qualification and availability of certified installation partners vary substantially among the 16 countries.
MENA Data Center Cables & Wires Industry Trends and Strategic Insights
AI compute expansion favors high-count optical-fiber trunks, low-loss interconnects and compact connectorized cabling to scale high-density network architectures.
Campus resilience increases requirements for segregated A/B power feeders, fire-performance cables, screened controls and traceable installation testing.
Prefabricated power and network cable packages help meet compressed construction schedules, especially for modular halls and phased hyperscale builds.
Local approvals, certified contractors and country-specific data sovereignty rules influence equipment lists, purchasing cycles and deployment footprints.
MENA Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 61.81 Million |
| 2031 Projected Market Size | US$ 94.03 Million |
| CAGR (2026–2031) | 7.24% |
| Geographic Coverage | 16 MENA markets: 6 MENA countries plus Egypt, Iran, Iraq, Israel, Algeria, Morocco, Tunisia, Jordan, Lebanon and Yemen |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
The study encompasses Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain, Egypt, Iran, Iraq, Israel, Algeria, Morocco, Tunisia, Jordan, Lebanon and Yemen. Coverage includes fiber-optic and copper datacom networks, low-/medium-voltage distribution, control and monitoring cable systems, installation format, conductor construction, insulation and data-center end-user/application types. Other MENA markets are outside the quantified market coverage.
MENA Data Center Cables & Wires Market White Space & Investment Opportunities
High-density optical networking: New hyperscale and AI halls create demand for factory-tested fiber trunks, scalable optical distribution and low-loss interconnect solutions.
Resilient electrical distribution: Dual-path LV and MV feeders, fire-rated cabling and qualified installation create opportunities in campus construction and upgrades.
Regional fulfillment and service: Country-level inventory, trained installers, onsite acceptance testing and local project intelligence can distinguish capable cable vendors.
Saudi Arabia, UAE, Egypt and Morocco offer different development cycles and sourcing ecosystems. Early engagement with owner-operators, EPC/MEP firms, network system integrators and electrical contractors is especially important when technical approvals precede the full campus buildout.
Driver Impact Analysis
New cloud regions, sovereign AI projects and hyperscale demand increase the need for optical trunks, high-reliability power feeders and structured copper links. Major Saudi and UAE developments provide opportunities for scalable, repeated cable packages across multiple data halls.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| AI and hyperscale construction | High-density fiber, LV/MV feeders and A/B power routes | High | Engage campus owners and major electrical EPC/MEP firms early. |
| Cloud-region rollout | Carrier fiber, campus trunks and structured cabling | High | Pursue repeatable regional supply packages. |
| Sovereign hosting and colocation | Redundant cabling, fire-rated materials and controls | Medium | Prequalify with hyperscale and government operators. |
| Network bandwidth upgrades | Pre-terminated optical systems and network copper | Medium | Target upgrades and brownfield extensions. |
Egyptian and Moroccan digital infrastructure investments reinforce demand for backbone fiber, campus interconnections and high-specification electrical installations. Supplier access improves through installer partnerships, approved-vendor registration, project design collaboration and localized service capability.
Restraint Impact Analysis
Grid capacity and connection lead times can delay campus execution or force staged commissioning. Additional constraints include cooling-system infrastructure, permitting, power resilience standards and the availability of installation crews skilled in mission-critical cable routing.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid access and power availability | Campus energization and new build commissioning | High | Track utility connections and phased project dates. |
| Product qualification and permits | Cable technical approvals and site installation | High | Maintain region-appropriate tests and certifications. |
| Copper, optical fiber and logistics costs | Supplier margins and schedule reliability | Medium | Provide indexed pricing and local buffer inventories. |
| Fragmented procurement and project timing | Demand conversion across 16 countries | Medium | Segment project pipelines by country and maturity. |
Fiber and conductor input cost changes, customs procedures, credit conditions and jurisdiction-specific product compliance can extend lead times or compress margins. Providers should maintain tested alternatives, transparent project milestones and disciplined price-adjustment terms.
MENA Data Center Cables & Wires Market Competitive Landscape
The competitive landscape combines regional power-cable manufacturers with global optical connectivity and structured-cabling suppliers. Riyadh Cables Group, Ducab, Elsewedy Electric and Oman Cables Industry are relevant to power infrastructure and electrical distribution, while Prysmian, Nexans, Corning, CommScope, Belden and Legrand compete across higher-specification network and facility installations.
| COMPANY | MENA DATA CENTER CABLES & WIRES POSITIONING |
| Riyadh Cables Group | Saudi power-cable producer serving electrical feeders, utility connection and large-campus infrastructure. |
| Ducab | UAE manufacturer supplying power and specialty cables for mission-critical electrical installations. |
| Elsewedy Electric | Egypt-based electrical infrastructure supplier with power distribution and regional contractor reach. |
| Oman Cables Industry | Oman-based LV/MV cable manufacturer serving utilities and high-reliability facilities. |
| Prysmian | Provider of high-density fiber, optical connectivity and power cables for digital infrastructure. |
| Nexans | International power and communications cable supplier with manufacturing presence in North Africa. |
| Corning | Fiber-optic cable, connectivity and high-density optical systems provider. |
| CommScope | Structured copper and fiber-optic cabling for enterprise and hyperscale networks. |
| Belden | Industrial and data networking cables, low-loss links and control-connectivity systems. |
| Legrand | Structured cabling, data-center connectivity and electrical infrastructure supplier. |
Competitive positioning depends on approved product catalogs, optical density, certified fire performance, availability of high-capacity LV/MV power cables, regional distributors and reliable commissioning support. Suppliers able to package fiber, controls and facility power connectivity around phased campus needs can improve project conversion.
MENA Data Center Cables & Wires Market Recent Developments
January 1, 2026 — Saudi Arabia: The Saudi Data and Artificial Intelligence Authority laid the foundation stone for its planned 480 MW Hexagon government data center in Riyadh, creating a major long-term electrical and optical infrastructure opportunity.
February 9, 2026 — UAE: Khazna Data Centers launched NexOps, an in-house operations organization supporting more than 30 data centers, strengthening standardized operations for regional hyperscale facilities.
March 4, 2026 — Product launch: Prysmian introduced Sirocco Ultra high-density optical-fiber cables for compact telecommunications and data-center connectivity applications.
April 7, 2026 — Morocco: Oracle announced the opening of its Casablanca public cloud region, hosted by N+ONE Datacenters, marking a cloud-infrastructure expansion in North Africa.
June 18, 2026 — Egypt: The ministers responsible for electricity, communications and investment coordinated preparation of a national data-center and cloud-computing strategy, including site availability, grid access and investment incentives.
July 16, 2026 — Egypt: Telecom Egypt announced it would not proceed with a proposed 75%–80% Regional Data Center Hub transaction with Helios Investments and would instead continue building a wholly owned data-center subsidiary.


























































