


Japan Cables & Wires Market Overview
The Japan cables and wires market reached US$ 14.19 billion in 2025 and is projected to reach US$ 15.79 billion by 2031, implying 1.80% annualized growth from 2025 to 2031. Coverage encompasses building and industrial wiring, medium- and high-voltage cables, optical-fiber and data cables plus specialty products for mobility, renewable energy and industrial machinery. Low-voltage products represent 45.58% of 2025 market value. Medium- and high-voltage cables contribute 36.11%.
Japanese cable demand is shaped by maintenance and replacement of mature power networks, offshore wind interconnections, factory automation, rail and transport infrastructure, semiconductor facilities plus fiber-network requirements. Product reliability and qualification remain central to purchasing decisions, particularly for high-voltage, fire-resistant and specialized industrial cabling. Manufacturers balance domestic utility specifications with export exposure and long-cycle technology investments.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 14.19 Billion | US$ 15.79 Billion | 1.80% |
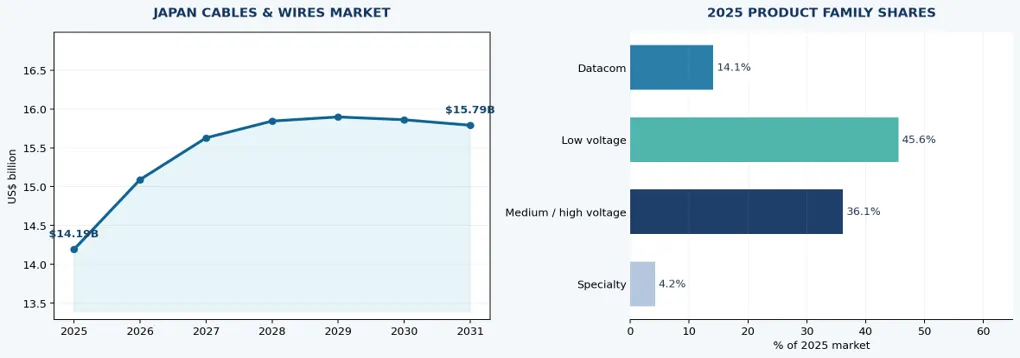
The Japan cables and wires market is projected to increase from US$ 14.19 billion in 2025 to US$ 15.79 billion in 2031, an absolute gain of US$ 1.60 billion.
The implied annualized growth rate is 1.80% between 2025 and 2031, consistent with Japan’s mature but technologically specialized demand base.
Low-voltage cables account for 45.58% of 2025 market value, reflecting building, factory and distribution installation demand.
Medium- and high-voltage cables hold 36.11% of 2025 market value, supported by transmission refurbishment, utility distribution and renewable-grid connections.
Datacom cables comprise 14.10% of 2025 market value, supporting telecom, fiber access, data centers and industrial networking.
Specialty cables constitute 4.21% of 2025 value, with demand from transport, factory automation and application-specific power systems.
Japan Cables & Wires Industry Trends and Strategic Insights
Replacement of aging transmission and distribution assets sustains demand for qualified power cables, joints and terminations. Utilities increasingly assess lifecycle performance and installation constraints.
Offshore wind installations and renewable-energy grid connection projects create opportunities for submarine, medium/high-voltage and environmental-resistant cable systems.
Semiconductor fabs, industrial robotics and advanced manufacturing require high-reliability signal, control and flexible cable products compatible with demanding installation environments.
Data centers, enterprise networks and broadband upgrades support fiber-optic and structured copper cabling, while low-smoke and fire-performance requirements influence procurement.
Japan Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 14.19 Billion |
| 2031 Projected Market Size | US$ 15.79 Billion |
| CAGR (2026–2031) | 1.80% |
| Geographic Coverage | Japan (national market and principal industrial / utility demand clusters) |
| By Cable Type | Datacom Cables (Communication & Data Cables, Fiber Optic Cables); Low-Voltage Cables (Fire Resistant Cables, Low Smoke & Halogen Free Cables, Low Voltage Cables & Wires); Medium- and High-Voltage Cables (Medium Voltage Cables, High Voltage Cables); Special Cables (Mining Oil & Gas Cables, Photovoltaic Cables, Ship & Harbour Cables, Windmill Cables) |
| By Industry | Industrial — Discrete (Aerospace & Defense, Automotive, Batteries, Electrical & Electronics, Machine Building, Semiconductor); Process (Chemicals, Energy/Oil & Gas, Metal Processing); Hybrid (Food & Beverage, Lifesciences, Mining & Quarrying, Other Manufacturing). Non Industrial — Transportation (Air, Land, Rail, Marine Services); Infrastructure & Services (Commercial Real Estate, Data Centers, Healthcare, Hospitality & Entertainment, Public Sector/Research/Education, Residentials, Water & Waste, Others). Power Utilities — Power Generation (Coal, Conventional Excl. Coal, Renewables); Power Distribution & Transmission. |
| By Conductor / Transmission Medium | Copper; Aluminum; Optical Fiber; Composite / Hybrid Construction |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (above 1 to 35 kV); High Voltage (above 35 to 230 kV); Extra-High Voltage (above 230 kV) |
| By Insulation and Sheathing Material | Cross-Linked Polyethylene (XLPE); Polyvinyl Chloride (PVC); Ethylene Propylene Rubber (EPR/EPDM); Polyethylene (PE); Low Smoke Zero Halogen (LSZH); Other Materials |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, recent developments and partnerships |
| Market Data Coverage | Cable-type and cable-subtype market values, 2025–2031 (US$ million); industry, material, voltage and installation breakdowns within the defined report scope |
The study covers Japan’s cable and wire revenue by product family with multilevel segmentation across industrial, non-industrial and power-utility end markets. Complementary breakdowns address conductor medium, voltage rating, insulation material and installation method, enabling equipment specification and procurement comparisons.
Japan Cables & Wires Market White Space & Investment Opportunities
Grid refurbishment and renewables: Modernization of power distribution, offshore wind landfalls and interconnectors creates opportunities in high-specification cable systems, accessories and installation services.
Industrial automation: Machine tools, electronics fabrication and robotics facilities favor flexible, shielded, fire-resistant and other purpose-built cable configurations.
Digital infrastructure: Fiber upgrades, high-density networking and resilient data-center power distribution provide opportunities for qualified communications and power cable suppliers.
Japan’s principal cable demand clusters include the Tokyo metropolitan region, Kansai and Chubu industrial corridors, where power distribution, transport and manufacturing infrastructure overlap. Hokkaido and northern/coastal locations offer renewable-grid and submarine-cable opportunities. Regional demand also reflects utility replacement cycles, logistics costs, project specifications and installation labor availability.
Driver Impact Analysis
Japan’s power cable requirements stem from scheduled replacement of aging assets, resilience investment, system reinforcement and connection of new generation capacity. Utilities demand proven reliability in high-voltage lines, underground applications and transmission equipment. Wind and solar interconnections influence procurement of power cables and accessories, while industrial electrification creates ongoing requirements for building wire, control systems and motor-related installations.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Grid renewal and resilience upgrades | MV/HV, utility distribution and cable accessories | Moderate | Develop long-term utilities and contractor qualification. |
| Renewables and offshore wind | Submarine, offshore and grid cables | Moderate–High | Coordinate with renewable EPC and grid connection projects. |
| Advanced industry and factory automation | Flexible, shielded and control wiring | Moderate | Target machinery suppliers and manufacturing upgrades. |
| Fiber and digital networks | Optical fiber and structured copper | Moderate | Engage datacenter integrators and network owners. |
Commercial opportunities depend on multiyear utility capital budgets, infrastructure procurement cycles and approvals for high-specification equipment. Long-term relationships with utilities, electrical contractors and engineering firms matter because qualification and project execution often take precedence over lowest upfront cost. Industrial and datacom sales also benefit from early engagement with factory planners, network integrators and equipment manufacturers.
Restraint Impact Analysis
Copper and aluminum input-cost variability affects the price of standard power cables and the working capital required for inventory. Labor shortages, specialized installation capacity and lengthy product qualification can constrain infrastructure project execution. Domestic manufacturing costs and competition from imported standardized cables place pressure on margins, although safety, reliability and test performance help differentiate sophisticated products.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Copper and aluminum price changes | Materials margins, quotations and working capital | High | Use transparent index-linked procurement terms. |
| Long product qualification cycles | Power utilities and specialty cable acceptance | Moderate–High | Invest in testing, standards and early technical engagement. |
| Project scheduling and installation constraints | Offshore, underground and transmission projects | Moderate–High | Plan lead times and installation partnerships. |
| Cost competition for standardized wire | Low-voltage and basic industrial cabling | Moderate | Differentiate through quality, support and high-value products. |
Further challenges include permitting and grid-connection delays for offshore wind or major transmission projects, high logistics costs for heavy cables and uneven demand across end markets. Suppliers can reduce exposure through index-linked quotations, diversified industrial accounts, qualification investment, design-stage project engagement and coordination with installation partners. Capacity planning is especially important for high-voltage and submarine cable lines where lead times can be substantial.
Japan Cables & Wires Market Competitive Landscape
The Japanese cables and wires market includes integrated power and telecommunications cable groups alongside specialists in industrial, electronics and high-performance wire products. Competitors range from Sumitomo Electric, Furukawa Electric and Fujikura to focused manufacturers of transmission equipment, factory automation cables and specialty wiring. Competitive differentiation centers on engineering, reliability, certifications, customer qualification and long-term project delivery capability.
| COMPANY | JAPAN CABLES & WIRES POSITIONING |
| Sumitomo Electric Industries | Broad power, automotive, industrial and optical-fiber cable portfolio. |
| Furukawa Electric | Power and fiber-optic cables with utility and digital-infrastructure capabilities. |
| Fujikura | Optical fiber, data connectivity and electronics-oriented cable technologies. |
| SWCC Corporation | Power cables and high-voltage cable-system engineering. |
| Proterial | Specialty materials and industrial cable solutions. |
| Tatsuta Electric Wire and Cable | Industrial and electronic wire with tailored application designs. |
| Mitsubishi Cable Industries | Industrial, power and specialty cable manufacturing. |
| J-Power Systems | High-voltage power cable systems and utility transmission solutions. |
| Oki Electric Cable | Signal, control and industrial cable solutions. |
| Taiyo Cabletec | Flexible and specialized cables for machinery and facilities. |
Suppliers compete through high-voltage cable technologies, fiber-optic production expertise, fire-performance materials and integrated connector/cable solutions. Utility contracts favor established testing credentials and performance history, while industrial buyers value customization and dependable delivery. Offshore wind, energy transition infrastructure and advanced manufacturing create potential for portfolio expansion, specialist partnerships and factory investments.
Japan Cables & Wires Market Recent Developments
2026: Power-system modernization and resilience planning continue to shape demand for replacement and higher-specification utility cables.
2026: Offshore wind and renewable-grid projects require technical preparation for submarine cable, export cable and landfall connections.
2026: Semiconductor and electronics manufacturing investment supports demand for clean, reliable factory power and control-cable systems.
2026: Data-center development and fiber-network upgrades maintain opportunities in optical, structured copper and critical-power cabling.
2026: Japanese cable producers continue to refine high-performance materials, qualification standards and specialized installation solutions.
2026: Commodity-metal price changes and construction labor availability remain important considerations for delivery schedules and quotations.


























































