


Italy Data Center Cables & Wires Market Size and Overview
The Italy Data Center Cables & Wires Market was valued at US$ 0.34 billion in 2025 and is forecast to reach US$ 0.73 billion by 2031, advancing at a CAGR of 13.25% over 2025–2031. Growth reflects expansion of hyperscale and colocation infrastructure, new AI computing capacity and the associated need for high-density fiber links, redundant power-distribution circuits and project-specific cable packages.
Milan and Lombardy remain the leading Italian data-center investment cluster, with opportunities spreading towards Rome, Turin and other connected industrial districts. Site-level demand includes incoming power connections, low-voltage distribution, optical campus backbones and structured cabling in data halls.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 0.34 Billion | US$ 0.73 Billion | 13.25% |
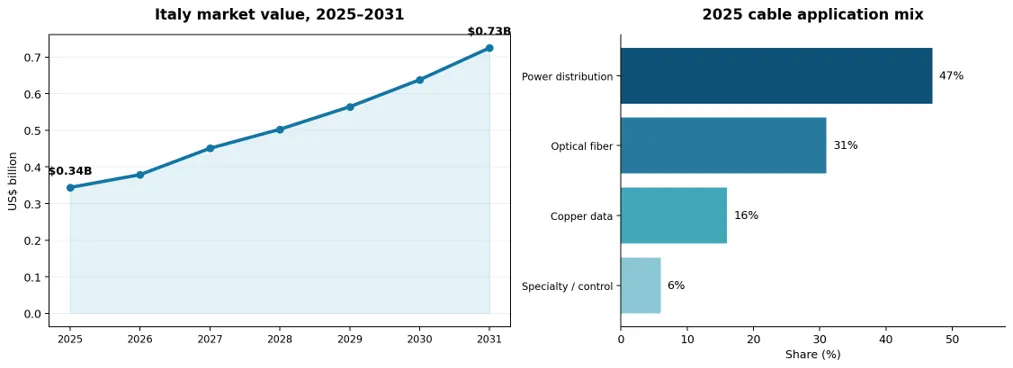
Italy Data Center Cables & Wires Key Takeaways
Italy Data Center Cables & Wires Market is valued at US$ 0.34 billion in 2025 and forecast at US$ 0.73 billion in 2031, representing 13.25% annualized growth.
The Milan metropolitan area remains a focal point for large data-center campuses, concentrated interconnection facilities and higher-density fiber procurement.
New AI and hyperscale installations require increased high-count optical-fiber connectivity, low-loss links and pre-terminated modular systems.
Redundant medium- and low-voltage distribution, UPS feeders and separated A/B routing drive demand for application-qualified power cables.
Fire safety, installation traceability and CE/CPR cable compliance influence material specification and procurement qualification.
Electricity availability and permitting can determine deployment timing, favoring suppliers with flexible schedules and qualified inventory.
Italy Data Center Cables & Wires Industry Trends and Strategic Insights
Higher-density network backbones and AI compute clusters are accelerating interest in compact optical pathways, high-count trunks and more efficient cable-management layouts.
Designs increasingly separate redundant critical-power paths and require tested low-smoke, low-halogen and fire-performance cable specifications.
Multi-phase campus builds create opportunities for pre-terminated copper and optical assemblies with repeatable site installation and commissioning quality.
Developers increasingly balance delivery lead times, copper costs, product certification and grid-connection schedules when selecting cable suppliers.
Italy Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 0.34 Billion |
| 2031 Projected Market Size | US$ 0.73 Billion |
| CAGR (2026–2031) | 13.25% |
| Geographic Coverage | Italy: Lombardy / Milan, Rome / Lazio, Turin / Piedmont and other emerging locations |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
Coverage includes power-distribution and data-transmission cabling in hyperscale, colocation, enterprise and edge data-center facilities. Segmentation spans cable type, data-center format, transmission medium, voltage rating, insulation, installation method and end-use industry.
Italy Data Center Cables & Wires Market White Space & Investment Opportunities
High-density optical connectivity: Expanding AI clusters open a route for miniaturized fiber cable, pre-terminated trunks and low-loss connectivity packages.
Grid-to-data-hall distribution: New campuses require medium-voltage supply connections, low-voltage distribution, UPS circuits and resilient feeder routing.
Modular cable procurement: Phased data-center deployment increases demand for repeatable cable packages, local logistics and commissioning documentation.
Milan, Lombardy and the emerging clusters around Rome and Turin offer opportunities for suppliers that can qualify early with electrical contractors, operators and network integrators. Project economics depend on electricity access, approved permits and phased construction.
Driver Impact Analysis
Hyperscale and colocation investment increases procurement of incoming feeders, internal power distribution and optical campus connectivity. AI-oriented facilities expand optical port counts and require higher cable densities, while dual-supply power architecture adds redundancy-driven volumes.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| AI / hyperscale expansion | Power cabling, optical fiber and campus backbones | High | Pursue data-center design and MEP specification opportunities |
| Phased large-campus development | Incoming feeders, LV distribution and interbuilding fiber | High | Coordinate project-phase cable packages with contractors |
| Fiber network densification | High-count fiber trunks, structured copper and rack links | High | Prioritize prefabricated and tested connectivity systems |
| Retrofits and redundancy | UPS circuits, control wiring and fire-rated networks | Moderate–High | Offer rapid installation, compliance documents and aftersales support |
Compact optical designs and pre-terminated components reduce installation time and improve use of constrained duct and containment spaces. Suppliers with certified product families, local staging and commissioning support can secure repeat contracts as operators scale data halls.
Restraint Impact Analysis
Available grid capacity, connection lead times and local permitting requirements can delay data-center project implementation and postpone cable purchase orders. Complex coordination between network operators, contractors and developers adds schedule uncertainty.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid connection and permitting | Large campus commissioning schedules | High | Link procurement to confirmed electrical connection milestones |
| Raw-material price variation | Copper, aluminum and specialty cables | High | Improve procurement flexibility and commercial indexation |
| Fire-safety qualification | Indoor power and networking specifications | High | Maintain verified CPR and fire-performance documentation |
| Installer and fiber-routing constraints | High-density campus deployment and retrofits | Moderate–High | Use prefabricated trunks and phased installation sequencing |
Copper-price volatility, specialized installer availability and increasingly dense electrical/fiber containment systems can increase installed costs. Fire-safety documentation, material qualification and commissioning checks create further delivery requirements.
Italy Data Center Cables & Wires Market Competitive Landscape
Italian data-center cabling is served by power-cable manufacturers, optical-fiber specialists and structured-cabling suppliers. Competition depends on fire compliance, high-density connectivity, delivery certainty, integrated project support and energy/network performance.
| COMPANY | ITALY DATA CENTER CABLES & WIRES POSITIONING |
| Prysmian | Italian headquarters; power distribution, fire-rated and high-density Sirocco optical cables |
| Nexans | Medium- and low-voltage power distribution cables for campus electrical infrastructure |
| Tratos | Italian power, fiber-optic and specialty cables for industrial and digital applications |
| La Triveneta Cavi | Low-voltage electrical distribution and building cable systems |
| Cavicel | Specialty industrial, safety and instrumentation cables for critical buildings |
| Corning | Optical-fiber platforms, structured cabling and dense data-center interconnects |
| CommScope | Structured copper and optical cabling for data halls and campuses |
| Belden | Copper/fiber connectivity and industrial-grade networking cable |
| Legrand | Data-center fiber/copper connectivity, cabinets and infrastructure |
| Schneider Electric | Critical electrical distribution systems and connected data-center infrastructure |
Companies compete through advanced optical cable density, certified electrical distribution products, installer partnerships, stocking availability and pre-terminated assemblies for large campuses.
Italy Data Center Cables & Wires Market Recent Developments
February 2026 — Regulation: Italy introduced Decree-Law No. 21/2026, establishing a streamlined authorization process for new, expanded and grid-connected data centers.
March 2026 — Product launch: Milan-based Prysmian launched Sirocco Ultra microduct cables using 160 µm optical fiber for high-density data-center, broadband and 5G networks.
March 2026 — Technology partnership: Prysmian and Relativity Networks presented next-generation hollow-core optical fiber technology designed to support hyperscale and AI networking.
June 2026 — Investment announcement: K2 Strategic presented plans for a hyperscale data-center campus south of Milan, with potential investment up to €5.3 billion and planned capacity of approximately 300 MW.
July 2026 — Regulatory implementation: Italy’s Environment and Energy Security Ministry issued operating guidance under the new unified data-center approval process introduced in February.
July 2026 — Government project designation: Italy declared two proposed data-center investment programs in Lombardy and Piedmont strategically important, with a combined announced investment value of about €8 billion.


























































