


Italy Cables & Wires Market Size and Overview
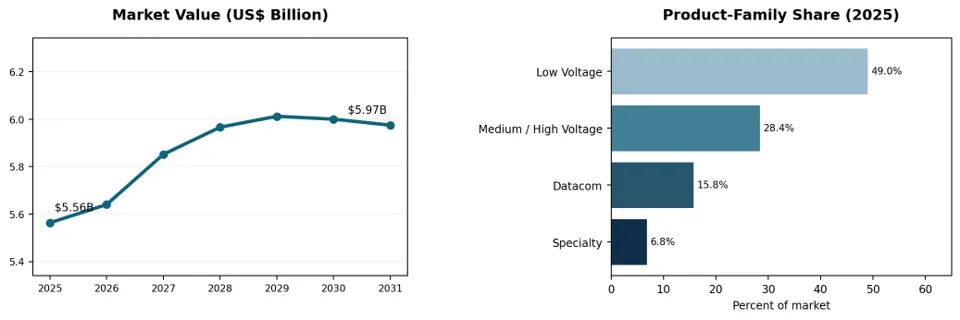
The Italy cables and wires market was valued at US$ 5.56 billion in 2025 and is projected to reach US$ 5.97 billion by 2031, representing 1.20% annualized growth during 2025–2031. The market encompasses low-voltage power distribution, medium- and high-voltage transmission, optical and copper datacom cabling and specialized industrial and marine products.
Growth opportunities in Italy are linked to Terna grid reinforcement, long-distance submarine connections, urban electricity-distribution upgrades, renewable-energy integration and modernization of industrial electrical systems. Cable demand is also supported by rail infrastructure, marine equipment, data centers and telecommunications networks. Suppliers differentiate through quality approvals, on-time delivery, specialized installation expertise and fire-performance specifications.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 5.56 Billion | US$ 5.97 Billion | 1.20% |
Italy Cables & Wires Key Takeaways
Italy market value increases from US$ 5.56 billion in 2025 to US$ 5.97 billion in 2031, an expansion of US$ 0.41 billion.
Annualized market growth is 1.20% for 2025–2031, with demand anchored in transmission interconnectors, electricity distribution, building renovation and industrial installations.
Low Voltage represented 49.05% of Italy cables and wires revenue in 2025, reflecting its roles across electricity networks, buildings, transport and communications.
Medium / High Voltage represented 28.38% of Italy cables and wires revenue in 2025, reflecting its roles across electricity networks, buildings, transport and communications.
Datacom represented 15.77% of Italy cables and wires revenue in 2025, reflecting its roles across electricity networks, buildings, transport and communications.
Specialty represented 6.80% of Italy cables and wires revenue in 2025, reflecting its roles across electricity networks, buildings, transport and communications.
Italy Cables & Wires Industry Trends and Strategic Insights
Large submarine cable projects, including connections involving Sicily and Sardinia, require high-voltage DC cable systems, marine installation services and specialized quality assurance.
Distribution-network reinforcement, renewable integration and urban electrification sustain demand for low- and medium-voltage cables, accessories and fire-safe electrical wiring.
Italian industrial clusters serving machinery, automotive, rail, shipping and automation demand flexible, shielded, high-temperature and low-smoke cable solutions.
Fiber-optic deployment, telecom backhaul and data-center networks raise demand for high-capacity optical cables and structured communications wiring.
Italy Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 7.01 Billion |
| 2031 Projected Market Size | US$ 7.55 Billion |
| CAGR (2026–2031) | 1.24% |
| Geographic Coverage | Italy (national market and principal industrial, energy and utility demand clusters) |
| By Cable Type | Datacom Cables (Communication & Data Cables, Fiber Optic Cables); Low-Voltage Cables (Fire Resistant Cables, Low Smoke & Halogen Free Cables, Low Voltage Cables & Wires); Medium- and High-Voltage Cables (Medium Voltage Cables, High Voltage Cables); Special Cables (Mining Oil & Gas Cables, Photovoltaic Cables, Ship & Harbour Cables, Windmill Cables) |
| By Industry | Industrial — Discrete (Aerospace & Defense, Automotive, Batteries, Electrical & Electronics, Machine Building, Semiconductor); Process (Chemicals, Energy/Oil & Gas, Metal Processing); Hybrid (Food & Beverage, Lifesciences, Mining & Quarrying, Other Manufacturing). Non Industrial — Transportation (Air, Land, Rail, Marine Services); Infrastructure & Services (Commercial Real Estate, Data Centers, Healthcare, Hospitality & Entertainment, Public Sector/Research/Education, Residentials, Water & Waste, Others). Power Utilities — Power Generation (Coal, Conventional Excl. Coal, Renewables); Power Distribution & Transmission. |
| By Conductor / Transmission Medium | Copper; Aluminum; Optical Fiber; Composite / Hybrid Construction |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (above 1 to 35 kV); High Voltage (above 35 to 230 kV); Extra-High Voltage (above 230 kV) |
| By Insulation and Sheathing Material | Cross-Linked Polyethylene (XLPE); Polyvinyl Chloride (PVC); Ethylene Propylene Rubber (EPR/EPDM); Polyethylene (PE); Low Smoke Zero Halogen (LSZH); Other Materials |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, market developments and partnerships |
| Market Data Coverage | Cable-family and cable-subtype market values, 2025–2031 (US$ million); segmentation, competition and market dynamics |
The Italy study covers datacom, low-voltage, medium-/high-voltage and specialty cable products. Additional segmentations examine industry, conductor / transmission medium, voltage rating, insulation and sheathing materials and installation method, alongside utility, industrial and construction applications.
Italy Cables & Wires Market White Space & Investment Opportunities
Submarine and terrestrial interconnectors: Italian grid programs create long-term opportunities for HVDC manufacturing, accessories, testing, jointing and marine-laying services.
Industrial and transport electrification: Automotive suppliers, machinery makers, rail projects and shipyards require specialized cable configurations and durable fire-performance solutions.
Digital and building infrastructure: Data centers, fiber networks, commercial retrofit and residential renovation increase opportunities for optical connectivity, copper data cabling and low-voltage distribution.
Priority demand centers include Lombardy, Veneto, Emilia-Romagna, Piedmont, Lazio, Campania, Sicily and Sardinia. Market requirements vary according to electricity grid density, industrial concentrations, subsea connection routes, construction pipelines and logistics access.
Driver Impact Analysis
Terna transmission spending and new interconnections underpin medium- and high-voltage cable requirements in Italy. Submarine cable routes connecting island and mainland grids call for technically qualified suppliers with access to specialized installation vessels and commissioning teams. Project scheduling, authorization milestones and manufacturing reservations affect how orders enter the market.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Grid reinforcement and power-system modernization | MV/HV underground and transmission cables | High | Utility qualification and contractor partnerships. |
| Renewable integration and offshore connections | HV cables, specialty and power interconnects | High | Target renewable developers, system operators and EPC firms. |
| Industrial automation and electrification | Industrial, control and low-voltage wiring | Moderate–High | Support industrial specifications and automated factories. |
| Fiber and data-center infrastructure | Optical fiber and structured copper | Moderate–High | Engage data-center integrators and network operators. |
Industrial modernization, rail investment, electrified facilities and increasing electricity demand diversify product opportunities. Italian OEMs and system integrators seek cables with high thermal tolerance, mechanical durability, electromagnetic shielding and dependable field support. Networks serving renewable generation and commercial buildings increase low- and medium-voltage demand.
Restraint Impact Analysis
Metal-price fluctuations, cable factory bottlenecks, submarine installation complexity and supply-chain concentration can affect pricing and schedules. Large marine projects are exposed to route surveys, environmental permits, coastal interfaces, weather conditions and limited vessel availability.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Copper and aluminum price fluctuations | Contract margins and inventory funding | High | Metal-index procurement and contract protection. |
| Planning and grid-project delays | Project order conversion and scheduling | High | Strengthen pipeline management and stagger capacity. |
| Testing and engineering qualification | Utilities and mission-critical products | Moderate–High | Earlier type testing and design support. |
| Cost competition in standard cable products | Basic low-voltage and building wire | Moderate | Differentiate through quality, service and specialty products. |
Low-voltage building-wire categories face intense tender and distributor competition, while high-voltage cable systems require substantial technical qualification and manufacturing lead times. Suppliers can manage risk through indexed contracts, product certification, local inventory, qualified installation partners and coordinated long-term project planning.
Italy Cables & Wires Market Competitive Landscape
Italy hosts a major international cable-manufacturing ecosystem alongside specialized domestic suppliers. Prysmian, Nexans, Tratos, La Triveneta Cavi, Cavicel, ICEL, Baldassari Cavi, Cavel, Belden and Corning represent a mix of transmission, building, industrial and datacom capabilities.
| COMPANY | Italy CABLES & WIRES POSITIONING |
| Prysmian | Italian-headquartered integrated power, submarine and telecom cable systems. |
| Nexans | International transmission and distribution cable supplier with Italian project activity. |
| Tratos | Italian manufacturer of medium-voltage, low-voltage and specialty cable systems. |
| La Triveneta Cavi | Italian producer of building, low-voltage and industrial cable products. |
| Cavicel | Italian supplier of fire-resistant and specialist industrial cables. |
| ICEL | Italian producer of insulated conductors and industrial electrical cables. |
| Baldassari Cavi | Italian cables for electrical installations, industrial and utility applications. |
| Cavel | Italian manufacturer of coaxial and communications cables. |
| Belden | Industrial communications and high-performance data-transmission cabling. |
| Corning | Fiber-optic connectivity and data cable technologies used in Italian networks. |
Competition increasingly depends on ultra-high-voltage cable engineering, submarine installation and jointing, fire safety, industrial customization, environmental performance and customer support. Domestic manufacturers contribute flexible specialty and distribution products, while multinational groups compete for high-value grid packages.
Italy Cables & Wires Market Recent Developments
January 7, 2026 — Nexans announced completion of the Tyrrhenian Link western-section HVDC submarine cable installation, following its final laying operation on January 1 and recording a 2,150 m installation depth.
February 10, 2026 — Prysmian completed the acquisition of ACSM, a subsea-cable installation, route engineering and seabed-preparation specialist, integrating it into the group from February.
April 9, 2026 — Terna announced completion of marine cable-laying works on the Campania–Sicily eastern section of the Tyrrhenian Link, with Prysmian delivering the cable system.
June 22, 2026 — Prysmian received the notice to proceed from Terna and STEG for the Italy–Tunisia ELMED submarine electrical interconnector, adding approximately €460 million to its project backlog.
August 3, 2026 — Prysmian announced an agreement to acquire Atkore, expanding its planned electrical-solutions portfolio; the announcement is distinct from transaction completion.
October 13, 2026 — Prysmian completed its acquisition of Xtera through an 80%-owned venture with Fincantieri holding 20%, extending its submarine telecom systems capabilities.


























































