


India Cables & Wires Market Size and Overview
The India cables and wires market reached US$ 11.51 billion in 2025 and is projected to reach US$ 18.36 billion by 2031, representing 8.08% annualized growth over 2025–2031. The market covers low-voltage building and industrial wiring, medium- and high-voltage electricity cables, communication and optical-fiber cables plus specialty cables. Low-voltage cables accounted for 46.18% of 2025 market value. Medium- and high-voltage cables represented 35.80%.
India’s cable demand is supported by electricity transmission and distribution investment, construction and urban infrastructure, manufacturing capacity additions, renewable-energy interconnections and broadband rollout. Purchasers increasingly assess thermal ratings, conductor efficiency, flame performance and traceability alongside total delivered cost. Large institutional and utility orders often require extended qualification, inspection and execution capacity.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
| US$ 11.51 Billion | US$ 18.36 Billion | 8.08% |
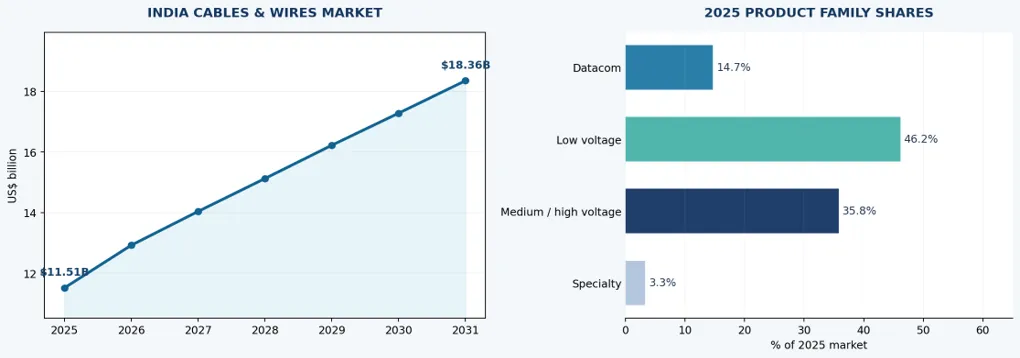
India’s cables and wires market is projected to rise from US$ 11.51 billion in 2025 to US$ 18.36 billion in 2031, a market expansion of US$ 6.84 billion.
The market represents 8.08% annualized growth over 2025–2031, with demand linked to power infrastructure, building construction and industrial investments.
Low-voltage cables represented 46.18% of 2025 market value, reflecting building electrification, factory wiring and commercial construction.
Medium- and high-voltage cables accounted for 35.80% of 2025 value, driven by grid strengthening, power evacuation and industrial distribution.
Datacom cables contributed 14.69% of 2025 market value, with uses across broadband, data centers, telecommunications and factory networking.
Specialty cables represented 3.33% of 2025 value, spanning photovoltaic, wind, mining, oil and gas, marine and other specialized applications.
India Cables & Wires Industry Trends and Strategic Insights
Grid investment is increasing demand for MV/HV power cables, underground distribution and associated accessories as utilities strengthen networks and connect renewable generation.
Urban construction, metro systems, airports and industrial parks sustain demand for certified low-voltage, fire-resistant and low-smoke cable designs.
Solar, wind and energy-storage projects favor weather-resistant, high-reliability and application-specific cables. Local suppliers can capture greater value through project qualification and installation support.
Fiber access expansion, enterprise connectivity, data-center investments and factory digitization support optical fiber and structured copper requirements.
India Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 11.51 Billion |
| 2031 Projected Market Size | US$ 18.36 Billion |
| CAGR (2026–2031) | 8.08% |
| Geographic Coverage | India (national market and major industrial, utility and infrastructure corridors) |
| By Cable Type | Datacom Cables (Communication & Data Cables, Fiber Optic Cables); Low-Voltage Cables (Fire Resistant Cables, Low Smoke & Halogen Free Cables, Low Voltage Cables & Wires); Medium- and High-Voltage Cables (Medium Voltage Cables, High Voltage Cables); Special Cables (Mining Oil & Gas Cables, Photovoltaic Cables, Ship & Harbour Cables, Windmill Cables) |
| By Industry | Industrial — Discrete (Aerospace & Defense, Automotive, Batteries, Electrical & Electronics, Machine Building, Semiconductor); Process (Chemicals, Energy/Oil & Gas, Metal Processing); Hybrid (Food & Beverage, Lifesciences, Mining & Quarrying, Other Manufacturing). Non Industrial — Transportation (Air, Land, Rail, Marine Services); Infrastructure & Services (Commercial Real Estate, Data Centers, Healthcare, Hospitality & Entertainment, Public Sector/Research/Education, Residentials, Water & Waste, Others). Power Utilities — Power Generation (Coal, Conventional Excl. Coal, Renewables); Power Distribution & Transmission. |
| By Conductor / Transmission Medium | Copper; Aluminum; Optical Fiber; Composite / Hybrid Construction |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (above 1 to 35 kV); High Voltage (above 35 to 230 kV); Extra-High Voltage (above 230 kV) |
| By Insulation and Sheathing Material | Cross-Linked Polyethylene (XLPE); Polyvinyl Chloride (PVC); Ethylene Propylene Rubber (EPR/EPDM); Polyethylene (PE); Low Smoke Zero Halogen (LSZH); Other Materials |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, recent developments and partnerships |
| Market Data Coverage | Cable-type and cable-subtype market values, 2025–2031 (US$ million); industry, material, voltage and installation breakdowns within the defined report scope |
The report covers India’s cables and wires market by cable family and subtype with industry end markets organized as Industrial, Non Industrial and Power Utilities. Complementary dimensions include conductor and transmission medium, voltage class, insulation and sheathing material and installation method. Each segmentation is consolidated within one Market Scope table row.
India Cables & Wires Market White Space & Investment Opportunities
Utility and renewable-power programs: Suppliers can target transmission reinforcement, high-capacity substations, solar parks and wind evacuation networks with qualified MV/HV cable systems.
Construction and manufacturing: Commercial buildings, housing, metro rail and industrial corridors offer demand for safe building wire, control cables and fire-performance product lines.
Digital infrastructure: Fiber broadband, high-density data centers and smart factories present opportunities in communication, optical-fiber, shielded and specialty connectivity products.
Major commercial demand corridors span Maharashtra, Gujarat, Tamil Nadu, Karnataka, Telangana and the Delhi NCR region through manufacturing, offices, digital infrastructure and construction. Utility procurement and renewable projects extend opportunities across additional states. Project timing, regulatory clearances, grid connection requirements and distribution networks shape the addressable opportunity for each cable specification.
Driver Impact Analysis
India’s cable demand benefits from reinforcement of electricity transmission and distribution systems alongside grid extensions to accommodate demand growth and renewable power. Utility and EPC buyers require consistent electrical performance, routine testing, reliable terminations and installation quality. Underground distribution, high-capacity transmission assets and power evacuation corridors create higher-value applications for medium- and high-voltage cables.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Electricity grid upgrades | MV/HV power cables and utility accessories | High | Engage utilities and EPCs at early tender and design stages. |
| Urbanization and buildings | Low-voltage, fire-resistant and LSZH wire | High | Expand specification-led channels and construction partnerships. |
| Renewables and industrial corridors | PV, wind and industrial power/control cables | High | Target developers, OEMs and project contractors. |
| Fiber networks and data centers | Optical fiber, datacom and structured copper | Moderate–High | Build relationships with telecom and digital infrastructure buyers. |
Industrial expansion, commercial buildings, rail and metro infrastructure and housing development generate requirements for low-voltage power, control and fire-safety cables. Suppliers with broad distributor reach can serve standardized building wiring, while manufacturers with technical qualification and engineering teams are better positioned for complex utility, renewable and industrial projects. Lead generation should target EPC contractors, utilities, industrial developers and large electrical distributors early in the procurement cycle.
Restraint Impact Analysis
Copper and aluminum price fluctuations are major factors affecting cable cost, inventory financing and tender profitability. Project-driven procurement can also expose suppliers to price resets between bid submission and delivery. Stringent customer testing, inconsistent specifications and rising fire-performance requirements may increase production complexity and certification costs. Imported machinery and specialized material inputs can add currency-related cost exposure.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Copper/aluminum price volatility | Cable input costs, pricing and working capital | High | Use metal-indexed quotations and inventory discipline. |
| Project permissions and contract delays | Transmission, utility and infrastructure delivery | Moderate–High | Balance EPC exposure and monitor project readiness. |
| Technical qualification and compliance | Fire-performance, HV and specialty cables | Moderate–High | Invest in certifications, inspection and testing. |
| Intense channel competition | Commodity building and low-voltage cables | Moderate | Differentiate via quality, service and dealer availability. |
Cable-market growth can also be constrained by grid-right-of-way permissions, construction delays, utility disbursement timing and uneven contractor availability. Distribution competition and counterfeit or noncompliant low-price offerings create pricing pressure in some product lines. Producers can mitigate exposure using metal-indexed commercial terms, rigorous quality assurance, reliable delivery schedules and diversified relationships across utilities, industrial customers and distributors.
India Cables & Wires Market Competitive Landscape
India’s cables and wires market combines large integrated manufacturers serving building wire and power cable demand with specialist optical-fiber, industrial and high-voltage suppliers. Polycab India, KEI Industries, RR Kabel, Havells India and Finolex Cables participate in important domestic cable and electrical distribution channels. APAR Industries, Universal Cables, JSW Cables, Sterlite Technologies and Birla Cable contribute capabilities across power transmission, industrial applications and communications cabling.
| COMPANY | INDIA CABLES & WIRES POSITIONING |
| Polycab India | Broad low-voltage and power cable portfolio with nationwide channels. |
| KEI Industries | Power cables, EHV projects and building/industrial wiring. |
| RR Kabel | Building wire, power cables and consumer-facing distribution. |
| Havells India | Flexible and building wires with established electrical channels. |
| Finolex Cables | Electrical and communications cables with industrial applications. |
| APAR Industries | Power and specialty cables serving utility and industrial projects. |
| Universal Cables | Power cable systems with industrial and high-voltage capabilities. |
| JSW Cables | Developing power cable and wire capabilities for domestic infrastructure. |
| Sterlite Technologies | Optical fiber and data connectivity products for digital infrastructure. |
| Birla Cable | Communications cables and specialty cable solutions. |
Competitive positioning depends on geographic dealer coverage, utility and EPC approvals, production capacity, product certifications, order execution and brand trust. Manufacturers targeting complex projects increasingly compete on technical design, testing, logistics and customer support, while standardized low-voltage products remain exposed to distribution intensity and copper-linked pricing. Renewable energy, power-grid investment and digital infrastructure provide potential areas for product-mix improvement.
India Cables & Wires Market Recent Developments
2026: Power transmission and distribution upgrades sustain procurement interest in high-performance cables and associated installation products.
2026: Renewable power additions and connection works support demand for solar, wind and medium/high-voltage evacuation cabling.
2026: Infrastructure construction and industrial capacity expansions continue to require certified building, control and low-voltage cables.
2026: Fiber deployment and digital-infrastructure development broaden opportunities in optical-fiber and communications cabling.
2026: Domestic manufacturers continue to emphasize capacity, product qualification, distribution expansion and higher-value cable applications.
2026: Copper and aluminum cost volatility remains relevant to working capital, tender terms and selling prices.


























































