


High Purity Alumina Market Size and Overview
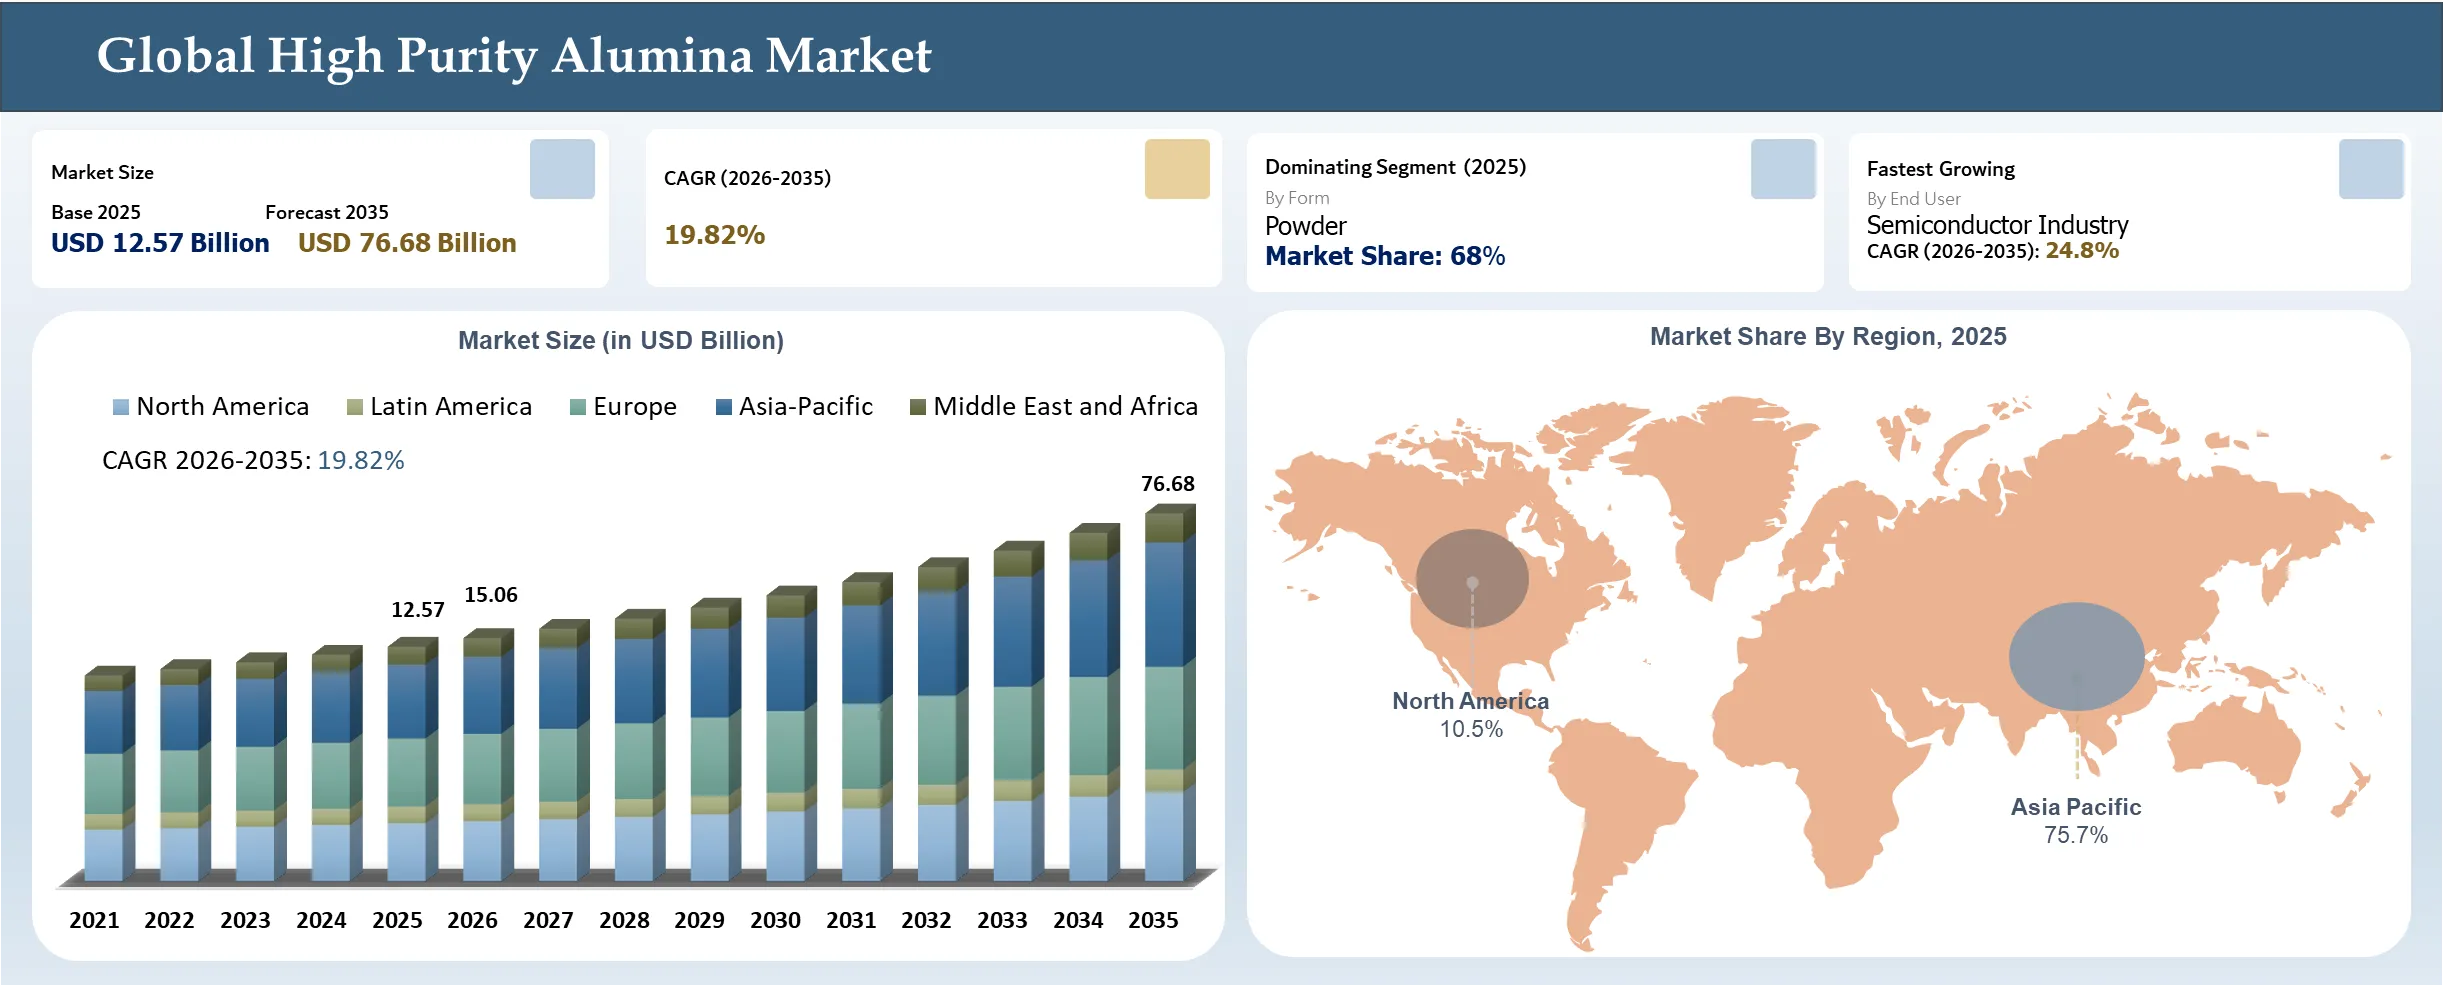
The global high-purity alumina market reached USD 12.57 billion in 2025 and is expected to reach USD 76.68 billion by 2035, growing with a CAGR of 19.82% during the forecast period 2026-2035. The market is gaining momentum from increasing requirements for ultra-high purity materials in semiconductors, lithium-ion batteries, AI-powered electronics, and manufacturing processes. In January 2026, AlphaHPA secured an investment of USD 52.7 million from Australia's National Reconstruction Fund Corporation (NRFC) for its HPA First Project at Gladstone, Queensland. It is part of a total USD 158 million (A$225 million equivalent) funding round for the development of HPA for semiconductor and lithium-ion batteries. The project will be fully powered by 100% renewable energy.
Technological development is also supporting the market by improving purity and production economics. Andromeda Metals reported advancing pilot plant technology towards commercial production and exhibiting the capacity to produce ultra-high-purity alumina, proving the feasibility of alternate sources of feedstock and local supply of HPA. Meanwhile, the process used by AlphaHPA, known as Smart SX, produces aluminium precursors and boehmite or alumina at 5N+ and 4N+, respectively, while almost 100% of process reagents are recycled.
White-Space Opportunities for Green Metals Decarbonization, Electrification, and Low-Emission Processing
In December 2025, the Australian Renewable Energy Agency (ARENA) allocated up to A$750 million (USD 526 million) through the Future Made in Australia (FMA) Innovation Fund to accelerate pre-commercial innovation, demonstration, and deployment of renewable-energy and low-emissions technologies across the Green Metals Priority, covering green iron, green steel, green alumina, and green aluminium.
The highest investment is directed toward the Green Metals area itself, with the A$750 million pool supporting first-of-a-kind solutions and commercial-scale production, including technologies for green alumina and aluminium, green iron and steelmaking, Australian iron-ore processing, and projects progressing toward final investment decisions.
Within the wider FMA Innovation Fund, additional investment areas include A$200 million (USD 140 million) initially for Renewable Energy Technology Manufacturing and A$250 million (USD 175 million) for Low Carbon Liquid Fuels, taking the overall FMA Innovation Fund to A$1.5 billion (USD 1.05 billion).
The funding is expected to create significant opportunities across the green alumina, aluminium, iron and steel technology value chains, benefiting producers, technology developers, engineering companies, R&D organisations, OEMs and industrial technology start-ups. South32 is directly positioned in the alumina-refining area through its Worsley Alumina Refinery, where it is evaluating electrification options for steam generation, creating opportunities for electric boilers, mechanical vapour recompression and other low-emissions refining technologies.
Rio Tinto, Alcoa, Queensland Alumina Limited and Nyrstar are also positioned across the alumina and aluminium decarbonisation value chain through opportunities involving renewable electricity, process electrification, low-carbon refining and energy-efficiency technologies. Element Zero is positioned in green iron through electrochemical ironmaking technology, while NewPro Consulting and Engineering Services supports engineering and technical activities associated with green-iron projects.
Fortescue, BlueScope Steel, Liberty Steel Australia and Whyalla Steelworks are positioned in green iron and green steel through opportunities involving hydrogen-based ironmaking, renewable energy, electric processing and lower-emissions steel production.
High Purity Alumina Market Key Takeaways
- The Asia-Pacific region dominated the global HPA market with a 75.7% share in 2025. Growth is driven by concentration in semiconductor, LED, lithium-ion battery, and synthetic-sapphire manufacturing.
- The powder form dominated the market in 2025, capturing a 68.0% share. Powder HPA offers engineered particle morphology, surface area, and crystallinity required across diverse high-end applications.
- AlphaHPA secured USD 52.7 million from Australia's NRFC in January 2026 as part of a total USD 158 million (A$225 million) funding package. The project focuses on 100% renewable-energy-powered HPA production for semiconductors and batteries.
- Australia’s ARENA allocated A$750 million (USD 526 million) to the Green Metals Priority within a larger A$1.5 billion (USD 1.05 billion) FMA Innovation Fund. The initiative targets pre-commercial low-emissions solutions, including green alumina and aluminium.
High Purity Alumina Market Industry Trends and Strategic Insight
- HPA is shifting from a conventional Speciality alumina material toward a strategic input for advanced technology manufacturing, particularly across semiconductors, AI-related electronics, lithium-ion batteries, LEDs, and synthetic sapphire applications.
- The market is moving toward application-specific HPA grades rather than standardized products, with producers developing controlled particle size, surface characteristics, thermal properties, and ultra-low impurity profiles to meet increasingly demanding customer specifications.
- Advanced semiconductor packaging is emerging as a higher-value growth avenue for HPA, as manufacturers require materials that combine high thermal conductivity, electrical insulation, low radiation characteristics, and dimensional control.
- Government-backed critical-mineral and green-manufacturing programs are improving the investment environment for domestic HPA projects, particularly where projects combine advanced processing, renewable energy, and downstream technology applications.
- Strategic opportunity is shifting toward specialised HPA formulations for high-growth end uses, rather than competing solely on commodity-grade purity, enabling suppliers to capture higher-value applications where material specifications are tightly linked to device performance.
High Purity Alumina Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 12.57 Billion | |
| 2035 Projected Market Size | USD 76.68 Billion | |
| CAGR (2026-2035) | 19.82% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | Asia-Pacific | |
| By Purity Level | 3N5 HPA, 4N HPA, 4N5 HPA, 5N HPA, Above 5N HPA | |
| By Form | Powder, Granules, Pellets, Slurries and Dispersions, Pucks and Tablets, Other Product Forms | |
| By End User | Semiconductor Industry, Consumer Electronics Industry, Lithium-Ion Battery Industry, Synthetic Sapphire Industry, LED and Speciality Lighting Industry, Technical Ceramics Industry, CMP and Polishing Materials Industry, Optical Components Industry, Medical and Healthcare Industry, DLE and Speciality Sorbent Industry, Other Industrial End Users | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
High Purity Alumina Market Disruption Analysis
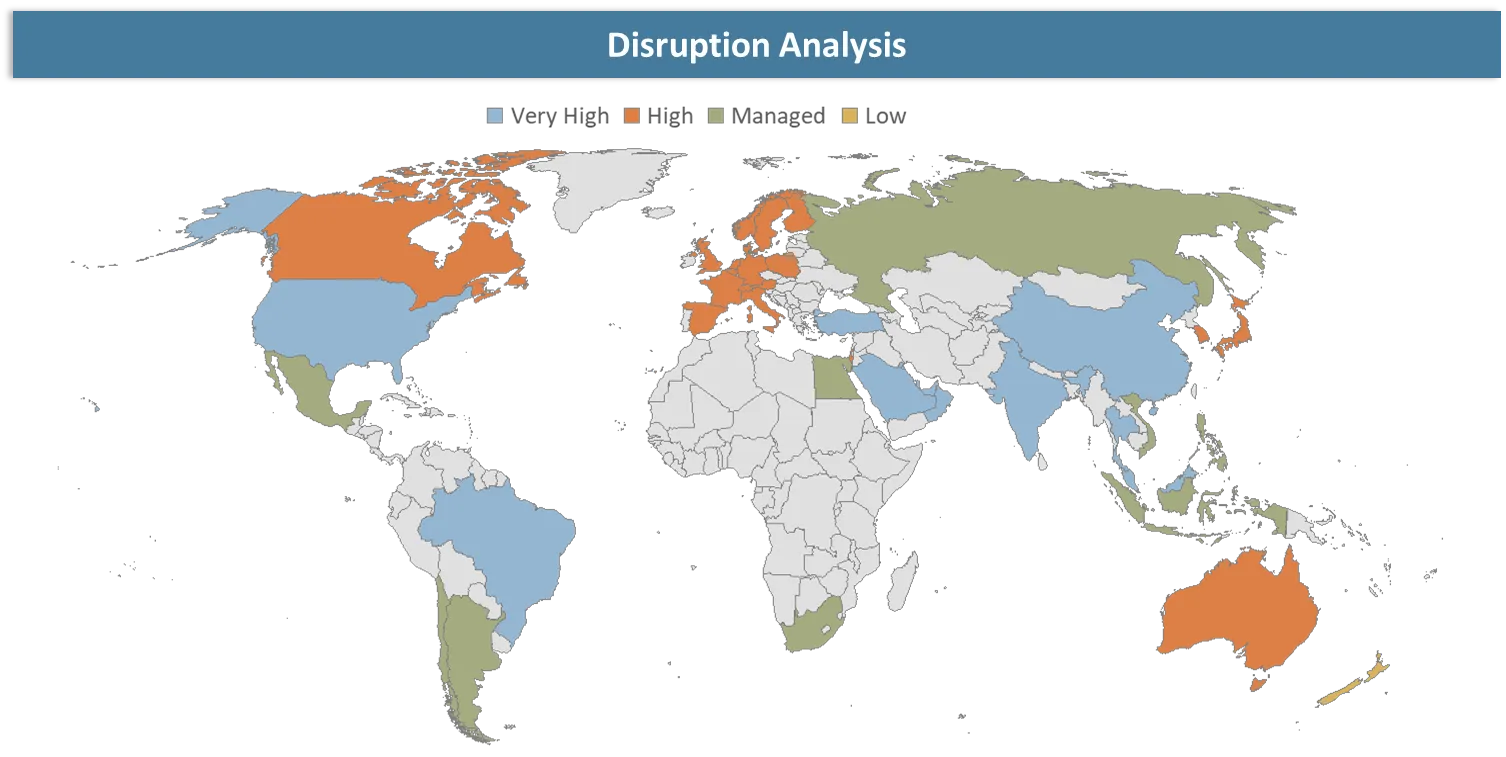
Advanced Purification Technologies Reshaping the High Purity Alumina Production Landscape
The disruption in the high purity alumina market is primarily associated with the transition from conventional alumina processing toward advanced purification technologies and alternative feedstock routes. Such technology is allowing HPA firms to utilize unconventional raw materials in their operations while being able to maintain control over their purity level and other aspects of resource usage. The process is especially important for uses in semiconductors, batteries, optical, and LED markets, which need precise control of alumina properties.
The alternative feedstock method used by Lava Blue is also creating an impact on the traditional HPA manufacturing process since HPA can now be manufactured using kaolin, red mud, and industrial waste rather than the usual alumina sources. The PRiSM pilot-scale production line in Brisbane can produce 4N and 5N HPA with a purity of up to 99.999% that can be used for battery, semiconductor, optical, and LED applications. Innovation becomes significant given that the worldwide HPA requirement is expected to surpass 240,000 tonnes per annum by 2030, with 75% of the supply coming from China.
High Purity Alumina Market BCG Matrix: Company Evaluation
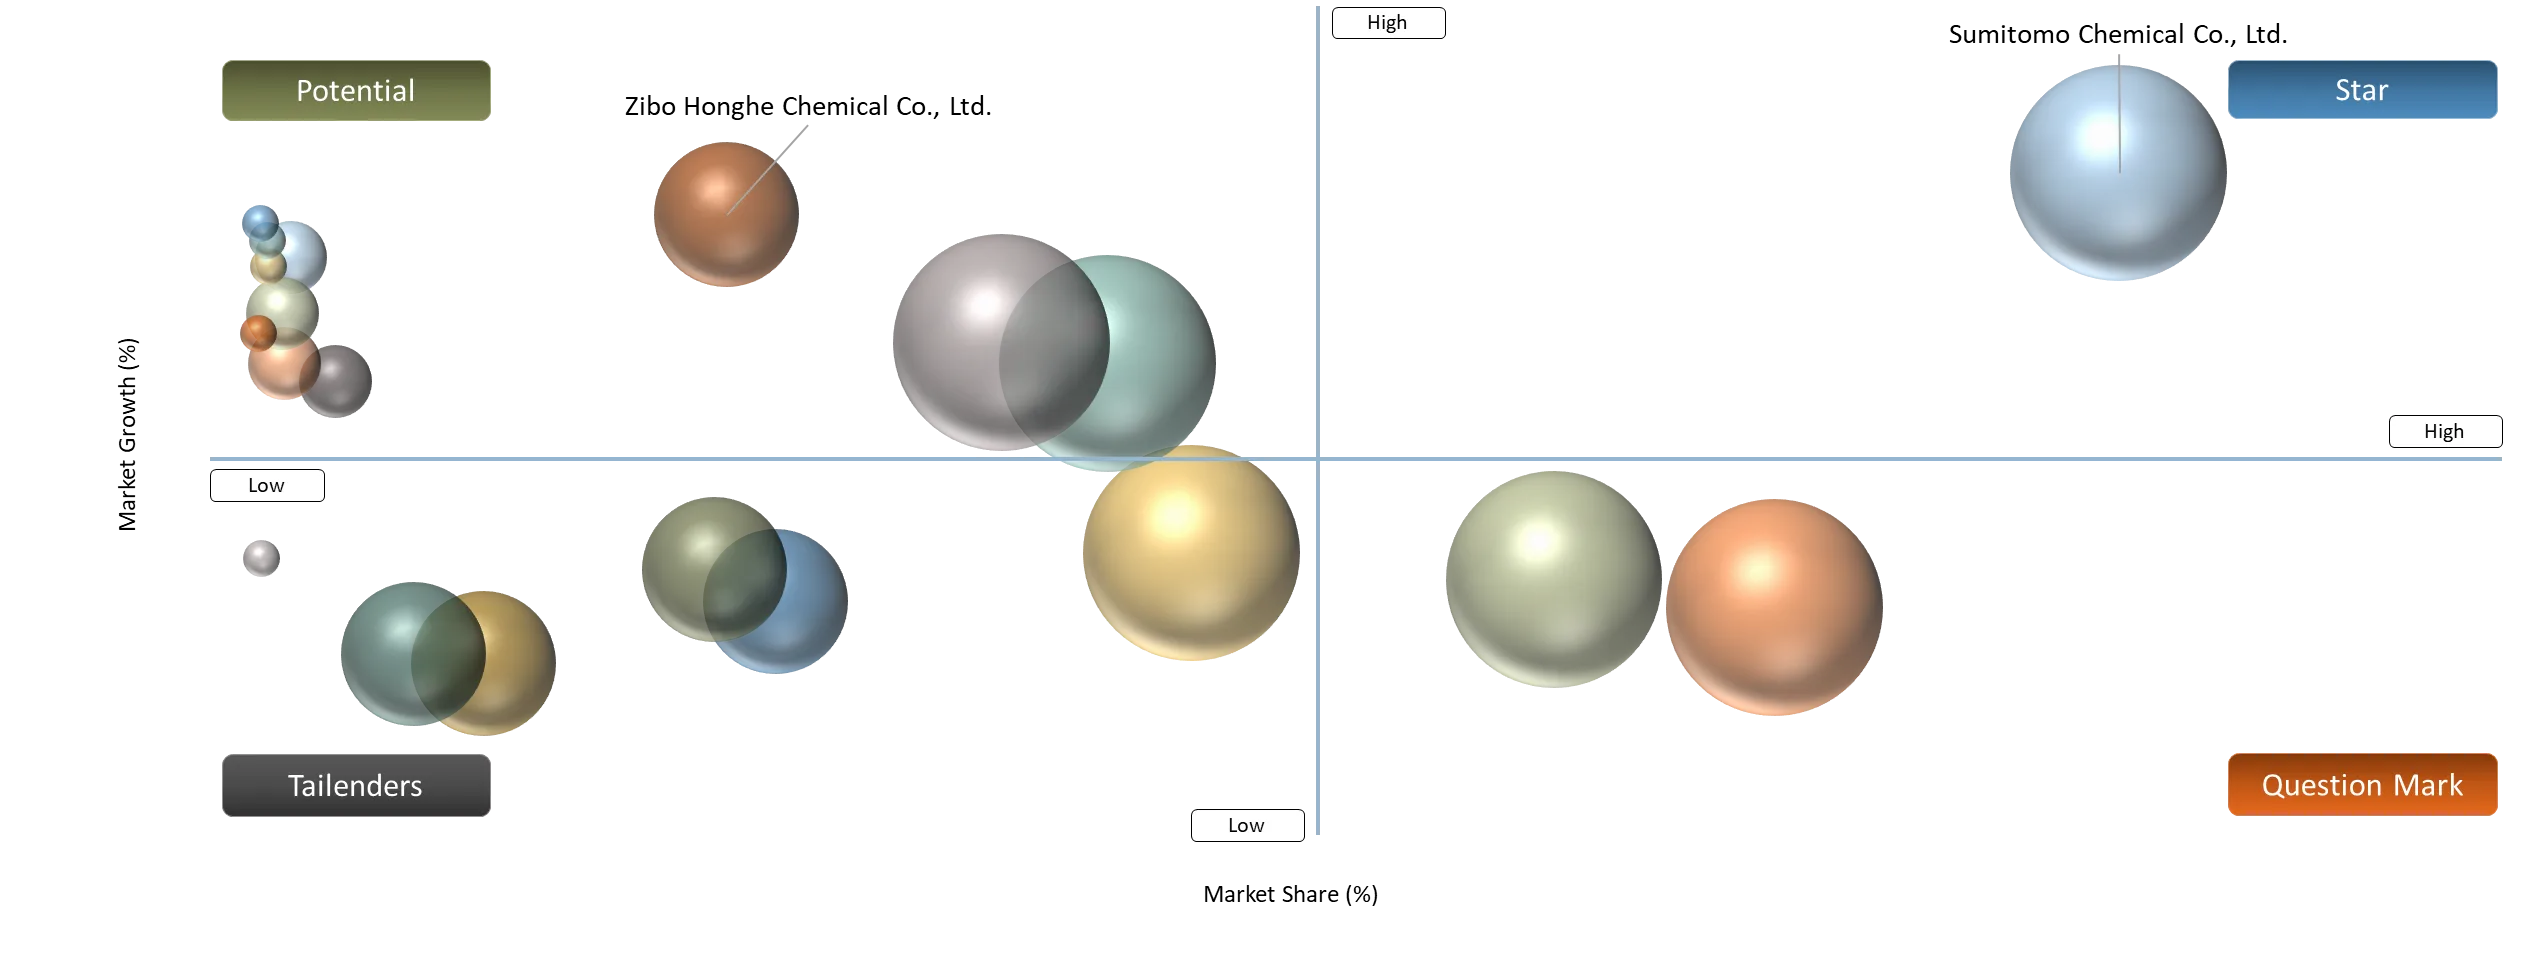
Stars include Sumitomo Chemical Co., Ltd., Sasol Limited, and Nippon Light Metal Co., Ltd. because these companies have established HPA production capabilities and strong positions across high-value applications such as semiconductor materials, battery-related components, LEDs, and advanced ceramics. Question Marks include Baikowski S.A., Taimei Chemicals Co., Ltd., Chalco Shandong Advanced Material Co., Ltd., Xuancheng Jingrui New Material Co., Ltd., and Shandong Higiant High-Purity Alumina Technology Co., Ltd.
Potential includes Zibo Honghe Chemical Co., Ltd., Shandong Gemsung Technology Co., Ltd., Hebei Heng Bo New Material Technology Co., Ltd., and Dalian Hiland Photoelectric Material Co., Ltd. Tailenders include Polar Performance Materials Inc. and Shandong Keheng Crystal Material Technologies Co., Ltd., whose HPA-related activities are comparatively narrower than those of the leading producers and diversified advanced-material companies.
High Purity Alumina Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Growing semiconductor, AI, and advanced-electronics production is supporting demand for ultra-high-purity materials such as HPA. | 28% | High – Asia Pacific, North America, and East Asia | Semiconductor substrates, advanced packaging, electronic ceramics, thermal-management components | Accelerates demand for 5N–6N HPA and application-specific grades, encouraging suppliers to improve impurity control and develop semiconductor-qualified materials. |
Rising global lithium-ion battery production is driving HPA demand for ceramic coatings that improve separator safety and thermal stability. | 25% | Very High – China, Japan, South Korea, Europe, and North America | Battery separator coatings, EV batteries, energy-storage systems | Strengthens HPA's position as a functional battery material and encourages capacity expansion toward battery-grade and higher-purity products. |
Rapid expansion of EV and energy-storage battery manufacturing is increasing demand for high-performance HPA used in advanced battery components. | 22% | High – Asia Pacific, Europe, and North America | EV battery cells, stationary energy storage, high-performance battery separators | Creates long-term downstream demand and encourages HPA producers to secure supply agreements with battery manufacturers and diversify into energy-storage applications. |
Increasing investment in localised battery and critical-mineral supply chains is encouraging regional HPA production and capacity expansion. | 15% | High – North America, Europe, Australia, Japan, and India | Domestic HPA production, battery-material supply chains, semiconductor materials | Reduces dependence on concentrated Asian supply chains and creates opportunities for new regional HPA plants using alternative feedstocks and lower-carbon processing routes. |
Growing semiconductor, AI, and advanced-electronics production is supporting demand for ultra-high-purity materials such as HPA
The rapid expansion of semiconductor manufacturing, AI infrastructure development, and advanced electronic systems calls for high-purity products. In situations where semiconductor manufacturers need strict impurity levels, thermal stability, electrical insulation, and material consistency, the demand for HPA increases. Additionally, the increase in artificial intelligence, high-performance computers, and semiconductor architecture is driving material performance demands in the electronics supply chain.
In parallel, the International Energy Agency (IEA) reported that prices for strategic minor minerals increased by over two times during 2025 and the beginning of 2026, with tungsten prices rising by six times due to high demand and tight supply conditions. According to the IEA report, the average percentage of top refineries' countries for critical minerals has increased to 72% in 2025 compared to 70% in 2023. In addition, the public finance commitment for critical mineral projects in advanced economies was about USD 65 billion in 2025, which is nearly four times higher than in 2023. Particularly, the agency highlighted semiconductors, robotics, and artificial intelligence (AI) as drivers of the next innovation wave and pointed out that gallium, germanium, indium, and antimony are of great importance for high technologies.
High Purity Alumina Market Segment Analysis
The global high purity alumina market is segmented based on purity level, form, end user, and region.
Powder-Form HPA Dominates Through Broad Application Coverage and Highly Controlled Particle Characteristics
The powder segment dominates the high purity alumina market, with a market share of 68.0% in 2025, owing to the ability to engineer the powdered form of HPA with controlled particle size, morphology, crystallinity, and surface properties for various high-end applications. The use of HPA in areas such as semiconductor processing, lithium-ion batteries, thermal management materials, technical ceramics, and sapphire applications ensures that the powder has a broader application range compared to other forms such as pellets and pucks.
Baikowski's PB high-purity alumina powder series demonstrates how engineered powder characteristics are supporting increasingly specialised applications. The company offers PB powders with a specific surface area of 8-12 m²/g and d50 (median particle size) of 0.30-0.36 μm. The density of sintered powders at 1,510 °C is about 3.92 - 3.95 g/cm³. Baikowski provides unground, jet-milled, ball-milled, and specially deagglomerated powders, making it possible to adjust the particle characteristics to suit the needs of technical ceramics.
High Purity Alumina Market Geographical Penetration
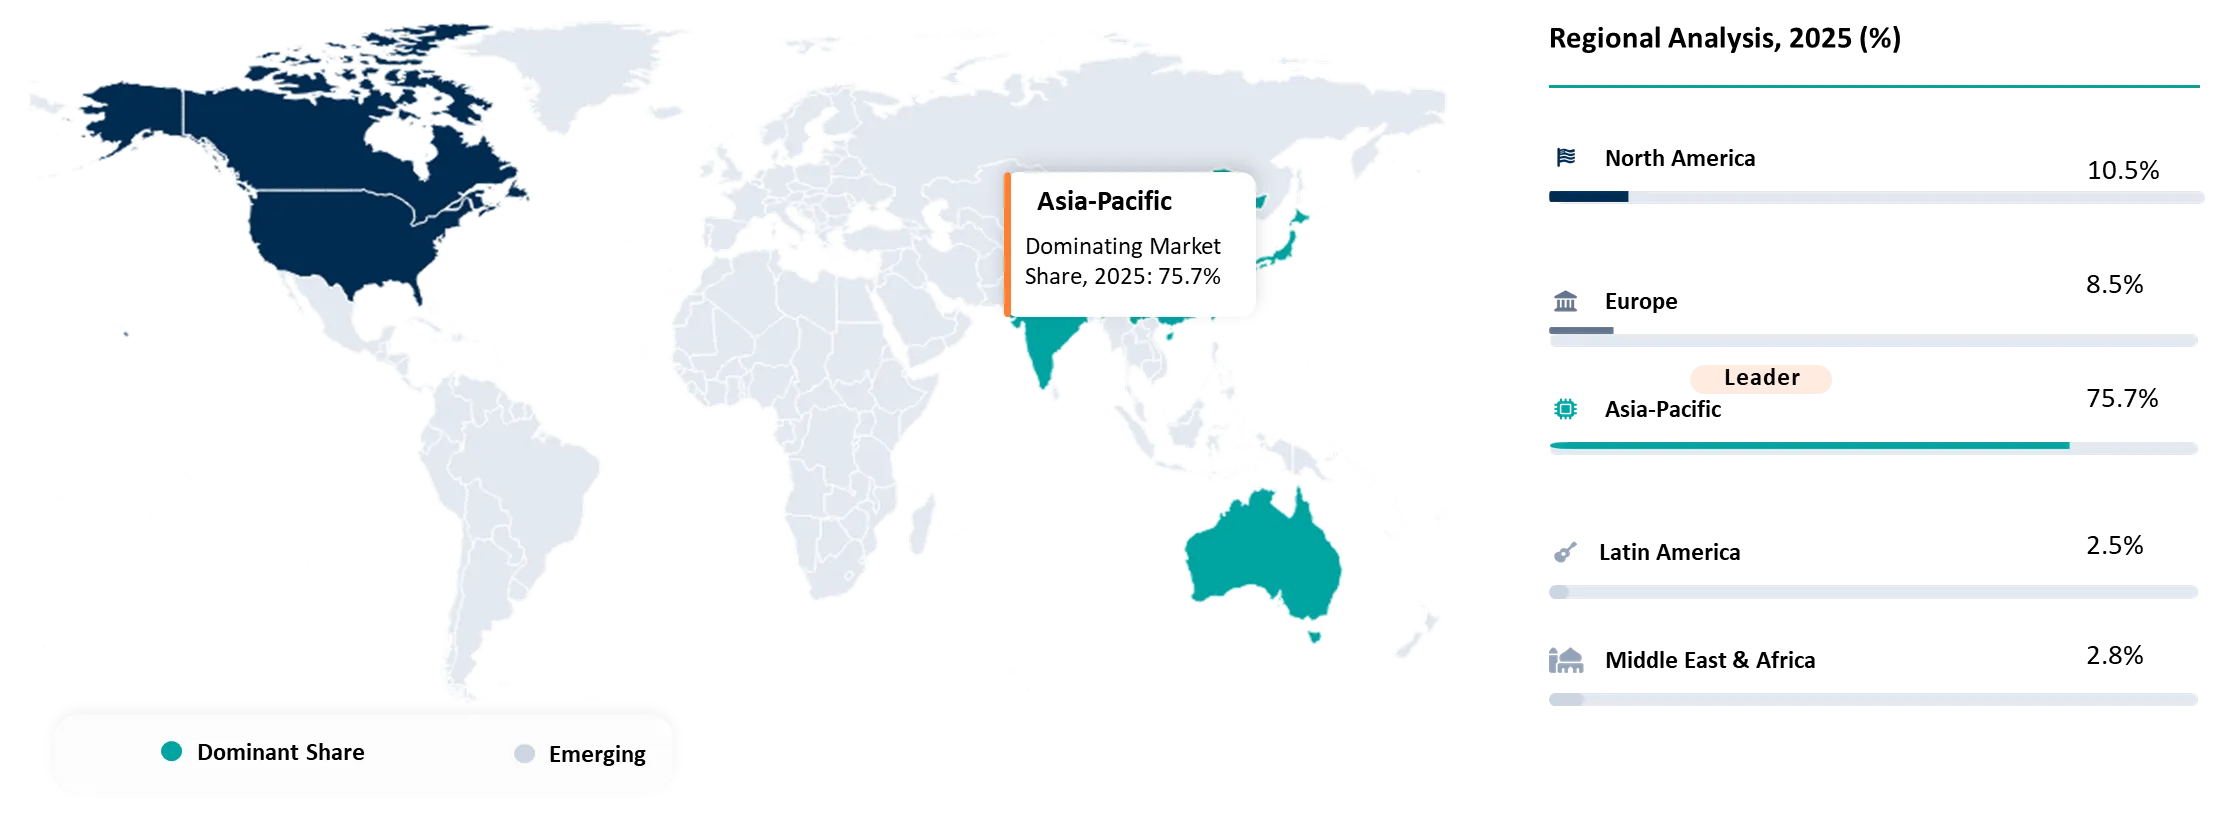
Asia-Pacific Dominates the High Purity Alumina Market Through Semiconductor, Battery, and Advanced-Material Manufacturing Expansion
The Asia-Pacific region dominates the high-purity alumina (HPA) market, accounting for a 75.7% market share in 2025, supported by its concentration of semiconductor, LED, lithium-ion battery, electronics, and synthetic-sapphire manufacturing. The region's integrated downstream manufacturing ecosystem is creating strong demand for high-purity and application-specific alumina grades, particularly for semiconductor processing, thermal-management materials, battery components, and advanced ceramics.
The expansion strengthens Asia-Pacific supply capabilities for high-purity alumina used in advanced semiconductor manufacturing and AI-related applications. In May 2026, Sumitomo Chemical Co., Ltd., a Japan-based chemical manufacturer, announced the launch of its ELA series of low-alpha-radiation, high-purity fine spherical alumina, expanding its high-purity alumina portfolio for advanced semiconductor applications. The ELA products have 99.99% or higher purity, offer low radiation and enhanced heat-dissipation properties, and feature particle sizes controllable to several micrometres or less, targeting advanced semiconductor packaging and AI semiconductor applications.
The product was developed by Dongwoo Fine-Chem Co., Ltd., a South Korea-based semiconductor materials and chemicals company and wholly owned subsidiary of Sumitomo Chemical.
China High Purity Alumina Market Trends
China holds the dominant position in the Asia-Pacific high-purity alumina (HPA) market, supported by its extensive alumina-processing ecosystem, large electronics and semiconductor manufacturing base, and growing production of advanced ceramic and functional materials. The country's integrated raw-material, refining, chemical-processing, and downstream manufacturing capabilities provide HPA producers with access to established supply chains and major end-use industries.
The project strengthens China’s domestic high-purity alumina and advanced sapphire materials supply chain for semiconductor, LED, optical, and electronics applications. In May 2025, Huatian Holdings Group Co., Ltd., a China-based industrial investment and manufacturing company, the Yuxi Municipal Government, a Chinese local government authority, and the Shandong University Yunnan Research Institute, a China-based university research institute, advanced an integrated high-purity alumina and sapphire functional-materials industry-chain project in Yuxi, Yunnan Province, China.
The project is planned in three phases with total investment of approximately RMB 4.2 billion (USD 630 million), and is expected to generate more than RMB 10 billion (USD 1.49 billion) in annual output value after reaching full production.
Japan High Purity Alumina Market Outlook
Japan is one of the major countries in the Asia-Pacific high purity alumina (HPA) market, supported by its established speciality-chemical industry, advanced ceramics expertise, and close integration with semiconductor, electronics, battery, and precision-material manufacturers. Japanese producers are increasingly positioning HPA as a strategic material for higher-value applications rather than only conventional alumina uses.
The investment strengthens Japan’s position in advanced speciality alumina production and expands regional supply capabilities for high-performance aluminium oxide materials. In October 2025, Evonik Industries AG, a Germany-based speciality chemicals manufacturer, inaugurated its Alu5 advanced fumed alumina production facility in Yokkaichi, Japan, representing a mid-double-digit million-euro investment to expand its Asian footprint. The facility manufactures AEROXIDE fumed aluminium oxide, a high-performance speciality alumina material used in ultra-thin coating technologies, lithium-ion batteries, electric mobility, consumer electronics, and sustainable powder coatings.
North America Strengthens the High Purity Alumina Market Through Semiconductor Localisation and Advanced-Material Investment
North America accounted for a 10.5% market share of the global high-purity alumina (HPA) market in 2025, supported by the region's expanding semiconductor ecosystem, battery-material manufacturing, advanced ceramics, and efforts to localise critical-material supply chains. The combination of semiconductor fabrication, AI infrastructure, electric-vehicle battery production, and speciality-material research is increasing the requirement for high-purity inputs with tightly controlled chemical and physical characteristics.
The collaboration strengthens the commercialisation pathway for battery-grade HPA and expands its potential integration into advanced lithium-ion and solid-state battery technologies. In December 2025, Impact Minerals Limited, an Australia-based mining and minerals development company, advanced its High Purity Alumina (HPA) commercialisation strategy through its 50%-owned associate Alluminous Pty Ltd, an Australia-based HPA technology company, which entered into a technology collaboration with Charge CCCV LLC (C4V), a U.S.-based battery technology company.
The collaboration focuses on developing and qualifying HiPurA HPA for advanced lithium-ion battery applications, including separator coatings, ceramic layers, solid-state components, and electrode-interface materials.
U.S. High Purity Alumina Market Trends
The U.S. holds a dominant position in the high-purity alumina (HPA) market, supported by the expansion of domestic semiconductor manufacturing, AI infrastructure, advanced packaging, and high-performance materials. The country's growing emphasis on domestic semiconductor and critical-material supply chains is encouraging demand for ultra-high-purity materials with tightly controlled impurity profiles.
The acquisition strengthens Hindalco’s presence in the North American speciality alumina supply chain and expands its portfolio of advanced alumina materials. In June 2025, Hindalco Industries Limited, an India-based metals and aluminium manufacturer and Aditya Birla Group company, announced the acquisition of a 100% stake in AluChem Companies, Inc., a U.S.-based speciality alumina producer, for an enterprise value of USD 125 million. AluChem operates three manufacturing facilities across Ohio and Arkansas, with annual production capacity of approximately 60,000 tonnes.
High Purity Alumina Market Competitive Landscape
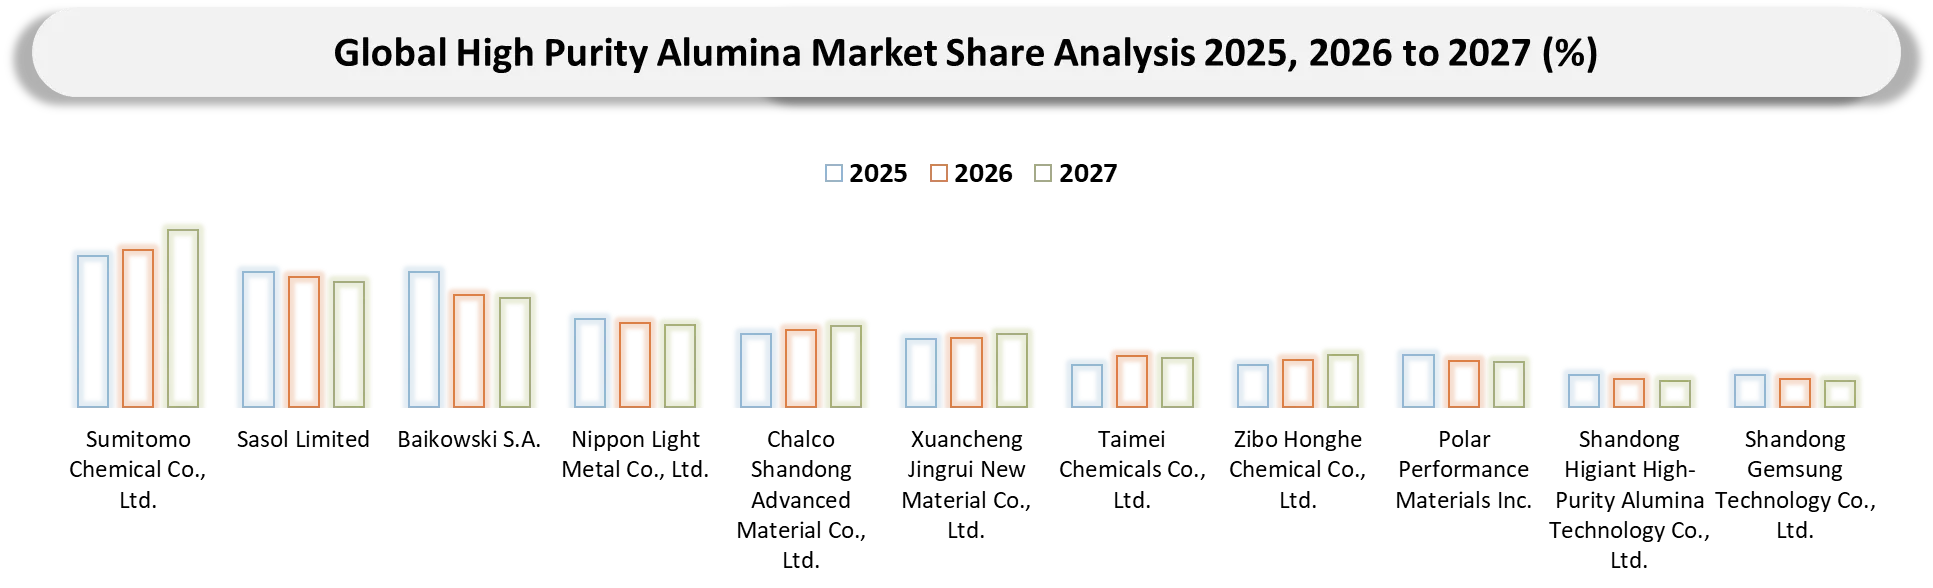
- The competitive landscape is characterised by three major participant groups: diversified speciality-chemical and alumina producers, specialised high-purity alumina manufacturers, and technology-led emerging producers. Sumitomo Chemical, Sasol, Baikowski, and Nippon Light Metal compete through established high-purity material portfolios and application-specific products, while Chalco Shandong Advanced Material, Xuancheng Jingrui, Taimei Chemicals, Zibo Honghe, Shandong Higiant, Shandong Gemsung, Hebei Heng Bo, Dalian Hiland, and Shandong Keheng strengthen the Chinese supply base across high-purity alumina, sapphire, ceramics, and electronic-material applications. Polar Performance Materials differentiates through 5N alumina for semiconductor, sapphire, aerospace, and technical-ceramics applications, while Alpha HPA is pursuing a technology-led model based on proprietary solvent-extraction and high-purity refining technology.
- Key players include Sumitomo Chemical Co., Ltd. (Japan), Sasol Limited (South Africa), Baikowski S.A. (France), Nippon Light Metal Co., Ltd. (Japan), Chalco Shandong Advanced Material Co., Ltd. (China), Xuancheng Jingrui New Material Co., Ltd. (China), Taimei Chemicals Co., Ltd. (Japan), Zibo Honghe Chemical Co., Ltd. (China), Polar Performance Materials Inc. (Canada), Shandong Higiant High-Purity Alumina Technology Co., Ltd. (China), Shandong Gemsung Technology Co., Ltd. (China), Hebei Heng Bo New Material Technology Co., Ltd. (China), Dalian Hiland Photoelectric Material Co., Ltd. (China), Shandong Keheng Crystal Material Technologies Co., Ltd. (China), and Alpha HPA Limited (Australia).
Key Developments
- April 2025: Impact Minerals Limited, an Australia-based mining and minerals development company, announced plans to acquire a 50% interest in Alluminous Pty Ltd, an Australia-based high-purity alumina technology company, for a total acquisition cost of A$2.2 million (USD 1.54 million).
- December 2025: Chongqing Renbing Technology Co., Ltd., a China-based high-purity alumina and advanced alumina materials manufacturer, highlighted its expansion in the High Purity Alumina (HPA) market and domestic substitution of imported materials.
- January 2026: Ceracom Co., Ltd., a South Korea-based environmental ceramic materials manufacturer, achieved what it described as the world’s first commercial mass production of 99.9% high-purity alumina honeycomb supports.
- June 2025: Hindalco Industries Limited, an India-based metals and aluminium manufacturer and Aditya Birla Group company, announced the acquisition of a 100% stake in AluChem Companies, Inc., a U.S.-based speciality alumina manufacturer, for an enterprise value of USD 125 million.
- August 2026: Alpha HPA Limited, an Australia-based high-purity alumina producer, signed a Letter of Intent (LOI) with a South Korean speciality ceramics supplier serving the semiconductor industry for up to 1,400 tonnes of high-purity aluminas and alumina hydrates, increasing Alpha HPA’s total LOI coverage to 13,500 tonnes for its HPA First Project Stage 2 capacity.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organisations procuring high purity alumina (HPA) increasingly prioritise suppliers capable of delivering consistent purity levels, controlled particle-size distribution, and stable material characteristics suited to semiconductor, battery, LED, sapphire, and advanced-ceramic applications.
- The procurement decision is increasingly influenced by the growing requirements for ultra-high-purity grades, low impurity concentrations, controlled morphology, low alpha radiation, and application-specific surface properties, particularly for semiconductor and advanced-electronics applications.
- Buyers evaluate suppliers based on purity consistency, particle-size distribution, crystalline phase, specific surface area, morphology, moisture content, trace-metal levels, thermal performance, and batch-to-batch quality, as these parameters directly affect downstream processing and product reliability.
Why Choose DataM?
- Technological Innovations: Explores advancements in HPA purification, alternative-feedstock processing, ultra-high-purity grades, controlled particle engineering, low-alpha alumina, and specialised powder technologies for semiconductor, battery, sapphire, LED, and advanced-ceramic applications.
- Product Performance & Market Positioning: Evaluates how HPA producers differentiate through purity level, particle-size distribution, morphology, crystalline phase, surface area, thermal performance, and impurity control, highlighting competitive positioning across 4N, 4N5, 5N, and above-5N grades.
- Real-World Evidence: Highlights HPA adoption across semiconductor processing, lithium-ion battery separator coatings, synthetic sapphire, LED substrates, CMP, thermal-management materials, and technical ceramics, demonstrating how material characteristics influence downstream performance and reliability.
- Market Updates & Industry Changes: Tracks new HPA production facilities, capacity expansions, purification technologies, product launches, pilot-scale developments, and regional supply-chain investments across Asia-Pacific, North America, Europe, and Australia.
- Competitive Strategies: Analyzes how leading companies pursue growth through proprietary purification technologies, feedstock diversification, production-scale expansion, application-specific HPA grades, strategic partnerships, and downstream customer qualification.
- Pricing & Market Access: Examines HPA pricing differences according to purity level, particle characteristics, production technology, application requirements, processing complexity, and order volumes, together with access to semiconductor, battery, LED, sapphire, and advanced-ceramic supply chains.
- Market Entry & Expansion: Identifies opportunities created by semiconductor localisation, AI and advanced-electronics manufacturing, EV and battery expansion, synthetic sapphire demand, and advanced ceramics, while assessing strategies such as regional production, technology differentiation, alternative feedstocks, and long-term customer agreements.
Target Audience 2026
- HPA Manufacturers & Specialty Chemical Producers
- Semiconductor Manufacturers & Advanced Packaging Companies
- Lithium-Ion Battery & Energy-Storage Manufacturers
- LED & Synthetic Sapphire Manufacturers
- Technical Ceramics & Advanced Materials Manufacturers
- CMP & Semiconductor Process-Material Suppliers
- HPA Raw-Material & Technology Developers





























































