Germany Data Center Motors and Drives Market Size and Overview
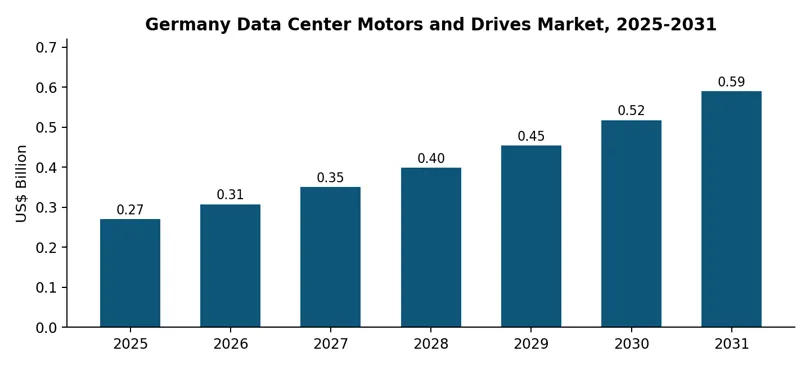
The Germany Data Center Motors and Drives Market is estimated at US$ 0.27 billion in 2025 and is projected to reach US$ 0.59 billion in 2031, equivalent to approximately 13.9% annualized growth. Data center expansion in Frankfurt, Berlin and emerging regional clusters is increasing the requirement for motor-driven chilled-water circulation, air handling, heat rejection and liquid-cooling distribution.
The market covers electric motors and variable frequency drives installed in data center mechanical services. Demand includes motors used with pumps, fans, chillers and cooling towers plus VFDs managing speed, energy consumption and system response. The equipment estimate excludes complete cooling units, chillers, pump packages and building-management software to avoid double counting.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026-2031) |
| US$ 0.27 Billion | US$ 0.59 Billion | 13.9% |
Germany Data Center Motors and Drives Key Takeaways
Data center motor and drive revenue is estimated to expand from US$ 0.27 billion in 2025 to US$ 0.59 billion in 2031.
Frankfurt remains Germany's largest colocation hub, while announced Berlin and regional builds widen equipment procurement opportunities.
AI rack densities are raising demand for coolant circulation, heat rejection and high-reliability pump and fan motors.
Variable frequency drives help mechanical plant adjust water flow and airflow as cooling loads vary.
Germany's efficiency and waste-heat requirements strengthen the business case for efficient motors, drives and controls.
Approved-vendor status with cooling OEMs, service response and spare-drive availability influence sourcing decisions.
Germany Data Center Motors and Drives Industry Trends and Strategic Insights
Operators are combining chilled-water systems, air cooling and direct-liquid cooling, changing the mix of pump and fan applications.
Mechanical engineering packages increasingly bring matched motors, VFDs, pumps and plant controllers into one purchase specification.
Energy-efficiency and heat-reuse objectives encourage closer control of part-load pump and fan performance.
Suppliers able to provide harmonics management, building controls integration and rapid field replacement have an advantage.
Germany Data Center Motors and Drives Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 0.27 Billion |
| 2031 Projected Market Size | US$ 0.59 Billion |
| CAGR (2026-2031) | 13.9% |
| By Drive Type | AC induction and permanent-magnet fan and pump motors, low- and medium-voltage VFDs |
| By End-Use Industry | Hyperscale, colocation, enterprise and edge data centers |
| By Power Rating | Chilled water, condenser water, HVAC fans, cooling towers, liquid cooling |
| By Voltage | Below 7.5 kW, 7.5-37 kW, above 37-200 kW, above 200 kW |
| By Control Method | IE3, IE4, PM motor designs, vector and variable-speed drive control |
| By Application | Indoor mechanical rooms, rooftop equipment, packaged cooling systems |
| By Installation Stage | New construction, campus expansion, retrofit and replacement |
| Market Data Coverage | 2025-2031 equipment-revenue estimates, cooling-system applications and market trends |
Germany Data Center Motors and Drives Market White Space & Investment Opportunities
Cooling upgrades: target older data halls with VFD retrofits and high-efficiency pump and air-handling motors.
AI infrastructure: qualify motors and drives for redundant liquid-cooling circulation and high-density heat rejection.
Lifecycle services: provide predictive maintenance, replacement stock, commissioning and controls integration.
Vendors should engage cooling equipment OEMs, MEP contractors and data center developers before mechanical designs are frozen. Reference installations, energy performance and access to local field support are central to repeat-project awards.
Driver Impact Analysis
Germany's expanding data center pipeline supports the installation of chilled-water pumps, condenser-water motors, ventilation fans and variable-speed drives. Larger campuses create multiple cooling plant stages and higher demand for redundancy. Liquid-cooling distribution brings additional circulation duty but alters the balance between air movement and water flow. Supplier engagement during early MEP specification can secure approval for repeated equipment packages.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 IMPACT | STRATEGIC IMPACT |
| Cooling and mechanical plant motors | High | New data center construction and phased cooling plant installations | Secure positions with German mechanical OEMs at design stage |
| Liquid-cooling circulation systems | High | High-density coolant circulation and redundant pump motors | Prove serviceability and redundancy in modular systems |
| Energy-efficiency compliance and retrofits | High | VFDs for chilled-water, HVAC and condenser systems | Quantify part-load savings and support controls integration |
| Mechanical plant reliability and uptime | Medium-High | Local service, diagnostics and drive replacement | Offer spares, monitoring and rapid commissioning support |
Efficiency and reliability are equally important demand drivers. Running centrifugal pumps and fans at variable speed can lower part-load power use, while condition monitoring provides earlier warning of mechanical or electrical faults. Germany's data center energy-efficiency requirements also encourage operators to examine cooling performance when replacing mechanical plant. High-serviceability designs can win premium applications when maintenance access is limited.
Restraint Impact Analysis
Motor and drive purchasing is commonly embedded in larger cooling-system procurement contracts. This reduces visibility of individual component spending and limits direct access for suppliers outside an OEM's approved list. Critical facilities also expect extensive reliability validation, detailed acceptance testing and a proven local service organization before changing their standard motor or drive platform.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| OEM-bundled mechanical procurement | Pump, chiller and air-handling OEM packages | High | Build approved supplier relationships with major OEMs |
| Grid connection and project scheduling | Phased construction schedules and project releases | High | Link production commitments to confirmed project milestones |
| Live-site modernization and controls compatibility | Existing BMS interfaces and critical cooling systems | Medium-High | Plan acceptance testing and short maintenance windows |
| Changing liquid- versus air-cooling architecture | Pump and fan motor mixes across cooling designs | Medium-High | Offer modular equipment for different thermal architectures |
Additional constraints include grid-connection delays that can shift construction schedules, higher costs for low-volume specialized mechanical designs and the difficulty of performing electrical retrofits inside running data centers. VFD harmonics, electromagnetic interference and interfaces with existing building-management controls may also require extra engineering. Cooling architecture changes can reduce air-handling motor demand even as liquid-loop pump demand grows.
Germany Data Center Motors and Drives Market Competitive Landscape
Competition includes German and international motor manufacturers, VFD specialists, pump suppliers and suppliers of packaged cooling systems. Data center buyers prioritize demonstrated uptime, motor and drive efficiency, low-harmonic performance, BMS integration and German field-service availability. A strong channel relationship with HVAC and pump OEMs can be as valuable as a direct sales presence.
| COMPANY | DATA CENTER MOTORS AND DRIVES POSITIONING |
| Siemens | SIMOTICS motors and SINAMICS drive systems for HVAC pumps, fans and mechanical services. |
| ABB | High-efficiency motors and AC drives for pumping, ventilation and cooling-plant utilities. |
| Danfoss Drives | VLT and VACON drives for variable-flow HVAC and water-circulation systems. |
| SEW-EURODRIVE | Motors, drive technology and engineered motion equipment with German service coverage. |
| WEG | Industrial electric motors and variable-speed drives for mechanical plant equipment. |
| KSB | Pump systems and variable-speed control expertise relevant to chilled-water circulation. |
| Bosch Building Technologies | Building controls and HVAC integration relevant to critical cooling management. |
| ebm-papst | Efficient fan motors and EC-driven air movement for HVAC and data center cooling. |
| Schneider Electric | Motor control and variable-speed drive products with data center infrastructure channels. |
| Ziehl-Abegg | Energy-efficient fan and motor technologies for cooling and ventilation equipment. |
Equipment is generally specified by mechanical system manufacturers, engineering consultants and MEP contractors before facility procurement. Multi-site standardization offers suppliers repeat business if the same drive family, spare parts and diagnostics can be supported across several German campuses.
Germany Data Center Motors and Drives Market Recent Developments
January 13, 2026: maincubes announced €2.475 billion in financing to advance its German data center portfolio, including a fourth Frankfurt facility and a planned Berlin campus.
April 3, 2026: Frankfurt (Oder) advanced plans for a data center site with six proposed modules and up to 350 MW of connected load.
April 22, 2026: SCHÄFER IT-Systems and Spirotech introduced ProtectaCool Rack, a liquid-cooling circuit protection system for higher-density data centers.
July 7, 2026: HOCHTIEF reported a construction contract for an NTT 36 MW Berlin data center, including major mechanical and electrical works.
September 17, 2026: NorthC began preparatory construction work for a 6 MW Frankfurt data center planned to enter service in 2028.
October 20, 2026: Amazon outlined €4.8 billion planned for expansion of its AWS Frankfurt cloud and AI infrastructure in 2027.