


Germany Data Center Cables & Wires Market Size and Overview
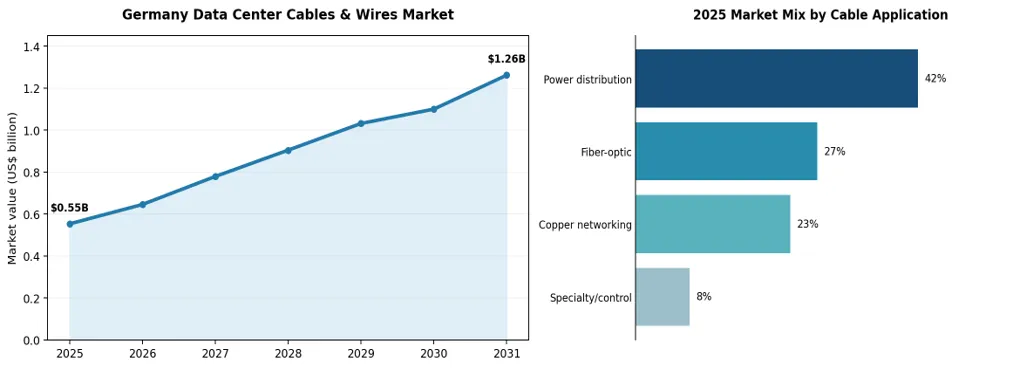
The Germany Data Center Cables & Wires Market was valued at US$ 0.55 billion in 2025 and is forecast to reach US$ 1.26 billion by 2031, at a CAGR of 14.75% during 2026–2031. The market encompasses medium- and low-voltage power distribution cables, optical fiber links, structured copper networks and fire-rated control cabling installed in hyperscale, colocation, enterprise and edge data centers.
German demand is driven by data-center power capacity additions in Frankfurt/Rhine-Main and developing sites in Berlin, Munich and other digital infrastructure corridors. AI server clusters require dense fiber links and robust power distribution between incoming substations, UPS installations, busway interfaces, PDUs and equipment racks. Upgrades to existing facilities are also creating opportunities for low-smoke, halogen-free cable replacements and high-density connectivity.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 9.41 Billion | US$ 11.04 Billion | 2.71% |
Germany Data Center Cables & Wires Key Takeaways
The Germany Data Center Cables & Wires Market is projected to rise from US$ 0.55 billion in 2025 to US$ 1.26 billion in 2031.
The forecast CAGR of 14.75% is supported by hyperscale capacity investment, expansion of AI infrastructure and cabling upgrades inside operating facilities.
Power-distribution cables account for a substantial share of cabling expenditure due to the need for redundancy, resilient low-voltage distribution and grid interconnection.
Optical fiber is an attractive growth category as higher-bandwidth connections and denser inter-rack networking become standard in AI-focused data centers.
Fire-rated, low-smoke and halogen-free specifications remain important procurement requirements in enclosed German data-center facilities.
Cable suppliers can strengthen positions through qualified installation partners, preterminated assemblies and rapid deployment support.
Germany Data Center Cables & Wires Industry Trends and Strategic Insights
High-density networking shifts demand toward fiber-rich trunk solutions, MPO/MTP assemblies and structured connectivity that reduces installation time.
Operators are standardizing redundant power-distribution pathways and documented testing to reduce deployment and operating risks.
High-density racks increase requirements for cable management, airflow-conscious routing and flexible, fire-safe designs.
Sustainability specifications increasingly influence materials selection, product declarations and retrofit projects.
Germany Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 0.55 Billion |
| 2031 Projected Market Size | US$ 1.26 Billion |
| CAGR (2026–2031) | 14.75% |
| Geographic Coverage | Germany: Frankfurt/Rhine-Main, Berlin, Munich and other data-center development clusters |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
The study analyzes data-center-specific power and data cabling by cable type, facility category, end-use application, conductor or transmission medium, voltage rating, installation method plus insulation and sheathing materials. Market Scope uses one row for each segmentation.
Germany Data Center Cables & Wires Market White Space & Investment Opportunities
AI-ready networking: High-fiber-count and preterminated cable systems enable fast deployment of high-bandwidth racks and interconnections.
Critical-power upgrades: Low-voltage power feeders, UPS and backup-generator connections create recurring replacement and expansion opportunities.
Retrofit programs: Modernizing older facilities can generate demand for compact cable routes, fire-safe materials and documented installation services.
Frankfurt/Rhine-Main remains a key market for large-scale data-center infrastructure, with Berlin, Munich and other industrial and digital clusters creating additional opportunity. Project execution increasingly depends on grid availability, cable qualification, contractor access and efficient construction sequencing. Suppliers offering integrated power and network cable packages can improve engagement with facility developers, MEP contractors and network integrators.
Driver Impact Analysis
Growth in AI computing capacity and cloud demand is increasing the number and intensity of critical-power cable routes within German data centers. New campuses require medium-voltage incoming feeders, low-voltage distribution cables, backup-power connections and robust wiring to support redundant architectures. Demand also extends beyond new builds: operating facilities periodically replace network cabling and extend electrical distribution as rack densities and computing equipment change.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| AI / hyperscale capacity expansion | Power feeders and high-density optical fiber | High | Target campus developers and design contractors early |
| Data-center upgrades and rack densification | Fiber trunks, copper networks and LV cables | High | Bundle retrofit-friendly connectivity and power solutions |
| Redundant critical-power infrastructure | MV/LV cables, UPS interconnects and fire-rated wiring | High | Differentiate with validated reliability and installation support |
| Cloud and colocation network build-out | Structured copper and fiber backbones | Moderate–High | Work with network integrators and operators |
Fiber connectivity is expanding in importance as higher-bandwidth interconnects and AI clusters increase the density of connections between racks and network rooms. Cable procurement increasingly favors fire-safe materials, reliable bend performance, documented optical performance and preterminated cable assemblies that shorten installation windows. Suppliers with German technical support, system integrator relationships and established fulfillment capacity are well placed to serve both new construction and retrofit projects.
Restraint Impact Analysis
Grid-connection capacity, permitting procedures and skilled electrical-installation labor can delay data-center project execution, pushing cable procurement into later periods. Metal pricing, optical-fiber supply, specialized connector availability and freight costs create exposure for suppliers quoting major campus projects. Stringent operational uptime requirements can further lengthen component qualification and constrain last-minute product substitutions.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid connections and permitting | New campus timelines | High | Align cable deliveries to secured power and construction milestones |
| Copper and specialty-material inflation | Price exposure in power and control cables | High | Use indexed commercial terms and qualified alternatives |
| Uptime and fire-safety qualification | Power and networking specifications | High | Maintain test documentation and qualified product ranges |
| Installer and containment constraints | Fiber density and routing inside facilities | Moderate–High | Support prefabrication, labeling and staged installation |
Long lead times for engineered power cable systems, constrained cable-tray space and increasingly dense optical pathways raise design and installation complexity. Operators may require repeat testing, fire-performance documentation and standardized cable identification to minimize commissioning risks. Suppliers can address these challenges through phased deliveries, certified product families, alternative sourcing, contractor training and tighter alignment with facility engineering schedules.
Germany Data Center Cables & Wires Market Competitive Landscape
Germany’s data-center cabling supplier landscape includes international cable manufacturers, specialist fiber providers and Germany-based industrial connectivity companies. Prysmian, Nexans, LAPP, HELUKABEL, Corning, Belden, LEONI, NKT, TKD Kabel and Südkabel participate across power feeds, structured networking, fiber connectivity and engineered installations.
| COMPANY | GERMANY DATA CENTER CABLES & WIRES POSITIONING |
| Prysmian | Power and optical fiber cable solutions for data centers |
| Nexans | LV/MV power and critical distribution cables |
| LAPP | Power, control and industrial connectivity cables |
| HELUKABEL | LV power and control cables, installation solutions |
| Corning | Optical fiber, high-density datacom and interconnect systems |
| Belden | Structured copper and optical data-center connectivity |
| LEONI | Specialty power, data and control cable systems |
| NKT | MV/HV power cabling for electricity-grid interconnections |
| TKD Kabel | Control and power cable products for facilities |
| Südkabel | High-voltage cables and engineered power connections |
Competitive differentiation depends on power-cable reliability, fire and smoke standards, deployment speed, fiber density, installation expertise and cable-system documentation. Hyperscale procurement often favors suppliers able to serve multi-site specifications, while colocation operators place value on retrofit support, availability of standardized components and dependable regional service. Partnerships with MEP contractors and systems integrators strengthen access to project design and deployment cycles.
Germany Data Center Cables & Wires Market Recent Developments
October 2026 — Acquisition and German capacity expansion: Prysmian completed its acquisition of Xtera through a joint venture with Fincantieri, alongside doubling submarine telecom cable capacity at its Nordenham facility in Germany. The deal expands the group’s telecommunications cable systems capabilities.
September 2026 — Product innovation: Prysmian introduced lower-carbon aluminum cable technology for AI infrastructure, advancing lower-emission cable options for high-power digital facilities.
July 2026 — Data-center cable investment: Prysmian announced an acceleration of its data-center strategy in Digital Solutions, targeting stronger high-density connectivity and optical-cable capabilities.
June 2026 — German regulatory proposal: The federal cabinet approved draft amendments to the Energy Efficiency Act affecting data centers, including proposed changes to efficiency transition periods and renewable-energy requirements. The draft was a legislative proposal rather than enacted law at that announcement.
May 2026 — Portfolio expansion and brand integration: Prysmian consolidated Draka-branded cables under the Prysmian brand in Germany, simplifying the product portfolio while retaining technical specifications and certifications.
March 2026 — Optical-fiber product launch: Prysmian introduced Sirocco Ultra microduct cables using 160-micrometre optical fibers to increase connection density for data-center, fiber-access and 5G networks.


























































