


Germany Cables & Wires Market Size and Overview
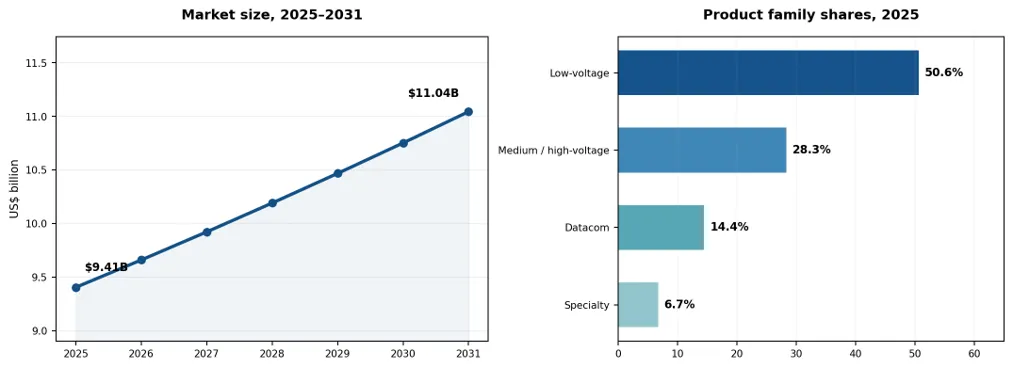
The Germany cables and wires market was valued at US$ 9.41 billion in 2025 and is expected to reach US$ 11.04 billion by 2031, representing 2.71% annualized growth over 2025–2031. Demand spans low-voltage building and industrial wiring, medium- and high-voltage power cables, copper and optical datacom cables plus application-specific specialty wires. Low-voltage products accounted for 50.58% of the 2025 market, followed by medium- and high-voltage cables at 28.27%.
German cable demand is supported by electricity-grid reinforcement, renewable-energy interconnection, building refurbishment, industrial automation and new digital infrastructure. Utilities require reliable underground and high-voltage transmission systems while industrial customers prioritize fire performance, electromagnetic compatibility, automation readiness and lifecycle quality. Cable manufacturers must also navigate raw-material costs, technical approval cycles and changing installation schedules.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 9.41 Billion | US$ 11.04 Billion | 2.71% |
Germany Cables & Wires Key Takeaways
Germany’s cables and wires market is forecast to increase from US$ 9.41 billion in 2025 to US$ 11.04 billion by 2031, representing US$ 1.64 billion of incremental demand.
The 2025–2031 annualized growth rate is 2.71%, reflecting established industrial consumption alongside medium-voltage utility and grid-renewal programs.
Low-voltage cables represented 50.58% of 2025 market value, led by building installation, facility refurbishment and general industrial wiring.
Medium- and high-voltage cables represented 28.27% of 2025 value, supported by grid reinforcement, renewable integration and large energy projects.
Datacom cables comprised 14.44% of 2025 market value, spanning fiber connectivity, enterprise networks, broadband and data centers.
Specialty cables accounted for 6.71% of 2025 revenue, including industrial, marine, wind and photovoltaic applications.
Germany Cables & Wires Industry Trends and Strategic Insights
Transmission-grid reinforcement and distribution-network upgrades are increasing demand for qualified high-voltage and medium-voltage cable systems, accessories and underground installation capabilities.
Onshore and offshore wind, solar projects and cross-border power corridors require cables built for demanding electrical, environmental and lifecycle performance.
Automotive manufacturing, machinery, industrial automation and semiconductor-related investment support flexible, shielded, control and application-specific cables.
Data-center construction, fiber broadband, enterprise modernization and rail infrastructure create demand for optical and copper networking cables with documented fire and reliability performance.
Germany Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 9.41 Billion |
| 2031 Projected Market Size | US$ 11.04 Billion |
| CAGR (2026–2031) | 2.71% |
| Geographic Coverage | Germany (national market and principal industrial, energy and utility demand clusters) |
| By Cable Type | Datacom Cables (Communication & Data Cables, Fiber Optic Cables); Low-Voltage Cables (Fire Resistant Cables, Low Smoke & Halogen Free Cables, Low Voltage Cables & Wires); Medium- and High-Voltage Cables (Medium Voltage Cables, High Voltage Cables); Special Cables (Mining Oil & Gas Cables, Photovoltaic Cables, Ship & Harbour Cables, Windmill Cables) |
| By Industry | Industrial — Discrete (Aerospace & Defense, Automotive, Batteries, Electrical & Electronics, Machine Building, Semiconductor); Process (Chemicals, Energy/Oil & Gas, Metal Processing); Hybrid (Food & Beverage, Lifesciences, Mining & Quarrying, Other Manufacturing). Non Industrial — Transportation (Air, Land, Rail, Marine Services); Infrastructure & Services (Commercial Real Estate, Data Centers, Healthcare, Hospitality & Entertainment, Public Sector/Research/Education, Residentials, Water & Waste, Others). Power Utilities — Power Generation (Coal, Conventional Excl. Coal, Renewables); Power Distribution & Transmission. |
| By Conductor / Transmission Medium | Copper; Aluminum; Optical Fiber; Composite / Hybrid Construction |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (above 1 to 35 kV); High Voltage (above 35 to 230 kV); Extra-High Voltage (above 230 kV) |
| By Insulation and Sheathing Material | Cross-Linked Polyethylene (XLPE); Polyvinyl Chloride (PVC); Ethylene Propylene Rubber (EPR/EPDM); Polyethylene (PE); Low Smoke Zero Halogen (LSZH); Other Materials |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, market developments and partnerships |
| Market Data Coverage | Cable-family and cable-subtype market values, 2025–2031 (US$ million); segmentation, competition and market dynamics |
The study covers Germany’s cables and wires market by cable family and subtype. The segmentation framework also covers industrial, non-industrial and power-utility end markets alongside conductor medium, voltage rating, insulation and sheathing materials plus installation method. Each segmentation is presented in a single Market Scope table row with detailed hierarchy retained in the Table of Contents.
Germany Cables & Wires Market White Space & Investment Opportunities
Grid reinforcement: Utility modernization and underground transmission corridors create openings for medium- and high-voltage cable manufacturers, installers and testing partners.
Industrial systems: Automotive, machinery, factory automation and process industries require fire-safe, shielded, flexible and chemical-resistant cable designs.
Digital infrastructure: Data centers and fiber upgrades support optical and structured copper cabling alongside reliable low-voltage power feeds.
Germany’s demand opportunities span North Rhine-Westphalia, Bavaria, Baden-Württemberg, Lower Saxony and major urban regions. Industrial clusters require plant wiring and flexible control cables, while northern wind-generation hubs and transmission corridors create opportunities for high-capacity power cable systems. Logistics, certification, subcontractor capacity and installation scheduling influence project conversion.
Driver Impact Analysis
Germany’s electricity-transition priorities are reinforcing demand for medium- and high-voltage cabling, particularly where renewable generation needs to be transmitted to consumption centers. Transmission and distribution upgrades require underground systems, high-performance insulation and robust connection accessories. Industrial electrification adds demand from manufacturing facilities, process industries, energy equipment and new production sites.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Grid reinforcement and power-system modernization | MV/HV underground and transmission cables | High | Utility qualification and contractor partnerships. |
| Renewable integration and offshore connections | HV cables, specialty and power interconnects | High | Target renewable developers, system operators and EPC firms. |
| Industrial automation and electrification | Industrial, control and low-voltage wiring | Moderate–High | Support industrial specifications and automated factories. |
| Fiber and data-center infrastructure | Optical fiber and structured copper | Moderate–High | Engage data-center integrators and network operators. |
Cable suppliers can benefit from early specification with transmission operators, distribution utilities, engineering contractors and industrial developers. Multiyear framework agreements support better capacity planning for highly engineered power cables. At the same time, renovation of commercial buildings, factory modernization and new data-center facilities support a continuing base of low-voltage and datacom demand.
Restraint Impact Analysis
Copper and aluminum price volatility can materially affect contract profitability and working capital, especially for long-lead infrastructure orders. Cable projects also face planning and permitting delays, product testing requirements and limited specialized installation crews. Supply-chain bottlenecks in insulation compounds, high-voltage accessories or qualified production capacity may lengthen delivery times.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Copper and aluminum price fluctuations | Contract margins and inventory funding | High | Metal-index procurement and contract protection. |
| Planning and grid-project delays | Project order conversion and scheduling | High | Strengthen pipeline management and stagger capacity. |
| Testing and engineering qualification | Utilities and mission-critical products | Moderate–High | Earlier type testing and design support. |
| Cost competition in standard cable products | Basic low-voltage and building wire | Moderate | Differentiate through quality, service and specialty products. |
Long utility tender cycles and cost pressure in standardized building wire can produce uneven order timing even when end-market requirements remain healthy. Manufacturers can address these constraints with metal-index pricing clauses, portfolio differentiation, certified products, localized technical support, diversified suppliers and closer alignment with contractor installation plans. Engineering-led suppliers are better positioned in specialty, transmission and critical-infrastructure applications.
Germany Cables & Wires Market Competitive Landscape
Germany’s cables and wires market includes international power-cable groups, locally headquartered industrial cable specialists and connectivity suppliers. Prysmian, Nexans, LEONI, LAPP, HELUKABEL, NKT, Südkabel, TKD Kabel, Corning and Belden participate across selected power, industrial, datacom and specialty applications. Differentiation depends on product breadth, testing credentials, distribution networks and engineering support.
| COMPANY | GERMANY CABLES & WIRES POSITIONING |
| Prysmian Group | Power, underground transmission and industrial cabling portfolio. |
| Nexans | Power cable systems and medium/high-voltage grid applications. |
| LEONI | Industrial, automotive and specialty cable systems. |
| LAPP Group | Industrial automation, connectivity and factory wiring solutions. |
| HELUKABEL | Control, power and specialty cables for industrial applications. |
| NKT | Medium/high-voltage cable systems and grid infrastructure. |
| Südkabel | High-voltage and engineered power-cable systems. |
| TKD Kabel | Industrial cables, installation wire and application-specific solutions. |
| Corning | Optical fiber and data connectivity cable solutions. |
| Belden | Industrial and enterprise data-cabling products. |
Utility cable tenders place significant emphasis on technical qualification, installation reliability and project delivery, while industrial buyers value custom assemblies, flexibility, EMC protection and chemical resistance. Fiber and datacom contracts increasingly require high-density connectivity, fire safety and rapid installation. Strategic priorities include utility project partnerships, specialty product development and customer-specific engineering services.
Germany Cables & Wires Market Recent Developments
2026: Transmission and distribution modernization activity continues to influence power-cable procurement, installation services and long-cycle utility qualification.
2026: Renewable-energy interconnection and offshore wind activity supports demand for export, underground and high-voltage cable systems.
2026: Industrial automation and plant-renovation programs continue to support flexible control cables, industrial Ethernet and specialty wiring.
2026: Data-center and network expansion creates opportunities in optical fiber, structured copper and critical-power cabling.
2026: Suppliers continue to emphasize product certifications, higher performance materials and installation-ready cable systems.
2026: Metal price movements, permitting timetables and specialized installation labor remain important commercial considerations.


























































