


GCC Data Center Cables & Wires Market Size and Overview
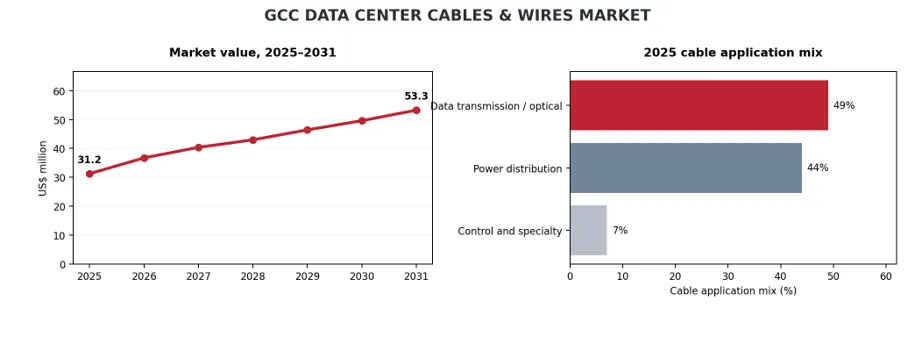
The GCC Data Center Cables & Wires Market was valued at US$ 31.25 million in 2025 and is forecast to reach US$ 53.26 million by 2031, representing 9.29% annualized growth over 2025–2031. Coverage spans optical and high-speed copper data cables, critical electrical feeders, low- and medium-voltage power distribution and control cabling for hyperscale, colocation, government, enterprise and edge data centers across six GCC countries.
Saudi Arabia and UAE anchor GCC data-center development, supported by sovereign AI programs, cloud-region investment and regional interconnection. Qatar, Bahrain, Oman and Kuwait offer additional colocation, sovereign hosting and digital-service requirements. Cable opportunities range from substations and dual electrical pathways to optical-fiber campus links, structured copper networks and high-density AI switching fabrics.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 31.25 Million | US$ 53.26 Million | 9.29% |
GCC Data Center Cables & Wires Key Takeaways
The GCC Data Center Cables & Wires Market rises from US$ 31.25 million in 2025 to US$ 53.26 million by 2031, equivalent to 9.29% annualized growth.
Saudi Arabia and the UAE lead data-center developments linked to sovereign cloud, hyperscale campuses and artificial-intelligence processing capacity.
High-density optical-fiber links and pre-terminated assemblies become more important as AI networks increase east-west traffic and port density.
Redundant power pathways, fire-rated cable systems and certified installation practices are essential for high-availability facilities.
Grid-connection availability, heat resilience and demanding project execution schedules favor suppliers with local support and reliable inventory.
Localization, material compliance, approved-vendor registration and country-specific permitting influence commercial conversion across GCC markets.
GCC Data Center Cables & Wires Industry Trends and Strategic Insights
AI-ready campuses increase demand for high-count fiber trunks, small-form-factor optical cabling and scalable cross-connect architectures.
Reliability design supports separated A/B power routes, screened control cables, fire-performance grades and robust circuit identification.
Modular campus deployment creates repeatable packages for prefabricated cable assemblies, plug-and-play network distribution and standardized electrical circuits.
Regional sourcing and project-stage visibility shape supplier choice, particularly where lead times and civil-work sequencing affect data-hall activation.
GCC Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 31.25 Million |
| 2031 Projected Market Size | US$ 53.26 Million |
| CAGR (2026–2031) | 9.29% |
| Geographic Coverage | Saudi Arabia, UAE, Qatar, Kuwait, Oman and Bahrain |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
The report covers Saudi Arabia, UAE, Qatar, Kuwait, Oman and Bahrain. It includes optical-fiber and copper data-network cabling, incoming and internal power cables, monitoring and control circuits and other application-specific cable installations for hyperscale, colocation, enterprise and edge data centers. Segmentation addresses cable type, application, data-center category, transmission medium, voltage, material and installation method.
GCC Data Center Cables & Wires Market White Space & Investment Opportunities
AI-network optical infrastructure: New halls and campus fiber links favor high-count cables, low-loss connectivity and factory-terminated solutions.
Certified power distribution: Redundant LV/MV feeders and low-smoke, fire-performance cables support mission-critical electrical systems.
Local project fulfillment: In-country inventory, installer qualification, containment design and phased supply contracts improve delivery competitiveness.
Saudi Arabia and UAE offer the largest concentration of GCC opportunities, while Qatar, Kuwait, Oman and Bahrain have selective high-value applications in sovereign hosting, cloud availability zones and critical digital infrastructure.
Driver Impact Analysis
Saudi AI data-center investment, sovereign hosting projects and hyperscale cloud development support demand for dense optical connectivity, dual-path electrical distribution and certified cabling. Large installations require early specification engagement with owner-engineers, EPC firms and MEP contractors. Multi-phase project execution can generate repeat orders for power and network cable packages.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| AI / hyperscale expansion | Power cabling, optical fiber and campus backbones | High | Pursue data-center design and MEP specification opportunities |
| Phased large-campus development | Incoming feeders, LV distribution and interbuilding fiber | High | Coordinate project-phase cable packages with contractors |
| Fiber network densification | High-count fiber trunks, structured copper and rack links | High | Prioritize prefabricated and tested connectivity systems |
| Retrofits and redundancy | UPS circuits, control wiring and fire-rated networks | Moderate–High | Offer rapid installation, compliance documents and aftersales support |
Expansion in the UAE and wider GCC attracts high-bandwidth campus interconnection, edge connectivity and resilience upgrades. Fiber-density growth and high-availability design increase the value of pre-terminated networks, low-smoke sheathing and traceable electrical circuits. Suppliers with installation engineering and local compliance support can capture a larger share of contracts.
Restraint Impact Analysis
Grid-connection lead times, heat-management infrastructure and permitting requirements can defer large campus construction. A mismatch between announced compute capacity and connected electrical capacity causes cabling tenders to move between project phases.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid connection and permitting | Large campus commissioning schedules | High | Link procurement to confirmed electrical connection milestones |
| Raw-material price variation | Copper, aluminum and specialty cables | High | Improve procurement flexibility and commercial indexation |
| Fire-safety qualification | Indoor power and networking specifications | High | Maintain verified CPR and fire-performance documentation |
| Installer and fiber-routing constraints | High-density campus deployment and retrofits | Moderate–High | Use prefabricated trunks and phased installation sequencing |
Copper and optical-component cost changes, imports, customs logistics and variations in fire-safety standards increase project execution risk. Competition for certified installation labor and compressed construction schedules can raise installed costs and force material substitutions.
GCC Data Center Cables & Wires Market Competitive Landscape
Competition spans GCC-based power-cable manufacturers, international optical-fiber specialists and structured-cabling systems suppliers. Ducab, Riyadh Cables Group, Oman Cables Industry, Bahra Electric, Doha Cables, Prysmian, Nexans, Corning, CommScope and Belden cover different elements of power and data cabling for critical digital facilities.
| COMPANY | GCC DATA CENTER CABLES & WIRES POSITIONING |
| Ducab | UAE-based electrical cable manufacturer active in mission-critical infrastructure and power distribution. |
| Riyadh Cables Group | Saudi cable supplier for electrical feeders, low- and medium-voltage distribution and infrastructure. |
| Oman Cables Industry | Regional LV/MV cable manufacturer serving industrial and commercial facilities. |
| Bahra Electric | Saudi power-cable and building-wire producer for critical electrical installations. |
| Doha Cables | Qatar-based manufacturer of power cables and building wires. |
| Prysmian | Optical fiber, communications systems and mission-critical electrical cable portfolio. |
| Nexans | Low- and medium-voltage cabling and fire-performance solutions for critical infrastructure. |
| Corning | High-density fiber and pre-terminated network connectivity for data centers. |
| CommScope | Structured copper and fiber network infrastructure for high-density facilities. |
| Belden | Industrial and data communications cabling for network reliability and control. |
Selection criteria include IEC and fire-performance qualifications, high-count fiber availability, low-loss network connectivity, A/B power redundancy, local fulfillment and access to approved MEP contractors. Suppliers that coordinate cable packages across data-center construction phases can differentiate.
GCC Data Center Cables & Wires Market Recent Developments
January 1, 2026 — Construction milestone: Saudi Arabia laid the foundation stone for SDAIA’s Hexagon government data center in Riyadh, planned for 480 MW total capacity and a Tier IV classification.
January 21, 2026 — Financing agreement: HUMAIN and Saudi Arabia’s National Infrastructure Fund announced a non-binding financing framework of up to US$1.2 billion supporting development of up to 250 MW of hyperscale AI data-center capacity.
March 4, 2026 — Product launch: Prysmian introduced Sirocco Ultra high-density optical microduct cables incorporating 160 µm optical fiber for applications that include data-center connectivity.
August 31, 2026 — Strategic partnership: center3 and Saudi Electricity Project Development Company announced cooperation on power feasibility studies, substation design and preparatory work for new data-center projects.
September 2026 — Regulatory change: Saudi Arabia adopted municipal requirements for commercial data centers covering licensing, Civil Defense approval, building design, backup electrical power and operational safeguards.
September 2026 — Infrastructure financing initiative: Saudi Arabia’s National Infrastructure Fund outlined its AI Data Center Financing Program for qualifying domestic AI facilities with Tier III-or-higher design and energy-efficiency criteria.


























































