France Data Center Transformer Market Overview
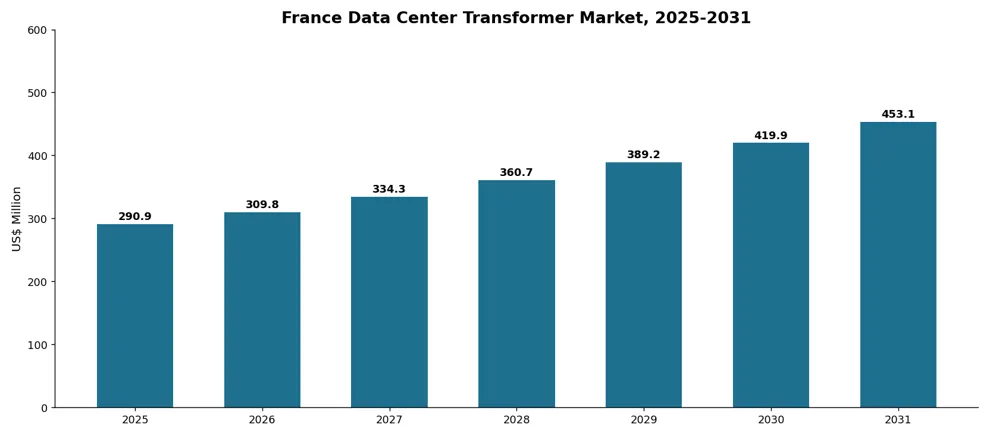
The France Data Center Transformer Market generated an estimated US$290.9 million in 2025 and is projected to reach approximately US$453.1 million by 2031, based on a 7.90% growth outlook for 2026-2033. New AI and hyperscale campuses, expanding colocation facilities and larger grid connections are increasing demand for power and distribution transformers. Equipment selection, available grid capacity and commissioning schedules influence when projects can be energized.
Transformers connect incoming grid supplies to site substations and medium-voltage distribution inside the campus. Large sites can require high-capacity primary transformers, medium-power units and dry-type distribution equipment for critical buildings. Buyers assess load growth, energy losses, fire safety, redundancy and maintenance access. France has a growing pipeline of projects seeking direct high-voltage connections, making early coordination with RTE and engineering contractors essential.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
| US$290.9 Million | US$453.1 Million | 7.90% |
France Data Center Transformer Key Takeaways
• France data center transformer revenue is estimated at US$290.9 million in 2025 and approximately US$453.1 million in 2031.
• New AI campuses and hyperscale projects are increasing demand for dedicated substations and large-capacity transformer packages.
• RTE reported nearly 18 GW of connection capacity reserved for around 80 data center projects in May 2026, highlighting a large long-term project pipeline.
• The Paris region and the Marseille area remain important for colocation and interconnection capacity, while new AI campuses are expanding to additional locations.
• Oil-immersed equipment supports large power connections, while dry-type transformers are important in indoor distribution and fire-sensitive areas.
• Suppliers are assessed on delivery reliability, grid compliance, efficiency, commissioning support and availability of local service teams.
France Data Center Transformer Industry Trends and Strategic Insights
• Hyperscale projects increasingly plan power infrastructure in stages, with substation and transformer packages ordered ahead of server-hall completion.
• France’s low-carbon power mix supports new AI infrastructure, although available connection capacity differs widely by site and voltage level.
• Developers are evaluating modular transformer substations, low-loss designs, alternative dielectric fluids and digital condition monitoring.
• Project awards increasingly depend on utility acceptance, lead-time credibility, delivery logistics and coordinated engineering of the full electrical chain.
France Data Center Transformer Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$290.9 Million |
| 2031 Projected Market Size | US$453.1 Million |
| CAGR (2026–2031) | 7.90% |
| By Transformer Type | Distribution transformers, medium-power, large-power, modular substations |
| By Data Center Type | Hyperscale, AI, cloud, colocation, enterprise and edge data centers |
| By Voltage Rating | Secondary distribution, medium voltage, high voltage and grid connections |
| By Insulation and Cooling | Oil-immersed, natural and synthetic ester, dry-type and cast resin |
| By Power Architecture | Utility-fed substations, campus primary power and downstream distribution |
| By Phase and Installation | Three-phase, pad-mounted, indoor, outdoor and modular units |
| By Installation Stage | New campus construction, expansion, retrofit, replacement and aftermarket |
| Competitive Landscape | 10 manufacturers and specialist transformer suppliers serving French critical-load demand |
| Market Data Coverage | 2025-2031 France data center transformer market, equipment applications and trends |
Coverage: France. The report covers transformers serving hyperscale, cloud, AI, colocation, enterprise and edge data centers. It includes utility interconnection transformers, campus medium-voltage distribution, dry-type equipment, modular substations, new-build projects, expansions, replacement demand and transformer maintenance services.
France Data Center Transformer Market White Space & Investment Opportunities
• Major campus grid interfaces: pursue high-capacity transformers and primary substation packages for projects with confirmed connection milestones.
• Repeatable building-level distribution: offer modular substations, dry-type transformers and lower-loss designs for staged data center expansions.
• Services and project delivery: develop installation, field testing, monitoring, spare-transformer and commissioning capabilities near key clusters.
Converting announced projects into transformer orders requires early engagement with RTE, campus developers, consulting engineers and electrical EPCs. Suppliers with qualified designs, dependable manufacturing slots and local service coverage are better positioned for phased, multi-site procurement.
Driver Impact Analysis
France is attracting large-scale AI campus proposals that require new grid-interface substations and several levels of downstream power conversion. RTE reported nearly 18 GW of reserved connection capacity across about 80 data center projects in May 2026, compared with around 5 GW across 40 projects at the end of 2024. Even where not all projects proceed, this pipeline gives transformer manufacturers a growing set of high-capacity opportunities. Planning early helps align transformer ratings, production slots and grid acceptance with project schedules.
| DRIVER | IMPACT LEVEL | PRODUCT / DEMAND SIGNAL | STRATEGIC IMPACT |
| AI and hyperscale campus development | High | Primary substations and high-capacity transformers | Engage on grid connection and reserve qualified factory capacity |
| Colocation growth and phased expansion | High | Modular substations and medium-voltage equipment | Offer repeatable power blocks and on-site commissioning |
| Grid connection and power availability | Medium-High | Large grid-interface transformer packages | Align transformer specifications with RTE milestones |
| Efficiency and critical-load resilience | High | Low-loss dry-type units and monitoring | Demonstrate lifecycle performance and service readiness |
Hyperscale facilities also need transformers that can support phased expansion without major shutdowns. Developers are increasingly considering standard electrical blocks, low-loss equipment and condition monitoring to manage the lifetime cost of critical infrastructure. Paris-area colocation expansion, Marseille’s connectivity role and new projects in northern France and Bordeaux create demand across primary power, medium-voltage distribution and replacement applications. Renewable and low-carbon power availability adds to France’s appeal for energy-intensive sites.
Restraint Impact Analysis
Grid availability and approval timing are major restraints. Many proposed data centers request direct high-voltage connections, but the final capacity and energization dates depend on network studies, reinforcement works and contractual milestones. Large demand forecasts do not automatically translate into immediate equipment orders. Transformer suppliers must distinguish projects with firm power arrangements from early-stage announcements, while developers need to avoid procurement commitments that are poorly aligned with grid delivery.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid connection and permitting uncertainty | High-voltage transformers and primary substations | High | Confirm connection milestones before production release |
| Long factory lead times | Large and medium-power transformers | High | Secure capacity early with approved alternate specifications |
| Copper and electrical-steel costs | Cores, windings and insulation materials | Medium-High | Include price protection and qualified dual sourcing |
| Complex project changes and site access | Utility acceptance, transportation and commissioning | Medium-High | Freeze design early and plan delivery and installation |
Supply-side constraints are also material. Medium- and large-power transformers may face long factory queues, specialized steel and copper exposure, extensive testing and complex transport into urban or industrial sites. Changes in load density, voltage level or redundant architecture can trigger redesign and additional approvals. Competition with grid-modernization orders may constrain manufacturing capacity. Buyers increasingly value specification freeze, approved alternatives, realistic delivery windows and strong local commissioning support.
France Data Center Transformer Market Competitive Landscape
The French data center transformer market brings together global manufacturers, European transformer specialists and French electrical-infrastructure suppliers. Large projects require utility-compatible transformer designs, manufacturing capacity, factory acceptance testing and reliable commissioning. Local presence is valuable for permitting interfaces, maintenance and replacement support.
| COMPANY | DATA CENTER TRANSFORMER POSITIONING |
| Hitachi Energy | Power and distribution transformers for major grid interfaces and high-capacity data center substations |
| GE Vernova | Large power transformers and grid engineering for French high-voltage infrastructure |
| Siemens Energy | Large transformer and grid-interface engineering for hyperscale power connections |
| Groupe Cahors | French distribution transformer and electrical distribution equipment for campus power supply |
| SGB-SMIT Group | European power and distribution transformers with dry-type and oil-immersed options |
| Eaton | Dry-type distribution and integrated electrical infrastructure for critical facilities |
| TMC Transformers | Dry-type transformer designs for indoor distribution and specialist installations |
| SEA Trasformatori | Medium-power and specialty transformers for engineered industrial and infrastructure loads |
| Mitsubishi Electric | Large power equipment for substation and transmission-related applications |
| Schneider Electric | France-based integration of data center power distribution and transformer-related electrical systems |
Competition differs by equipment class. High-capacity grid-interface transformers favor established power-equipment manufacturers, while medium-voltage and dry-type distribution products have broader supplier participation. Integrated electrical suppliers may lead customer specifications without manufacturing every transformer in the system. Buyers increasingly consider lifecycle losses, spare units, monitoring and service response alongside capital cost.
France Data Center Transformer Market Recent Developments
• February 12, 2026: Nebius outlined a phased 240 MW data center development at the former Bridgestone plant in Béthune. The project increases the potential need for new high-capacity electrical connections and site transformers.
• February 25, 2026: Vantage Data Centers and Altarea announced plans for a 400 MW campus near Bordeaux. Altarea reported that a 400 MW power connection had already been secured for the site.
• May 30, 2026: EDF selected SoftBank as preferred bidder for a proposed 400 MW data center at its former Bouchain power station site, subject to further studies and permissions.
• May 30, 2026: SoftBank announced a proposed 5 GW AI data center program in France, including a first-phase 3.1 GW plan in Hauts-de-France and a 1 GW campus proposal at Bosquel.
• July 3, 2026: EDF launched a new call for expressions of interest for a high-power data center on its former Creys-Mépieu industrial site, highlighting the importance of existing grid infrastructure.
• October 15, 2026: RTE announced consultation on Google’s proposed Ozans data center and its grid connection. The first phase is planned around a 120 MW, 225 kV connection, with a possible later 400 kV connection.