France Data Center Motors and Drives Market Overview
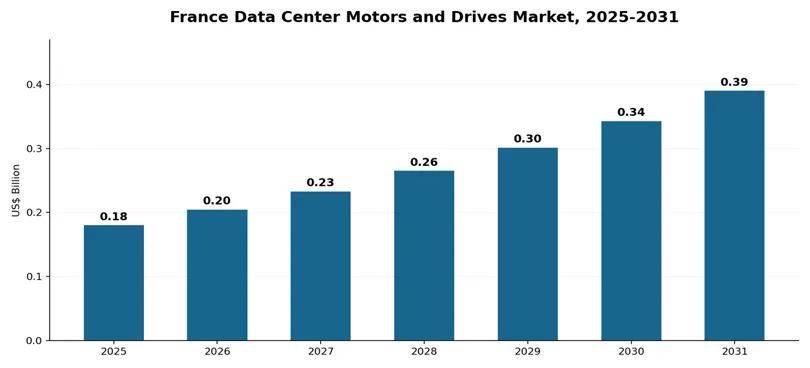
The France Data Center Motors and Drives Market is estimated at US$ 0.18 billion in 2025 and is projected to reach US$ 0.39 billion by 2031, representing approximately 13.75% annualized growth. France is building larger cloud and AI data center facilities, particularly around Paris and emerging northern industrial locations. This expansion is increasing requirements for motors and variable-frequency drives used in chilled-water pumping, ventilation, heat rejection and coolant circulation. Project scale and mechanical redundancy are key demand factors.
The study measures standalone motors, variable-frequency drives and integrated motor-drive assemblies installed in data center mechanical services. This includes pump, fan and selected chiller-drive applications in new facilities, campus extensions and operating-site upgrades. It excludes complete chillers, pumps, coolant distribution units and other packaged cooling equipment from the revenue total. The forecast is a directional equipment-level estimate based on data center investment, cooling architecture and replacement demand.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026-2031) |
| US$ 0.18 Billion | US$ 0.39 Billion | 13.75% |
France Data Center Motors and Drives Key Takeaways
Data center motor and drive revenue is estimated to rise from US$ 0.18 billion in 2025 to US$ 0.39 billion by 2031.
The Paris market remains the main installed base, while proposed AI campuses in northern France could expand future mechanical-equipment demand.
High-density AI installations increase requirements for resilient coolant-circulation motors, redundant pumps and high-availability fan systems.
Variable-frequency drives support part-load energy savings and tighter temperature control in chilled-water and air-handling systems.
French operators place growing emphasis on cooling electricity use, heat reuse and equipment maintainability.
Cooling OEM qualification, commissioning support and local spare-parts availability are decisive factors for component suppliers.
France Data Center Motors and Drives Industry Trends and Strategic Insights
New facilities are combining air-based cooling with direct-to-chip and liquid-cooling systems, changing the balance between fan and pump motor demand.
Mechanical contractors increasingly purchase complete pump and air-handling packages, making OEM design-in more important than late-stage component quotations.
Efficiency requirements favor variable-speed pumping, premium-efficiency motors and building-management-system integration.
Local service teams and standardized drive families improve repair response and spare-part availability across multi-site operators.
France Data Center Motors and Drives Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 0.18 Billion |
| 2031 Projected Market Size | US$ 0.39 Billion |
| CAGR (2026-2031) | 13.75% |
| By Drive Type | AC induction and permanent-magnet pump and fan motors, low- and medium-voltage VFDs |
| By End-Use Industry | Hyperscale, cloud, colocation, enterprise and edge data centers |
| By Power Rating | Chilled water, condenser water, HVAC fans, cooling towers and liquid cooling |
| By Voltage | Below 7.5 kW, 7.5-37 kW, above 37-200 kW and above 200 kW |
| By Control Method | IE3 and IE4 motors, vector control, VFD-based variable flow and BMS interfaces |
| By Application | Mechanical rooms, rooftop cooling and packaged liquid-cooling systems |
| By Installation Stage | New-build, campus expansion, retrofit and scheduled replacement |
| Competitive Landscape | 10 motor, drive, pumping and thermal-management suppliers relevant to France |
| Market Data Coverage | 2025-2031 directional equipment-revenue forecast, applications and market trends |
Coverage: France. The report covers motors and industrial drives used in hyperscale, colocation, cloud, enterprise and edge data center mechanical services, including pumps, fans, cooling towers, chilled-water equipment, liquid-cooling loops and related replacement demand. It excludes full cooling-system revenue and counts motors or drives supplied in packaged equipment only at their component value.
France Data Center Motors and Drives Market White Space & Investment Opportunities
Liquid-cooling circulation: qualify efficient motors and VFDs for redundant coolant distribution and secondary water loops.
Brownfield upgrades: offer variable-speed drive retrofits, fan-motor replacement and controls integration without extended downtime.
Local service programs: establish stocked replacements, condition-monitoring support and commissioning coverage near Paris and emerging campuses.
Vendors should reach cooling OEMs, MEP contractors, consultants and data center operators during early mechanical design. Proven performance, lifecycle support and accepted spare-part strategies are important for multi-building campus purchasing.
Driver Impact Analysis
France’s data center construction pipeline is increasing demand for chilled-water and condenser-water pump motors, CRAH and air-handling fan motors, chiller auxiliaries and variable-speed drive systems. Hyperscale campuses require multiple mechanical plant trains, and redundancy increases installed motor and drive counts beyond the operating duty requirement. New AI applications also require more sophisticated circulation and heat-rejection arrangements as server density rises. Suppliers that engage early with packaged cooling-system manufacturers can win repeat equipment placements across multiple project phases.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 IMPACT | STRATEGIC IMPACT |
| Hyperscale and colocation buildout | High | New cooling plant, pump and fan motor packages | Secure OEM design-in before mechanical specifications are frozen |
| Liquid cooling and AI density | High | Additional coolant distribution and redundancy duty | Qualify motor-drive assemblies for flexible cooling architectures |
| Efficiency and heat reuse | High | VFD upgrades, premium motor replacements and circulation | Demonstrate part-load energy savings and BMS interoperability |
| Reliability and lifecycle support | Medium-High | Diagnostics, local spares and rapid replacement | Build French service coverage and consistent approved product ranges |
Energy performance is a second major driver. Variable-speed control allows pump and fan output to follow changing thermal loads, while premium-efficiency motors reduce continuous electricity use. Liquid cooling increases circulation duty even where the number of conventional air-handling fans decreases. Heat-reuse schemes also create opportunities for additional pumping and control equipment. Data center operators increasingly favor motors, drives and sensors that can communicate with building-management systems and support fault diagnosis before critical cooling performance is affected.
Restraint Impact Analysis
Motor and drive purchasing is frequently included within broader chiller, pump or air-handling equipment contracts. That bundling makes standalone component spending harder to identify and limits access for companies without approved-OEM relationships. France’s largest planned projects also face sequencing risks from land development, grid connection, permitting and funding decisions. Equipment suppliers can lose production visibility when site energization or mechanical design completion is deferred. Highly specialized uptime requirements increase testing, documentation and qualification costs.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| OEM-bundled procurement | Pumps, chillers and air-handling equipment | High | Develop relationships with French MEPs and cooling OEMs |
| Project timing and grid availability | Construction releases and energization dates | High | Align manufacturing slots with confirmed project milestones |
| Live-site retrofit risk | Existing controls, EMC and electrical redundancy | Medium-High | Plan compatibility testing and minimal-downtime replacement |
| Cooling-design uncertainty | Shifting fan and pump demand in hybrid systems | Medium-High | Offer modular drives and broad motor operating envelopes |
Retrofits at live sites require short maintenance windows and high confidence in compatibility with existing power quality, PLC and building-management systems. Harmonic distortion, electromagnetic compatibility and bypass arrangements can complicate drive upgrades. Rapid changes in air-versus-liquid cooling configurations also alter the motor and drive product mix between design and procurement. Supplier strategies should include flexible drive selections, local replacement stock, early engineering coordination and explicit definition of component value inside packaged mechanical equipment.
France Data Center Motors and Drives Market Competitive Landscape
France is served by European and global industrial motor suppliers, VFD specialists, fan manufacturers, pump OEMs and data center thermal-management firms. Competition is shaped by energy efficiency, proven reliability, liquid-cooling capability, BMS interoperability, service response and inclusion on approved mechanical-OEM lists. Schneider Electric, ABB, Danfoss and Siemens compete in motor control and drives, while pump and cooling-system companies influence the installed equipment specification.
| COMPANY | DATA CENTER MOTORS AND DRIVES POSITIONING |
| Schneider Electric | Soft starters, Altivar drives and data center motor-control solutions with extensive French engineering channels. |
| ABB | High-efficiency motors and AC drives for pumping, ventilation and heat-rejection equipment. |
| Danfoss Drives | VLT and VACON variable-speed drives for chilled-water pumps, fans and cooling utilities. |
| Siemens | SIMOTICS motors, SINAMICS drives and associated building/mechanical equipment controls. |
| Nidec Leroy-Somer | France-based industrial motor heritage and premium-efficiency motor products for mechanical OEMs. |
| WEG | Industrial motors and drives for ventilation and continuous-duty pumping applications. |
| Grundfos | Pump systems and variable-speed solutions for water circulation and cooling infrastructure. |
| Carrier | Cooling plants, CDUs and control systems that influence motor and pump drive specification. |
| ebm-papst | High-efficiency electronically commutated fan motors for air movement and heat rejection. |
| Vertiv | Thermal management solutions and cooling upgrades that influence integrated motor and drive demand. |
Data center mechanical packages are often specified by engineering consultants and equipment OEMs before final construction procurement. Suppliers with local commissioning capacity, proven compliance and predictable spare-part support are better placed to secure repeat installations across French data center portfolios.
France Data Center Motors and Drives Market Recent Developments
January 13, 2026: Carrier introduced a new coolant distribution unit from Montluel, France. Its secondary-loop controls are designed to optimize coolant flow and pumping energy in liquid-cooled data centers.
April 2, 2026: Carrier opened an expanded testing facility at Montluel to support high-performance HVAC and data center cooling development and validation.
May 14, 2026: Digital Realty and Equans Data Centers advanced construction of PAR15 at Dugny near Paris. The development will add a new mechanical and electrical infrastructure procurement opportunity.
May 30, 2026: Schneider Electric announced a strategic technology partnership supporting SoftBank’s planned AI data center investments in France, including proposed northern France campuses.
July 20, 2026: Vertiv reported the modernization of cooling infrastructure at French operator NFrance, delivering an approximately 20% reduction in cooling power consumption while keeping operations active.
September 23, 2026: Schneider Electric introduced the Motivair WCDU, combining integrated pumps and heat exchangers for hybrid air-and-liquid cooled AI data centers.