


France Data Center Cables & Wires Market Size and Overview
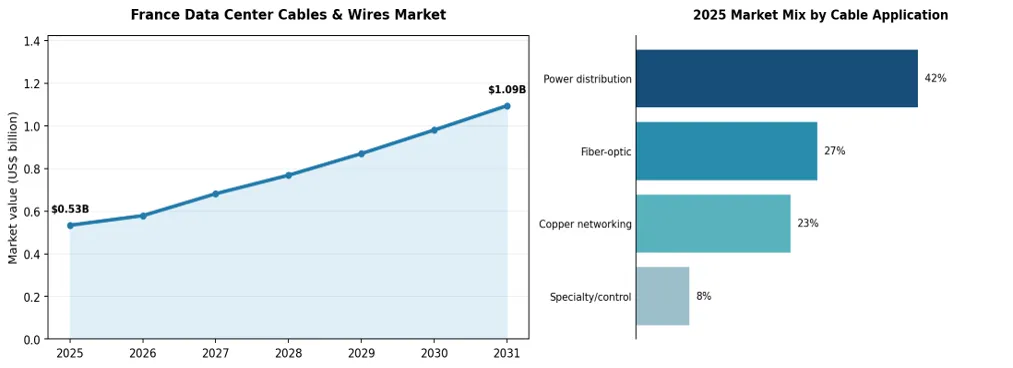
The France Data Center Cables & Wires Market was valued at US$ 0.53 billion in 2025 and is forecast to reach US$ 1.09 billion by 2031, registering a CAGR of 12.71% from 2025 to 2031. The market encompasses low- and medium-voltage power distribution cables, optical fiber links, structured copper cabling and fire-rated control wiring deployed across hyperscale, colocation, enterprise and edge data centers.
Demand is concentrated in Paris and Île-de-France with additional investment in Marseille, Lille and emerging industrial redevelopment sites in northern France. Large cloud and AI facilities require dense fiber cabling and robust electrical distribution from substations to UPS, backup generation, PDUs and computing halls. Data-center retrofits also generate recurring requirements for high-fiber-count links, LSZH cabling and structured copper replacements.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 9.41 Billion | US$ 11.04 Billion | 2.71% |
France Data Center Cables & Wires Key Takeaways
The France Data Center Cables & Wires Market is forecast to rise from US$ 0.53 billion in 2025 to US$ 1.09 billion by 2031.
Market growth of 12.71% reflects large campus announcements, cloud capacity additions and upgrade projects for AI-focused computing infrastructure.
Power-distribution cables remain integral to grid interfaces, electrical redundancy, UPS routes and backup-power systems within large campuses.
Optical fiber demand benefits from higher-density internal connections, inter-building links and higher-speed networking requirements.
French specifications emphasize low-smoke, fire-performance and installation traceability across critical data-center facilities.
Demand clusters around Paris and Île-de-France, while Marseille and Northern France create opportunities for new campus and connectivity corridors.
France Data Center Cables & Wires Industry Trends and Strategic Insights
Cloud and AI facilities are adopting fiber-dense structured cabling, preterminated trunk systems and faster rack-to-rack deployment approaches.
Redundancy designs create demand for separate cable paths, validated fire ratings and documentation of low-voltage critical-power installations.
Capacity additions increase interest in compact cable routes, modular data halls and faster field commissioning by specialist installers.
Procurement increasingly evaluates sustainability declarations, efficient cable use, supply availability and the ability to serve repeated campus phases.
France Data Center Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 0.53 Billion |
| 2031 Projected Market Size | US$ 1.09 Billion |
| CAGR (2026–2031) | 12.71% |
| Geographic Coverage | France: Paris and Île-de-France, Marseille, Lille, northern France and emerging campus corridors |
| By Cable Type | Power Cables (Medium-Voltage Feeders, Low-Voltage Distribution, UPS and Backup Connections); Datacom Cables (Fiber Optic, Structured Copper Ethernet, Coaxial and Specialty Interconnects); Control and Security Cables; Fire-Resistant and Low-Smoke Cables |
| By Industry / Data Center Type | Hyperscale and Cloud Data Centers; Colocation Data Centers; Enterprise Data Centers; Edge Data Centers; AI and High-Performance Computing Facilities |
| By Conductor / Transmission Medium | Copper; Aluminum; Single-Mode Optical Fiber; Multimode Optical Fiber; Hybrid Power/Data |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (1–35 kV); High Voltage (above 35 kV); Data and Signal Cables |
| By Insulation and Sheathing Material | XLPE; PVC; LSZH/LSHF; EPR/EPDM; PE and Flame-Retardant Jackets |
| By Installation Method | Underground and Grid Connections; Indoor Cable Trays; Overhead Containment; Raised-Floor Routes; In-Rack and In-Row Connections |
| Competitive Landscape | 10 Company Profiles, Product Positioning, Commercial Developments and Partnerships |
| Market Data Coverage | 2025–2031 Market Forecast, Segmentation, Application Mix, Drivers, Restraints and Competitive Coverage |
The report covers data-center-specific power and network cabling by cable type, facility category, end-use application, conductor or transmission medium, voltage rating, installation method plus insulation and sheathing materials. Each market segmentation is consolidated into one row in the Market Scope table.
France Data Center Cables & Wires Market White Space & Investment Opportunities
High-density networking: Faster AI interconnects increase demand for higher-fiber-count cable backbones and preterminated link architectures.
Critical-power distribution: Larger electrical loads increase opportunities in feeders, UPS connections, generator circuits and certified control wiring.
Campus phased build-out: New French hyperscale parks open cable supply opportunities spanning incoming grid lines, data halls and interbuilding fiber networks.
Paris and its surrounding region remain the core commercial destination for French data-center cabling. Marseille is important for international connectivity and northern France is emerging as a site for large campus developments. Supplier engagement depends on early MEP specifications, grid access, qualification status and delivery coordination with power and networking contractors.
Driver Impact Analysis
Hyperscale and AI-oriented capacity growth is increasing demand for medium-voltage site interfaces, low-voltage distribution circuits and dense datacom backbones. Project announcements in France support multiyear opportunities across new-build electrical packages, phased equipment hall deployment and specialized fit-outs. In operating facilities, modernization of fiber and copper networks plus UPS-related electrical changes support recurring installation demand.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| AI / hyperscale expansion | Power cabling, optical fiber and campus backbones | High | Pursue data-center design and MEP specification opportunities |
| Phased large-campus development | Incoming feeders, LV distribution and interbuilding fiber | High | Coordinate project-phase cable packages with contractors |
| Fiber network densification | High-count fiber trunks, structured copper and rack links | High | Prioritize prefabricated and tested connectivity systems |
| Retrofits and redundancy | UPS circuits, control wiring and fire-rated networks | Moderate–High | Offer rapid installation, compliance documents and aftersales support |
Cloud deployment and higher rack-density designs increase demand for certified structured networking products, tight-bend fiber solutions and modular termination systems. French engineering teams are placing greater emphasis on fire performance, routing separation, installation documentation and reliable capacity planning. Suppliers combining product availability with engineering and contractor support have opportunities across both hyperscale projects and the retrofit cycle.
Restraint Impact Analysis
Access to grid connections, planning approvals and specialist installation resources can shift timing for data-center developments, delaying related cable orders. Project budgets remain sensitive to copper and aluminum costs, optical fiber delivery schedules and specialist components. Qualification requirements for fire and smoke behavior can lengthen the product-approval cycle, particularly in large facilities with tightly controlled operating standards.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Grid connection and permitting | Large campus commissioning schedules | High | Link procurement to confirmed electrical connection milestones |
| Raw-material price variation | Copper, aluminum and specialty cables | High | Improve procurement flexibility and commercial indexation |
| Fire-safety qualification | Indoor power and networking specifications | High | Maintain verified CPR and fire-performance documentation |
| Installer and fiber-routing constraints | High-density campus deployment and retrofits | Moderate–High | Use prefabricated trunks and phased installation sequencing |
Large campuses frequently need coordination between power-distribution engineering, structured cabling installation and commissioning teams. Dense network paths and mechanical containment constraints can drive redesign or phased purchasing. Suppliers can reduce delivery risk through preterminated systems, traceable testing, harmonized specifications, documented fire performance and staggered fulfillment against construction milestones.
France Data Center Cables & Wires Market Competitive Landscape
The France Data Center Cables & Wires Market brings together manufacturers of critical-power cabling, optical fiber, structured copper and specialty facility wiring. Relevant competitors include Nexans, Prysmian, Acome, Corning, CommScope, Legrand, Schneider Electric, Belden, LAPP and HELUKABEL. Product positioning varies between cable production, certified system solutions and integrated connectivity portfolios.
| COMPANY | FRANCE DATA CENTER CABLES & WIRES POSITIONING |
| Nexans | Medium-voltage grid feeders, low-voltage distribution and fire-safe building cable systems |
| Prysmian | Power cables and optical-fiber cable portfolios for digital infrastructure |
| Acome | French optical fiber and copper communication cable manufacturing |
| Corning | Optical fiber and high-density data-center cabling systems |
| CommScope | Structured copper, fiber distribution and enterprise connectivity systems |
| Legrand | Structured cabling, network connectivity and critical infrastructure systems |
| Schneider Electric | Critical-power distribution and associated electrical connectivity solutions |
| Belden | Industrial and data-center copper and optical connectivity |
| LAPP | Power, control and industrial cable solutions |
| HELUKABEL | Low-voltage power and control cables for facility infrastructure |
Competitive advantage depends on product qualification, fire-performance certification, lead time, fiber density and ability to support French and European project specifications. Hyperscale procurement favors consistent multi-site systems and dependable deliveries. Local installers and MEP design contractors have substantial influence over supplier selection during the specification and commissioning stages.
France Data Center Cables & Wires Market Recent Developments
June 2026 — Major data-center expansion: Data4 announced the launch of its €5 billion data-center campus project at Escaudain in northern France. The redevelopment of the former industrial site supports a new multiyear pipeline of power-distribution and network cabling requirements.
June 2026 — French cable manufacturing investment: Prysmian announced more than €28 million in additional investment commitments across industrial sites in France at the Choose France summit, supporting domestic cable manufacturing capabilities.
Q2 2026 — Data-center facility expansion: Equinix listed its Paris PA12x xScale data center among new facilities scheduled for the second quarter of 2026, supporting additional electrical distribution and fiber-network installation activity.
February 2026 — Major supply contract: Nexans secured a €600 million, seven-year agreement with Enedis for medium-voltage cable supplies to modernize France’s distribution grid. Deliveries were scheduled to begin in the first quarter of 2026, with cables primarily produced at Bourg-en-Bresse.
February 2026 — Production capacity investment: Nexans highlighted a €15 million investment at its Bourg-en-Bresse operation to increase output for larger-section aluminum and reinforced-direct-burial medium-voltage cables, strengthening French grid cable supply capability.
May 2026 — Data-center market positioning: Nexans presented major data-center contracts in the US and Europe in materials for its annual shareholders’ meeting, underlining commercial demand for specialist electrical-cable offerings.


























































