


France Cables & Wires Market Size and Overview
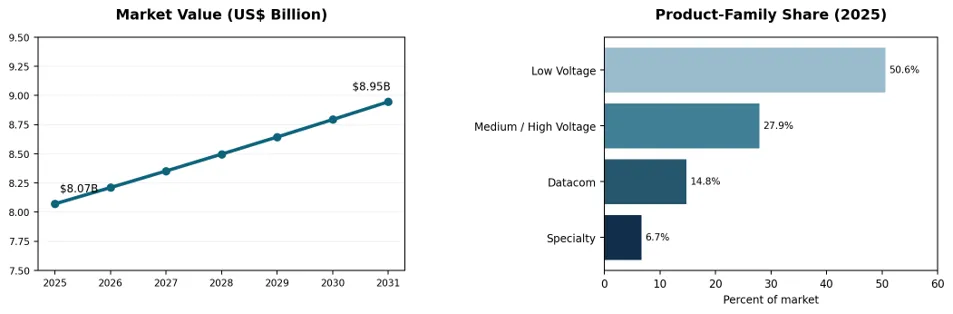
The France cables and wires market reached US$ 8.07 billion in 2025 and is projected to total US$ 8.95 billion by 2031, at an annualized growth rate of 1.73% over 2025–2031. Demand spans power distribution, industrial wiring, datacom connectivity and specialized infrastructure.
France’s market is shaped by Enedis distribution-network upgrades, RTE electricity transmission investment, offshore wind export cable systems, industrial plant renewal and fiber-network connectivity. High-voltage interconnection works and demand for low-carbon cable production are influencing supply strategies and specification standards.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 8.07 Billion | US$ 8.95 Billion | 1.73% |
France Cables & Wires Key Takeaways
• The France cables and wires market is forecast to increase from US$ 8.07 billion in 2025 to US$ 8.95 billion in 2031.
• The market is projected to record 1.73% annualized growth from 2025 to 2031, with stronger opportunity pockets in grid connections, offshore transmission and specialized fire-safe cabling.
• Low Voltage cables represented 50.60% of France’s 2025 cables and wires market, supported by electricity infrastructure, construction, industrial installations and digital networks.
• Medium / High Voltage cables represented 27.92% of France’s 2025 cables and wires market, supported by electricity infrastructure, construction, industrial installations and digital networks.
• Datacom cables represented 14.77% of France’s 2025 cables and wires market, supported by electricity infrastructure, construction, industrial installations and digital networks.
• Specialty cables represented 6.71% of France’s 2025 cables and wires market, supported by electricity infrastructure, construction, industrial installations and digital networks.
France Cables & Wires Industry Trends and Strategic Insights
• Distribution-network reinforcement is prioritizing medium-voltage cables, underground systems and security of supply under multi-year utility procurement frameworks.
• Offshore wind and cross-border interconnectors are expanding demand for export circuits, subsea HVDC cable systems and installation services.
• France’s automotive, aerospace, rail, industrial automation and nuclear supply chains sustain demand for fire-resistant, shielded and specialty cable products.
• Telecom fiber extension, data-center demand and electrified transport are increasing technical differentiation in cabling design and installation.
France Cables & Wires Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 8.07 Billion |
| 2031 Projected Market Size | US$ 8.95 Billion |
| CAGR (2026–2031) | 1.73% |
| Geographic Coverage | France (national market and principal industrial, energy and utility demand clusters) |
| By Cable Type | Datacom Cables (Communication & Data Cables, Fiber Optic Cables); Low-Voltage Cables (Fire Resistant Cables, Low Smoke & Halogen Free Cables, Low Voltage Cables & Wires); Medium- and High-Voltage Cables (Medium Voltage Cables, High Voltage Cables); Special Cables (Mining Oil & Gas Cables, Photovoltaic Cables, Ship & Harbour Cables, Windmill Cables) |
| By Industry | Industrial — Discrete (Aerospace & Defense, Automotive, Batteries, Electrical & Electronics, Machine Building, Semiconductor); Process (Chemicals, Energy/Oil & Gas, Metal Processing); Hybrid (Food & Beverage, Lifesciences, Mining & Quarrying, Other Manufacturing). Non Industrial — Transportation (Air, Land, Rail, Marine Services); Infrastructure & Services (Commercial Real Estate, Data Centers, Healthcare, Hospitality & Entertainment, Public Sector/Research/Education, Residentials, Water & Waste, Others). Power Utilities — Power Generation (Coal, Conventional Excl. Coal, Renewables); Power Distribution & Transmission. |
| By Conductor / Transmission Medium | Copper; Aluminum; Optical Fiber; Composite / Hybrid Construction |
| By Voltage Rating (Power Cables) | Low Voltage (up to 1 kV); Medium Voltage (above 1 to 35 kV); High Voltage (above 35 to 230 kV); Extra-High Voltage (above 230 kV) |
| By Insulation and Sheathing Material | Cross-Linked Polyethylene (XLPE); Polyvinyl Chloride (PVC); Ethylene Propylene Rubber (EPR/EPDM); Polyethylene (PE); Low Smoke Zero Halogen (LSZH); Other Materials |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, market developments and partnerships |
| Market Data Coverage | Cable-family and cable-subtype market values, 2025–2031 (US$ million); segmentation, competition and market dynamics |
The study covers France’s cables and wires market across datacom, low-voltage, medium-/high-voltage and specialty cable families. Additional segmentations span industrial and non-industrial end users, power utilities, conductor / transmission medium, voltage class, insulation material and installation method.
France Cables & Wires Market White Space & Investment Opportunities
• Grid contracts: Underground medium-voltage replacement, interconnection corridors and grid resiliency programs support long-term supply opportunities.
• Specialty production: Industrial automation, automotive electrification, aerospace and transport demand qualified, flexible and low-smoke products.
• Offshore and digital infrastructure: Submarine export cables, terrestrial fiber, structured datacom cabling and high-capacity connectivity create differentiated demand.
Priority French industrial and infrastructure clusters include Île-de-France, Auvergne-Rhône-Alpes, Hauts-de-France, Normandy, Brittany and Nouvelle-Aquitaine.
Driver Impact Analysis
French grid reinforcement and renewable integration are expanding the installed base of medium- and high-voltage cable systems. Enedis multi-year frameworks support manufacturing visibility while RTE interconnectors and wind export connections require factory qualification, installation coordination and maintenance readiness. Suppliers that secure specification approval early can improve execution certainty across successive project phases.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Grid reinforcement and power-system modernization | MV/HV underground and transmission cables | High | Utility qualification and contractor partnerships. |
| Renewable integration and offshore connections | HV cables, specialty and power interconnects | High | Target renewable developers, system operators and EPC firms. |
| Industrial automation and electrification | Industrial, control and low-voltage wiring | Moderate–High | Support industrial specifications and automated factories. |
| Fiber and data-center infrastructure | Optical fiber and structured copper | Moderate–High | Engage data-center integrators and network operators. |
Domestic manufacturing and certified low-carbon cable offerings support differentiation in French public and utility tenders. Demand for data transmission, fire-safe building wiring and electrified industrial equipment expands product breadth beyond conventional utility cables.
Restraint Impact Analysis
Copper and aluminum cost swings, energy-intensive manufacturing, offshore installation schedules and specialized vessel availability can affect delivery profitability. Infrastructure permits, grid-connection sequencing and extended customer qualification requirements may defer revenue recognition even when underlying demand remains intact.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Copper and aluminum price fluctuations | Contract margins and inventory funding | High | Metal-index procurement and contract protection. |
| Planning and grid-project delays | Project order conversion and scheduling | High | Strengthen pipeline management and stagger capacity. |
| Testing and engineering qualification | Utilities and mission-critical products | Moderate–High | Earlier type testing and design support. |
| Cost competition in standard cable products | Basic low-voltage and building wire | Moderate | Differentiate through quality, service and specialty products. |
Standard building wire faces price competition while high-voltage product qualification creates capacity bottlenecks. Suppliers can manage these pressures through metal-indexation clauses, dual sourcing, capacity reservation, installation partnerships and tighter project-stage forecasting.
France Cables & Wires Market Competitive Landscape
France combines domestic cable manufacturing leaders with international high-voltage, specialty and data-connectivity suppliers. Procurement favors technical qualification, product traceability, life-cycle reliability, certified fire performance and demonstrated utility-delivery capability.
| COMPANY | GERMANY CABLES & WIRES POSITIONING |
| Nexans | French-headquartered group with strong transmission, subsea and medium-voltage capabilities. |
| Prysmian | Energy and telecom cable manufacturer with extensive French industrial presence. |
| ACOME | French cooperative specializing in fiber and copper cable systems. |
| Axon’ Cable | French specialist in high-performance cables and interconnect systems. |
| NKT | Supplier of high-voltage transmission systems and offshore cable solutions. |
| LAPP Group | Industrial control, automation and specialty cable portfolio in France. |
| HELUKABEL | Industrial cable portfolio for automation and machinery manufacturers. |
| LEONI | Automotive and industrial wiring systems with European customer exposure. |
| TKD Kabel | Industrial cable distribution and technical supply capabilities. |
| CAE Groupe | French supplier and distributor of low-voltage, datacom and infrastructure cables. |
Competitive differentiation increasingly depends on HVDC and subsea capabilities, low-carbon manufacturing, medium-voltage capacity, fire-safe materials and local support for industrial and communications projects.
France Cables & Wires Market Recent Developments
• February 3, 2026 — Nexans completed delivery and formally handed over two 225 kV export cable circuits for the Dieppe–Le Tréport offshore wind farm to RTE.
• February 4, 2026 — Nexans signed a seven-year, €600 million framework agreement with Enedis for medium-voltage cables supporting French distribution-network modernization.
• March 24, 2026 — RTE announced the French subsea cable-laying phase of the 700 MW Celtic Interconnector, including cable supply by Nexans.
• May 19, 2026 — RTE, Nexans, GE Vernova and consortium partners launched RHODÉ, a €16 million R&D initiative for floating high-voltage DC offshore connections.
• June 2, 2026 — Prysmian announced more than €28 million in additional industrial investment plans across French sites at Choose France.
• June 22, 2026 — RTE reported commencement of offshore cable installation for the France–Spain Bay of Biscay interconnector, involving Prysmian and NKT cable-laying vessels.


























































