


Epidermolysis Bullosa Therapeutics Market Size and Overview
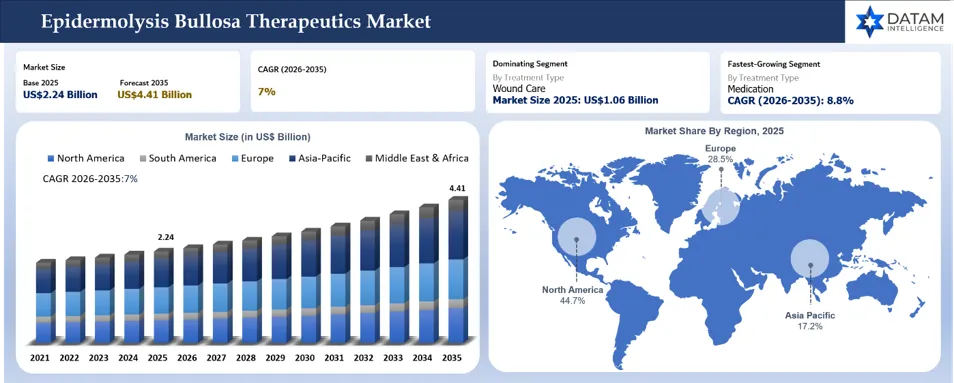
The epidermolysis bullosa therapeutics market reached US$2.24 billion in 2025 and is expected to reach US$4.41 billion by 2035, growing with a CAGR of 7% during the forecast period 2026-2035.
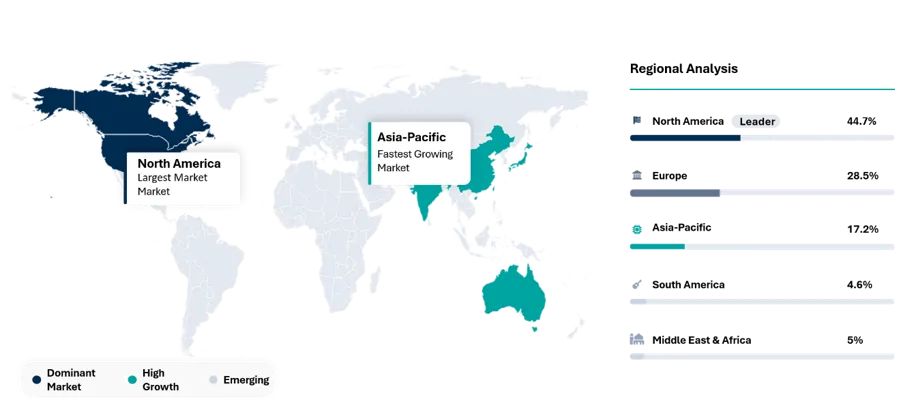
The global epidermolysis bullosa therapeutics market is evolving from a treatment landscape dominated by wound management and supportive care toward disease-modifying gene, cell and regenerative therapies. North America currently represents the largest regional market, accounting for approximately 44.7% of global revenue.
Recent regulatory progress has materially changed the competitive landscape. Krystal Biotech’s VYJUVEK is approved for wounds in patients with dystrophic epidermolysis bullosa carrying COL7A1 mutations, while Abeona Therapeutics’ ZEVASKYN received FDA approval in April 2025 for wounds in adult and pediatric patients with recessive dystrophic epidermolysis bullosa. These approvals are accelerating the transition toward genetically targeted treatments while creating opportunities in home administration, regenerative medicine, precision diagnosis and therapies addressing broader EB subtypes. However, high treatment costs, small eligible patient populations, complex manufacturing and limited specialized treatment infrastructure remain important barriers to wider adoption.
Epidermolysis Bullosa Therapeutics Market Key Takeaways
- The global bladder cancer treatment market was valued at US$2.24 billion in 2025 and is projected to reach US$4.41 billion by 2035, expanding at a CAGR of 7% during 2026-2035.
- The market is shifting from primarily supportive wound care toward disease-modifying gene, cell and regenerative therapies, changing the competitive and treatment landscape.
- Dystrophic epidermolysis bullosa remains the main focus of advanced therapeutic development due to its high clinical burden and expanding availability of targeted treatments.
- Recent approvals of VYJUVEK and ZEVASKYN have validated commercial pathways for gene and cell therapies and strengthened investment interest in rare dermatological disorders.
- North America leads the market, supported by early regulatory approvals, specialized treatment centers, reimbursement infrastructure and higher adoption of advanced therapies.
- Treatment access remains constrained by high therapy costs, complex manufacturing, limited specialist infrastructure and payer authorization requirements, particularly for advanced gene and cell therapies.
- Major growth opportunities lie in home-based administration, treatments for broader EB subtypes, longer-lasting wound closure, simplified dosing and precision genetic diagnosis.
- Competitive differentiation is increasingly based on durability of wound healing, safety, administration convenience, reimbursement access, manufacturing scalability and ability to address underlying genetic defects.
- The long-term market outlook will depend on successful commercialization of advanced therapies, expansion into underserved EB subtypes and improved affordability and treatment accessibility.
Epidermolysis Bullosa Therapeutics Market Scope
| Metrics | Details | |
| 2025 Market Size | US$2.24 Billion | |
| 2035 Projected Market Size | US$4.41 Billion | |
| CAGR (2026-2035) | 7% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Treatment Type | Medication, Wound Care, Others | |
| By Condition Type | Epidermolysis Bullosa Simplex, Dystrophic Epidermolysis Bullosa, Kindler Syndrome, Epidermolysis Bullosa Acquisita | |
| By Distribution Channel | Hospital Pharmacies, Community & Local Pharmacies, Online Pharmacies | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Epidermolysis Bullosa Therapeutics Market White Space & Investment Opportunities
- Next-Generation Gene and Cell Therapies for Broader EB Subtypes: Invest in gene replacement, gene editing, autologous cell therapy and regenerative medicine platforms capable of delivering durable wound closure and addressing the underlying genetic causes of epidermolysis bullosa. Opportunities are particularly attractive for therapies that can treat larger body surface areas, reduce treatment frequency, support repeat administration and expand beyond dystrophic epidermolysis bullosa into junctional and other severe EB subtypes.
- Home-Based and Simplified Treatment Delivery: Develop therapies and delivery models that reduce dependence on specialized treatment centers and enable safe administration in the home or outpatient setting. Simplified topical application, longer dosing intervals, caregiver-compatible administration and decentralized monitoring can reduce travel burden, improve treatment adherence and expand access for pediatric and geographically dispersed EB patients.
- Precision Diagnosis and Patient Stratification: Develop genetic testing, mutation profiling and digital wound-assessment tools that improve diagnosis, classify disease severity and identify patients most likely to benefit from gene, cell or targeted therapies. Better patient stratification can support treatment selection, accelerate clinical-trial recruitment, improve reimbursement evidence and enable more efficient development of therapies for genetically defined and ultra-rare EB populations.
Epidermolysis Bullosa Therapeutics Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Wound Closure and Healing Response
- Durability of Wound Healing
- Reduction in New Wound Formation
- Pain, Itching and Symptom Improvement
- Safety and Tolerability Profile
- Treatment Frequency and Administration Convenience
- Suitability by Epidermolysis Bullosa Subtype and Severity
- Eligibility Based on Genetic Mutation and Molecular Diagnosis
- Ability to Reduce Dressing Changes and Supportive Care Burden
- Home Administration and Caregiver Compatibility
- Long-Term Quality-of-Life Improvement
- Reimbursement Coverage and Overall Treatment Cost
- Availability Through Specialized Treatment Centers
- Manufacturing Reliability and Treatment Accessibility
Epidermolysis Bullosa Therapeutics Market BCG Matrix: Company Evaluation
STAR
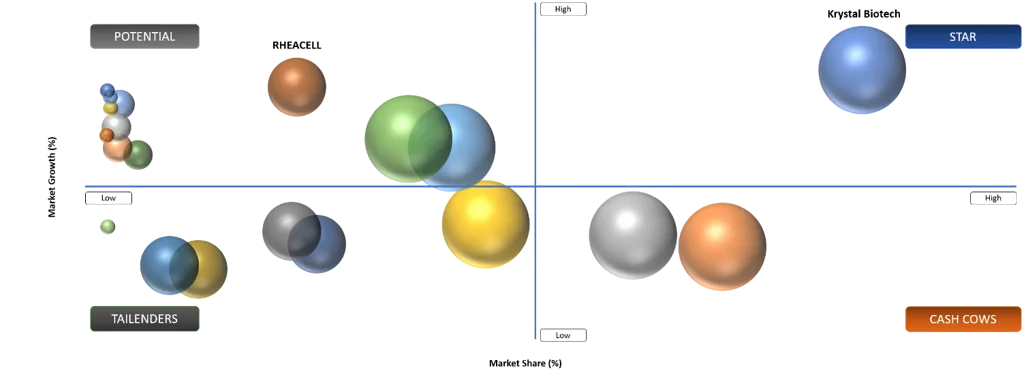
Krystal Biotech, Abeona Therapeutics and Chiesi Farmaceutici are positioned in the Star category based on their commercial-stage epidermolysis bullosa portfolios, regulatory approvals and growing treatment accessibility. Krystal Biotech maintains a prominent position through VYJUVEK, an approved gene therapy for dystrophic epidermolysis bullosa, supported by expanding reimbursement coverage, prescriber adoption and international commercialization. Abeona Therapeutics strengthens the competitive landscape with ZEVASKYN, an FDA-approved autologous cell-based gene therapy for recessive dystrophic epidermolysis bullosa. Chiesi contributes through FILSUVEZ and its established rare-disease commercialization infrastructure. Future leadership will depend on geographic expansion, reimbursement access, manufacturing scalability, treatment durability, home-administration capabilities and real-world evidence demonstrating sustained wound healing and improved patient outcomes.
POTENTIAL
RHEACELL, Xinnate and Aegle Therapeutics are positioned in the Potential category because their differentiated clinical-stage platforms could broaden the future treatment landscape beyond currently approved topical, gene and cell therapies. RHEACELL is advancing its proprietary ABCB5-positive mesenchymal stromal cell platform for recessive dystrophic epidermolysis bullosa, with the program positioned in late-stage clinical development and designed to address systemic inflammation and wound burden. Xinnate is developing TCP-25, an immune-modulating peptide therapy that entered a pivotal Phase 2/3 program and received FDA Fast Track and Rare Pediatric Disease designations in 2026. Aegle Therapeutics is evaluating AGLE-102, an extracellular-vesicle therapy, in Phase 1/2 development. Their progression will depend on clinical efficacy, safety, regulatory execution, financing, manufacturing readiness and commercialization partnerships.
Epidermolysis Bullosa Therapeutics Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Growing Adoption of Gene and Cell Therapies | 18.4% | Disease-modifying treatment adoption | Patients with dystrophic epidermolysis bullosa | Increasing availability of gene and cell therapies is expanding treatment beyond supportive wound care, improving long-term disease management and encouraging investment in advanced EB therapeutic platforms. |
Rising Regulatory Approvals and Pipeline Activity | 15.7% | Product availability and innovation | Patients eligible for novel topical, gene and regenerative therapies | Regulatory approvals and progressing clinical pipelines are broadening therapeutic options, accelerating commercialization and increasing competition among companies developing targeted treatments for epidermolysis bullosa. |
Increasing Diagnosis and Specialized EB Care | 12.9% | Patient identification and treatment access | Pediatric and adult EB patients | Improved genetic testing, specialist referral networks and multidisciplinary EB treatment centers are supporting earlier diagnosis, better patient stratification and increased utilization of advanced therapies and wound-care products. |
Driver: Growing Adoption of Gene and Cell Therapies
The growing adoption of gene and cell therapies is a major driver of the Epidermolysis Bullosa Therapeutics Market, as treatment is gradually shifting from supportive wound management toward disease-modifying approaches. Recent regulatory approvals have demonstrated the commercial potential of therapies designed to correct or replace defective genetic function and promote durable wound closure. These advances are increasing physician confidence, expanding treatment options for severe dystrophic epidermolysis bullosa and encouraging investment in next-generation regenerative platforms. Greater availability of specialized treatment centers, reimbursement pathways and home-based administration models is also improving patient access. As clinical evidence continues to strengthen around wound healing, durability and quality-of-life outcomes, gene and cell therapies are expected to support higher treatment penetration and reshape the competitive landscape of epidermolysis bullosa care.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Cost of Gene and Cell Therapies | 15.8% | Treatment affordability and reimbursement | Patients eligible for advanced gene and cell therapies | High treatment costs, complex reimbursement processes and payer scrutiny can restrict patient access, delay therapy initiation and slow adoption of newly approved disease-modifying treatments. |
Limited Specialized Treatment Infrastructure | 12.6% | Treatment availability | Patients requiring gene therapy, cell therapy and multidisciplinary EB care | Limited availability of qualified treatment centers and EB specialists can create geographic access barriers, increase patient travel burden and constrain wider commercialization of advanced therapies. |
Complex Manufacturing and Supply Chain Requirements | 10.9% | Therapy production and delivery | Autologous cell therapies and gene-based treatments | Specialized manufacturing, cold-chain logistics, patient-specific production and stringent quality-control requirements can increase lead times, constrain scalability and raise commercialization costs for advanced EB therapies. |
Restraint: High Cost of Gene and Cell Therapies
The high cost of advanced gene and cell therapies remains a major restraint for the Epidermolysis Bullosa Therapeutics Market. These treatments require complex manufacturing processes, specialized facilities, stringent quality controls, cold-chain logistics and highly trained clinical teams, resulting in substantial therapy and administration costs. Limited reimbursement coverage and lengthy payer authorization processes can further delay treatment initiation, particularly for patients requiring repeated or highly specialized care. The financial burden is also significant for healthcare systems managing rare-disease populations with lifelong treatment needs. Although gene and cell therapies offer the potential for durable wound healing and disease modification, affordability challenges may restrict adoption beyond major specialty centers. Wider reimbursement, outcome-based payment models and improved manufacturing efficiency will be important for supporting broader patient access.
Epidermolysis Bullosa Treatment Market Segment Analysis
The global epidermolysis bullosa treatment market is segmented based on product type, condition type, distribution channel, and region.
The epidermolysis bullosa simplex in the condition type segment accounted for approximately 43.2% of the global epidermolysis bullosa treatment market share
Epidermolysis bullosa is a very rare condition with approximately 500,000 cases worldwide. Epidermolysis bullosa is a plethora term used for refer various types of conditions classified on the basis of blister morpohology, severity and genetic mutation involved etc. Among these conditions, epidermolysis bullosa simplex (EBS) is the most common form in which the blistering is seen on the uppermost layer of the skin epidermis. In EBS, the genes encoding keratin production are mutated whose role is to provide strutural integrity to the skin. Most of the patients with epidermolysis bullosa have epidermolysis bullosa simplex (EBS).
For instance, on Jaunary 11, 2024, according to an article published in the National Center for Biotechnology Information has stated that epidermolysis bullosa simplex is the most common form accounting for approximately 70% of total cases globally. The other forms such as junctional epidermolysis bullosa accouts for 5% of the cases, dystrophic epidermolysis bullosa accounts for 25% of the cases, and kindler syndrome accounts is a very rare form with only 400
Epidermolysis Bullosa Therapeutics Market Geographical Penetration
U.S. Epidermolysis Bullosa Therapeutics Market Landscape
The United States represents a major market for epidermolysis bullosa therapeutics, supported by early adoption of advanced gene and cell therapies, strong rare-disease research infrastructure and established reimbursement pathways. The treatment landscape has shifted significantly beyond conventional wound management following the FDA approvals of Krystal Biotech’s VYJUVEK for dystrophic epidermolysis bullosa and Abeona Therapeutics’ ZEVASKYN for recessive dystrophic epidermolysis bullosa. In September 2025, the FDA expanded VYJUVEK to patients of all ages and permitted administration in the home setting by healthcare professionals, patients or caregivers. ZEVASKYN received FDA approval in April 2025, further expanding disease-modifying treatment options. Increasing availability of gene therapies, specialized treatment centers and home-based care is expected to reshape U.S. competitive dynamics.
Japan Epidermolysis Bullosa Therapeutics Market Outlook
The Japan epidermolysis bullosa therapeutics market is moving toward advanced regenerative and gene-based treatment options, alongside established wound-care and supportive management approaches. A key development was the July 2025 approval of VYJUVEK Gel in Japan for dystrophic epidermolysis bullosa, representing an important expansion of gene therapy availability in the country. Japan’s Pharmaceuticals and Medical Devices Agency classified the product as an orphan regenerative medical product and specified once-weekly application to affected wounds. The pipeline is also broadening, with a Japanese clinical study evaluating FILSUVEZ (Oleogel-S10) in epidermolysis bullosa patients registered in January 2025 and remaining active in 2026. Increasing regulatory support for regenerative medicine, specialist dermatology infrastructure and entry of multinational rare-disease companies are strengthening Japan’s long-term market opportunity.
Epidermolysis Bullosa Therapeutics Market Competitive Landscape
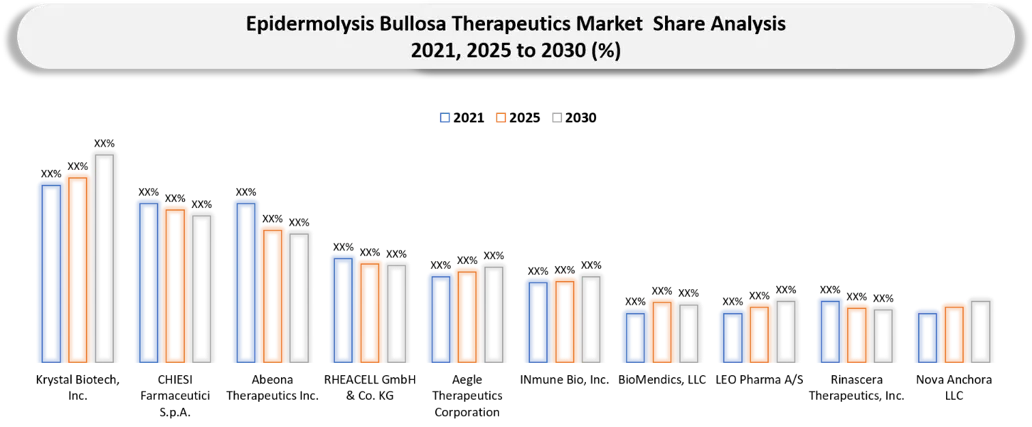
- The Epidermolysis Bullosa therapeutics market is transitioning from predominantly supportive wound management toward targeted gene, cell and regenerative therapies, creating a more innovation-driven competitive environment. Krystal Biotech has established a strong commercial position with VYJUVEK, the first FDA-approved gene therapy for dystrophic epidermolysis bullosa. In September 2025, the FDA expanded its indication to include patients of all ages and permitted home administration by healthcare professionals, patients or caregivers. Krystal reported USD 389.1 million in VYJUVEK revenue in 2025 and USD 116.4 million in Q1 2026, demonstrating increasing commercial adoption.
- Abeona Therapeutics strengthened competition following the April 2025 FDA approval of ZEVASKYN, an autologous cell-based gene therapy for wounds in patients with recessive dystrophic epidermolysis bullosa. Its first commercial patient was treated in December 2025, marking the company's transition into commercialization.
- Chiesi Farmaceutici competes through FILSUVEZ, a topical birch-triterpene therapy approved by the FDA for wounds associated with dystrophic and junctional epidermolysis bullosa in patients aged six months and older.
- Alongside these disease-targeted therapies, companies such as Mölnlycke Health Care, Smith & Nephew, Convatec Group, Essity, Coloplast and URGO Group maintain an important position in supportive wound care. Mölnlycke, for example, markets multiple soft-silicone products including Mepilex, Mepilex Lite, Mepilex Transfer and Mepitel for management of fragile skin and EB-associated wounds.
- Overall, competitive differentiation is increasingly centered on durability of wound closure, treatment frequency, home administration, patient convenience, reimbursement access, manufacturing scalability and the ability to address the underlying genetic cause of EB. The entry of commercially available gene and cell therapies is raising barriers to entry and shifting competition from conventional wound care toward long-term disease-modifying treatment strategies.
Key Companies of Epidermolysis Bullosa Therapeutics Market
- Krystal Biotech, Inc. (United States)
- CHIESI Farmaceutici S.p.A. (Italy)
- Abeona Therapeutics Inc. (United States)
- RHEACELL GmbH & Co. KG (Germany)
- Aegle Therapeutics Corporation (United States)
- INmune Bio, Inc. (United States)
- BioMendics, LLC (United States)
- LEO Pharma A/S (Denmark)
- Rinascera Therapeutics, Inc. (United States)
- Nova Anchora LLC (United States)
- Tay Therapeutics Limited (United Kingdom)
- Convatec Group Plc (United Kingdom)
- Smith & Nephew plc (United Kingdom)
- Mölnlycke Health Care AB (Sweden)
- Essity AB (Sweden)
- Coloplast A/S (Denmark)
- URGO Group (France)
- Medline Inc. (United States)
- Hollister Incorporated (United States)
- Ferris Mfg. Corp. (United States)
Epidermolysis Bullosa Therapeutics Market Recent Developments
- September 2026: Xinnate received FDA Rare Pediatric Disease Designation for TCP-25, its investigational immunomodulatory peptide therapy for epidermolysis bullosa. The company is advancing TCP-25 through the STEP Phase 2/3 clinical development program, strengthening the regulatory pathway for a potential new EB wound treatment.
- August 2026: Abeona Therapeutics reported continued commercial expansion of ZEVASKYN (prademagene zamikeracel) for recessive dystrophic epidermolysis bullosa. Five patients were treated during Q2 2026 and three additional patients had been treated in Q3 through August 13, bringing total treatments since launch to 12. ZEVASKYN generated USD 11.4 million in Q2 2026 net revenue, up 31% quarter-over-quarter.
- August 2026: The Centers for Medicare & Medicaid Services granted New Technology Add-On Payment status to ZEVASKYN, effective October 1, 2026 under the FY2027 Hospital Inpatient Prospective Payment System. The supplemental reimbursement mechanism is intended to facilitate hospital adoption and Medicare patient access to the autologous cell-based gene therapy.
- August 2026: Krystal Biotech reported USD 119.2 million in Q2 2026 global net product revenue from VYJUVEK, representing 24% year-over-year growth, while cumulative revenue since launch reached approximately USD 965.9 million. The company had secured more than 730 U.S. reimbursement approvals and expanded its prescriber network to more than 640 physicians.
- July 2026: Abeona Therapeutics activated Cincinnati Children’s as the seventh Qualified Treatment Center for ZEVASKYN in the United States, expanding treatment availability for adult and pediatric patients with recessive dystrophic epidermolysis bullosa.
What DATAM Uniquely Provides
- In-depth segmentation of the Epidermolysis Bullosa Therapeutics Market by treatment type, condition type, distribution channel and region, with additional assessment of epidermolysis bullosa simplex, dystrophic epidermolysis bullosa, junctional epidermolysis bullosa, Kindler syndrome and other clinically relevant disease categories.
- Competitive analysis of leading epidermolysis bullosa treatment companies covering marketed therapies, gene and cell therapy platforms, wound-care portfolios, mechanism of action, clinical efficacy, dosing and administration approach, safety profile, regulatory status, pipeline maturity, commercialization strategy and geographic expansion.
- Comprehensive assessment of diagnosed, treatable and therapy-eligible epidermolysis bullosa patient populations, including analysis by disease subtype, severity, age group, genetic mutation profile, wound burden, treatment setting and eligibility for advanced gene, cell and regenerative therapies.
- Detailed evaluation of the clinical and regulatory pipeline, including late-stage gene therapies, autologous cell therapies, regenerative medicine, topical treatments, wound-healing products and emerging molecular approaches, with analysis of trial progress, regulatory designations, approval pathways and potential commercialization timelines.
- Strategic assessment of market access, reimbursement and unmet needs, covering therapy affordability, treatment-center availability, home-based administration, payer coverage, manufacturing scalability, wound-care requirements and opportunities for therapies that improve durable wound closure, reduce treatment burden and address the underlying genetic cause of epidermolysis bullosa.



























































