


Global Data Center Transformer Market Overview
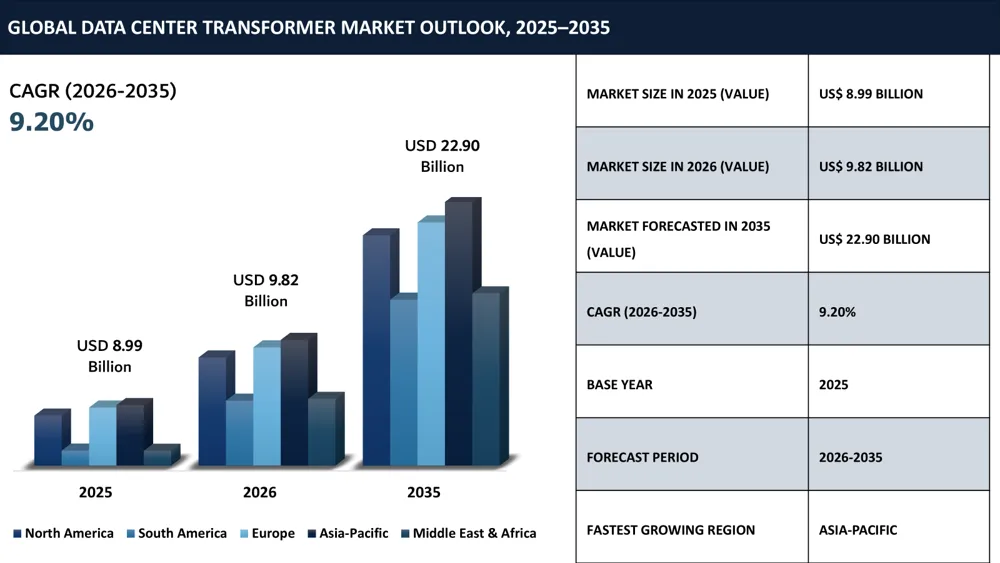
The data center transformer market has been experiencing considerable growth owing to the increasing need for efficient and dependable power supply infrastructure fueled by the growing popularity of hyperscale data centers, cloud computing, AI and HPC. As per the International Energy Agency (IEA), the global consumption of data center electricity in 2025 has risen to 485 TWh and is estimated to more than double by 2030, rising to 950 TWh, emphasizing the increasing electricity consumption of digital infrastructure. The rising use of generative AI applications, AI accelerators, high-density servers and computing systems is leading to the rising need for power transformers, distribution transformers, dry-type transformers and isolation transformers to ensure efficient voltage transformation and uninterrupted power supply. Furthermore, growing investment in hyperscale facilities, cloud infrastructure, grid modernization, renewable energy sources and on-site power generation is forcing data center companies to deploy transformers with high capacity and efficiency. The growing stress on the electricity grids, long lead times required in the purchase of transformers and the need for improved reliability of power are forcing manufacturers to increase their capacity to produce transformers with better technology and improve their supply chains to cater to the increasing demands for electricity.
Global Data Center Transformer Market: Strategic Insights
- AI-Driven Electricity Demand: According to the International Energy Agency (IEA), electricity usage in global data centers has risen from about 485 TWh in 2025 to an expected figure of 950 TWh in 2030. Growing AI infrastructure investments are boosting the need for high-capacity transformers and efficient power distribution systems.
- Transformer Manufacturing Expansion: In September 2026, Hitachi Energy made an investment of USD 528 million for its new transformer manufacturing plant in Mississippi, USA, to increase production capacity and cater to the increasing demands of data centers and other industries.
- Solid-State Transformer Technology Development: In August 2026, Siemens and Maschinenfabrik Reinhausen signed an agreement to develop solid-state transformers that have an output of 800 V DC for AI data centers, marking the potential use of new generation power distribution technology.
- High-Voltage Transformer Procurement and Grid Infrastructure Expansion: In September 2026, Hyosung Heavy Industries secured approximately 287 million USD in contracts for the supply of transformers from two technology companies in the US for AI data center projects, including transformers for 765 kV and 345 kV. This signifies an increasing importance of high-voltage transformer procurement for connecting data center grids.
WHY CHOOSE DATAM?
- Accelerated Customer Identification – Target 2.0× Qualified Sales Leads: Help transformer manufacturers double their pipeline of qualified customers through data center operators identification, prospect profiling, EPC contractors mapping and segmentation of customers. DataM helps companies to identify valuable prospects, qualify leads and acquire customers.
- Faster Market Entry & Business Expansion – Target 25% Reduction in Market Entry Time: Help transformer manufacturers shorten their market entry time by conducting geographic analysis, data center investments tracking, regulations research and distributors identification. DataM helps with faster market entry, partnership formation and business growth.
- Stronger Competitive Positioning – Target 25% Improvement in Sales Win Rate: Help transformer manufacturers enhance their sales win rates by 1.25× with the aid of Competitive Benchmarking, Pricing Intelligence, Transformer Technology Analysis and Portfolio Evaluation. DataM identifies competitive gaps, helps differentiate and gain more contracts with customers.
- Higher Customer Revenue & Account Expansion – Target 1.25× Revenue per Key Account: Facilitate a 25% increase in revenue from strategic accounts using Customer Wallet-Share Analysis, Opportunities for Replacement of Transformers, Cross-Selling Opportunities and Data Center Capacity Expansion Assessments. DataM maximizes customer value and builds long-term business relationships.
- Improved Pricing & Profitability – Target 2 Percentage-Point Gross Margin Improvement: Assist transformer manufacturers in boosting their gross margins by leveraging competitive pricing intelligence, raw material cost evaluation, assessments of consumer willingness to pay and benchmarking of transformer specifications. DataM enables better price setting, more effective bargaining and increased profitability.
- Strategic Partnerships & Channel Expansion – Target 1.5× Customer Acquisition: Help transformer manufacturers increase transformer-generated client acquisition rates by 50% using distributor mapping, EPC contractor identification, utility partnerships and ecosystem analysis. DataM enables manufacturers to strengthen their distribution network and extend their reach.
- Improved Demand Forecasting & Revenue Protection – Target 25% Reduction in Forecast Errors: Assist transformer manufacturers in minimizing their demand forecasting inaccuracies through analysis of data center construction pipeline, transformer purchasing intelligence, assessment of regional demand and scenario planning. DataM helps optimize inventory, decrease procurement snags and enhance order execution.
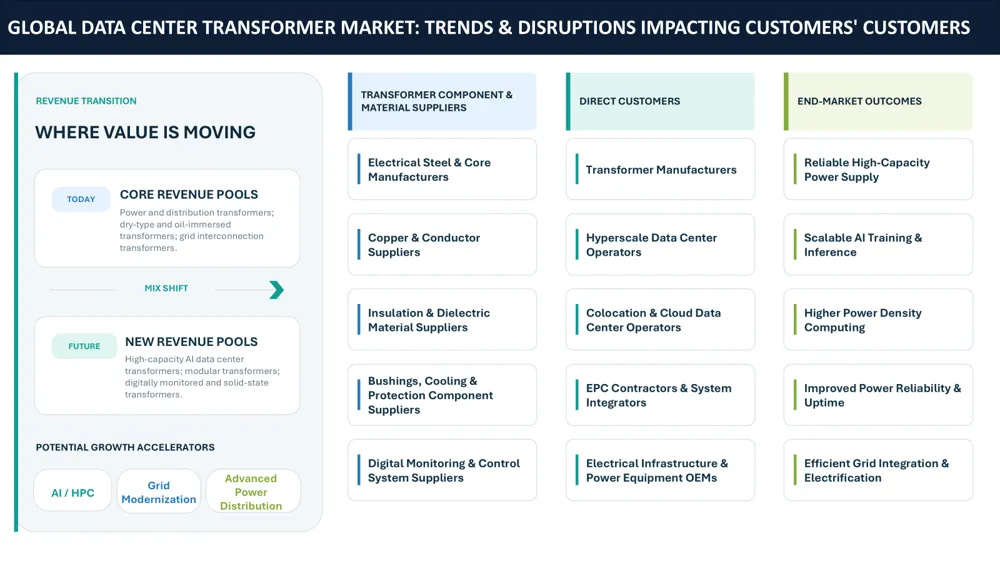
Global Data Center Transformer Market: Trends & Disruption Impacting Client Customers
GLOBAL DATA CENTER TRANSFORMER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
 | Supplies dry-type and liquid-filled transformers for data center substations, power distribution units and critical electrical infrastructure. | Reliable power distribution, improved energy efficiency, reduced electrical losses and enhanced operational safety. |
 | Provides high-voltage and medium-voltage power transformers for grid connections, substations and power distribution networks serving hyperscale and colocation data centers. | Improved power reliability, scalable infrastructure, efficient voltage conversion and reduced risk of power interruptions. |
 | Supplies power and distribution transformers for utility grid connections, substations and electrical networks supporting large-scale data center facilities. | Efficient voltage conversion, reliable electricity supply, reduced transmission losses and improved grid integration. |
 | Provides substation transformers and medium-voltage transformer solutions for data centers requiring reliable electrical supply and critical power infrastructure. | Enhanced electrical protection, improved operational reliability, surge protection and efficient power distribution. |
 | Offers medium-voltage and dry-type transformer solutions for hyperscale, cloud and colocation data centers. | Improved energy efficiency, dependable power distribution, reduced electrical losses and enhanced infrastructure reliability. |
Global Data Center Transformer Market Ecosystem
The global data center transformer market ecosystem comprises transformer manufacturers, electrical equipment suppliers, power distribution solution providers, engineering, procurement and construction (EPC) contractors, data center developers and operators, utility companies and power infrastructure integrators. Together, these stakeholders support transformer design, manufacturing, grid interconnection, voltage conversion, power distribution, installation and maintenance across hyperscale, colocation, enterprise, edge and AI data center facilities.
| TRANSFORMER MANUFACTURERS | ELECTRICAL EQUIPMENT & POWER INFRASTRUCTURE SUPPLIERS | DATA CENTER DEVELOPERS & OPERATORS |
| ABB Ltd. | Schneider Electric SE | Amazon Web Services (AWS) |
| Hitachi Energy Ltd. | Eaton Corporation plc | Microsoft Corporation |
| Siemens Energy AG | Mitsubishi Electric Corporation | Google (Alphabet Inc.) |
| GE Vernova Inc. | Toshiba Energy Systems & Solutions Corporation | Equinix, Inc. |
| Hyosung Heavy Industries Corporation | Fuji Electric Co., Ltd. | Digital Realty Trust, Inc. |
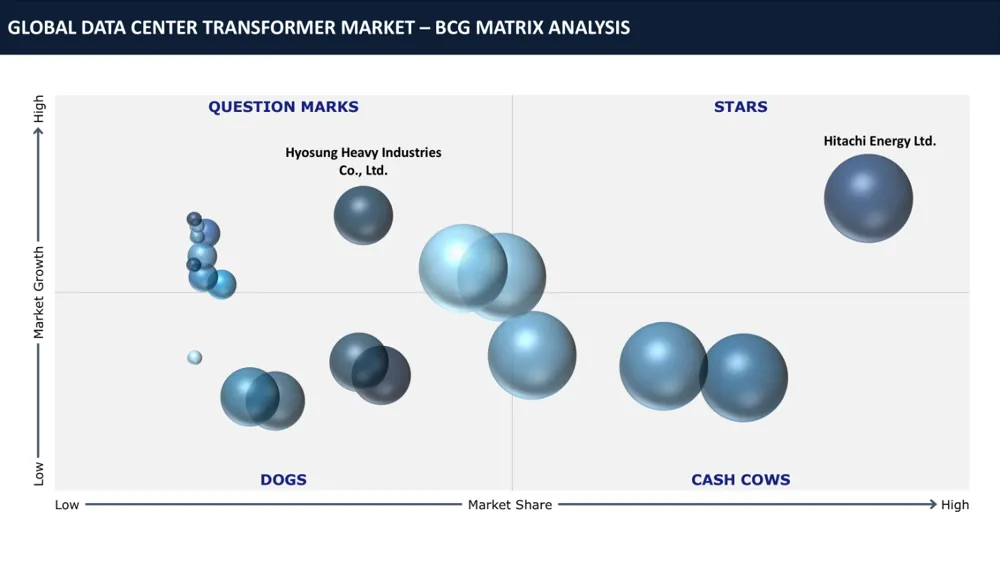
Global Data Center Transformer Market: BCG Matrix Analysis
- Stars: High-capacity power transformers, medium-voltage distribution transformers and dry-type transformers exhibit strong growth potential
- Cash Cows: Conventional distribution transformers, standard oil-immersed transformers and established dry-type transformer solutions generate stable demand.
- Question Marks: Solid-state transformers, high-efficiency transformers and advanced digital monitoring-enabled transformers represent emerging opportunities.
- Dogs: Obsolete, low-efficiency transformer designs and outdated equipment with limited compatibility with modern data center power requirements face declining competitiveness and replacement demand.
Global Data Center Transformer Market: Key Market Players
- ABB Ltd. (Switzerland)
- Schneider Electric SE (France)
- Siemens Energy AG (Germany)
- Hitachi Energy Ltd. (Switzerland)
- GE Vernova Inc. (United States)
- Eaton Corporation plc (Ireland)
- Mitsubishi Electric Corporation (Japan)
- Toshiba Energy Systems & Solutions Corporation (Japan)
- Hyosung Heavy Industries Corporation (South Korea)
- HD Hyundai Electric Co., Ltd. (South Korea)
- Fuji Electric Co., Ltd. (Japan)
- CG Power and Industrial Solutions Limited (India)
- Hammond Power Solutions Inc. (Canada)
- Virginia Transformer Corporation (United States)
- SGB-SMIT Group (Germany)
- WEG S.A. (Brazil)
- Delta Star, Inc. (United States)
- MGM Transformer Company (United States)
- Ormazabal (Spain)
- Legrand SA (France)
Global Data Center Transformer Market: Recent Developments
- WEG S.A. – October 2026: Highlighted their existing data center project experience, comprising 23 transformers with 70 MVA ratings and eight transformers with 250 MVA ratings used for U.S.-based projects, as well as 124 transformers used for a Brazilian data center project.
- Hyosung Heavy Industries Corporation – September 2026: Secured orders worth around $287 million for AI data centers in the U.S. for the supply of transformers from two American technology firms. These orders comprise 765 kV and 345 kV transformers and would increase their position in the American data centers power infrastructure market.
- Hitachi Energy Ltd. – September 2026: USD 528 million worth of investments have been made to build a new manufacturing plant in Mississippi, United States, to meet the rising demand for transformers from data centers and semiconductor manufacturers.
- Hammond Power Solutions Inc. – September 2026: A new manufacturing plant in Fort Worth, Texas, has been established to meet the rising demand for transformers from data centers and electrification programs with an initial annual manufacturing capacity of approximately CAD 250 million.
- Hitachi Energy Ltd. – August 2026: Committed USD 300 million for increased manufacturing capabilities for transformers and components in Hefei, China, due to the rise in demand from AI data centers, industrial electrification and electricity transmission grids.
Global Data Center Transformer Market: Delivered Customization
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
| Hyperscale Data Center Operator |
|
|
| Colocation Data Center Provider |
|
|
| Transformer Manufacturer |
|
|
| Electrical Equipment Supplier |
|
|
| EPC Contractor / System Integrator |
|
|
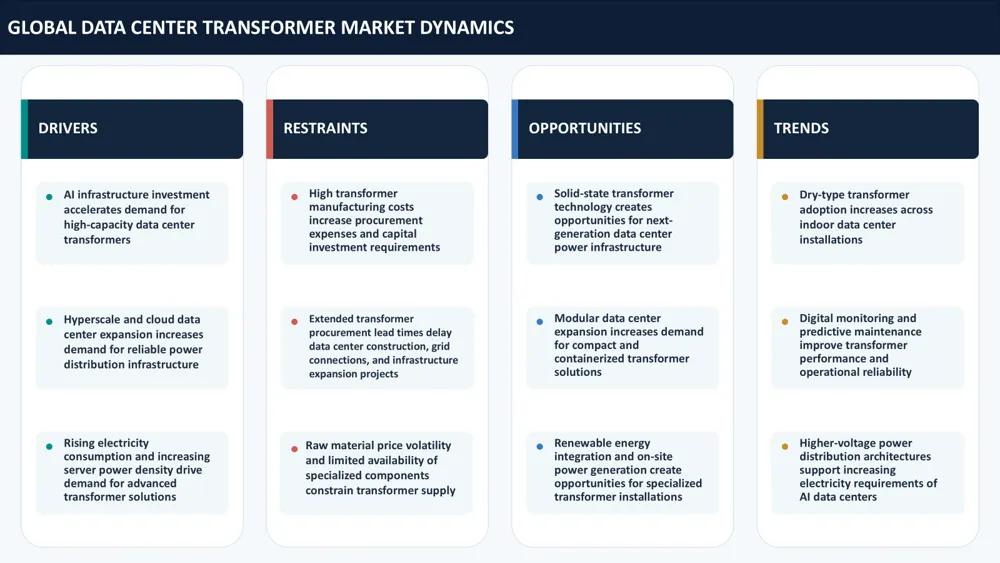
Global Data Center Transformer Market: Market Dynamics
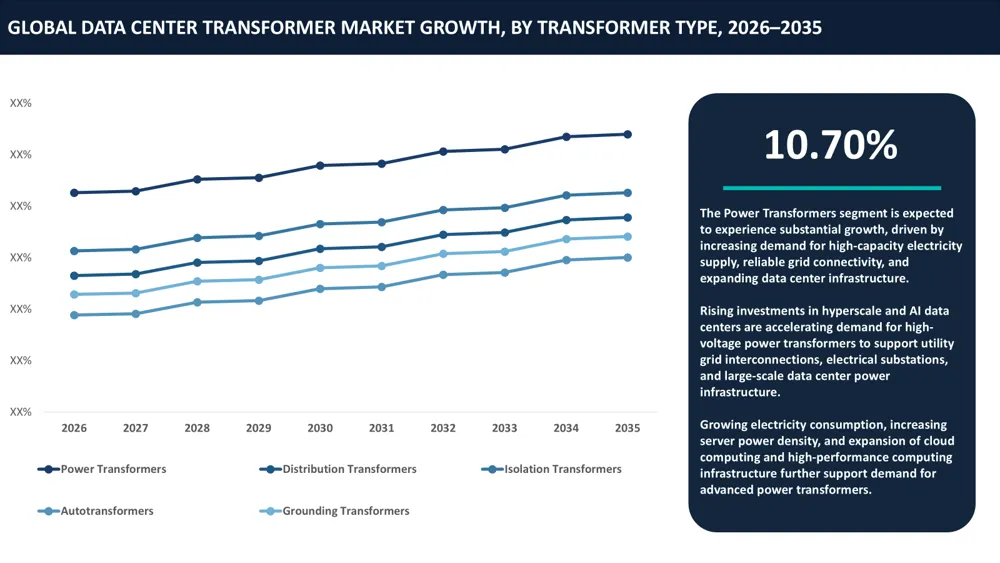
Global Data Center Transformer Market: Market Segment Analysis
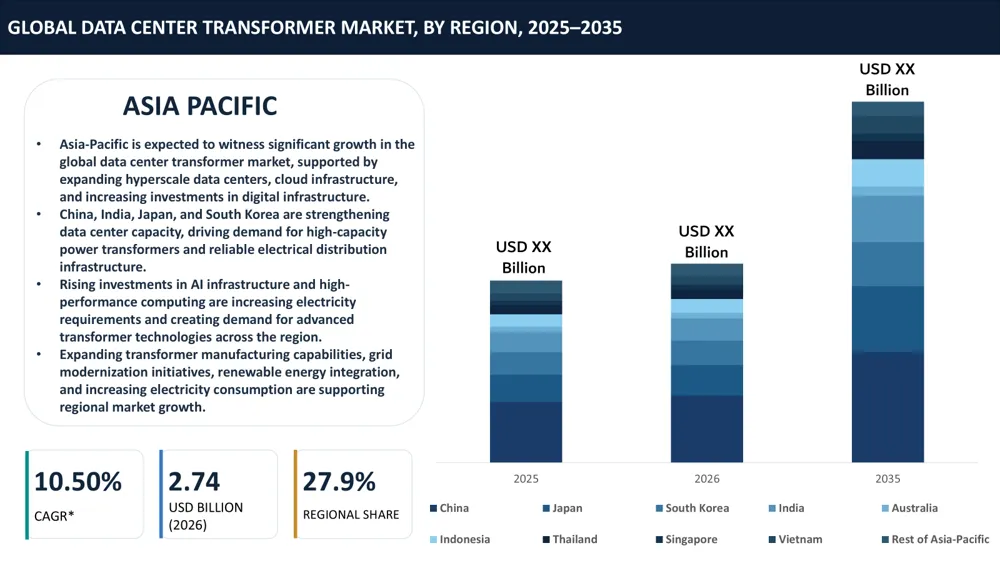
Global Data Center Transformer Market: Region Wise Analysis
Global Data Center Transformer Market: Market Scope
| Metrics | Details | |
| Market Size in 2025 (Value) | USD 791.70 Billion | |
| Market Size in 2026 (Value) | USD 869.25 Billion | |
| Market Forecasted in 2035 (Value) | USD 2,099.00 Billion | |
| CAGR (2026-2035) | 10.29% | |
| Years Considered | 2024-2035 | |
| Base Year | 2025 | |
| Forecast Period | 2026-2035 | |
| By Transformer Type | Power Transformers Distribution Transformers Isolation Transformers Autotransformers Grounding Transformers | |
| By Insulation Type | Oil-Immersed Transformers Dry-Type Transformers Cast Resin Transformers Vacuum Pressure Impregnated (VPI) Transformers Vacuum Pressure Encapsulated (VPE) Transformers | |
| By Voltage Level | Low Voltage (Below 1 kV) Medium Voltage (1 kV–36 kV) High Voltage (Above 36 kV–110 kV) Extra-High Voltage (Above 110 kV) | |
| By Power Rating | Below 1 MVA 1–5 MVA Above 5–10 MVA Above 10–25 MVA Above 25–50 MVA Above 50 MVA | |
| By Cooling Method | Oil Natural Air Natural (ONAN) Oil Natural Air Forced (ONAF) Oil Forced Air Forced (OFAF) Air Natural (AN) Air Forced (AF) | |
| By Phase | Single-Phase Transformers Three-Phase Transformers | |
| By Installation Environment | Indoor Transformers Outdoor Transformers | |
| By Mounting and Deployment Configuration | Skid-Mounted Transformers Containerized / Modular Transformers Pad-Mounted Transformers Pole-Mounted Transformers | |
| By Application | Utility Grid Interconnection Medium-Voltage Power Distribution Low-Voltage Power Distribution UPS and Critical Power Infrastructure Backup Power and Generator Integration Renewable Energy and On-Site Power Integration | |
| By Data Center Type | Hyperscale Data Centers Colocation Data Centers Enterprise Data Centers Edge Data Centers AI and High-Performance Computing (HPC) Data Centers | |
| By Data Center Tier | Tier I Tier II Tier III Tier IV | |
| By End-User | Cloud Service Providers Colocation Service Providers Enterprise Data Center Operators Telecommunications Data Center Operators Government and Public Sector Data Center Operators Managed Data Center Service Providers | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Turkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Market Share, Market Growth | |
Global Data Center Transformer Market: Target Audience
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| TRANSFORMER MANUFACTURERS | Power transformer, distribution transformer and dry-type transformer manufacturers | Assess market demand, competitor positioning, product opportunities, manufacturing capacity and regional expansion potential. |
| ELECTRICAL EQUIPMENT MANUFACTURERS | Switchgear, UPS, power distribution and electrical infrastructure suppliers | Identify transformer integration opportunities, product development requirements, strategic partnerships and cross-selling potential. |
| DATA CENTER OPERATORS | Hyperscale, colocation, enterprise and edge data center operators | Evaluate transformer specifications, power capacity requirements, supplier availability, procurement strategies and infrastructure expansion opportunities. |
| CLOUD SERVICE PROVIDERS | Cloud computing companies and AI infrastructure operators | Assess high-capacity transformer requirements, electricity demand growth, power reliability and infrastructure investment opportunities. |
| EPC CONTRACTORS & SYSTEM INTEGRATORS | Electrical engineering, procurement, construction and power system integration companies | Identify upcoming data center projects, transformer procurement opportunities, supplier capabilities and project execution requirements. |
| UTILITY & POWER COMPANIES | Electricity utilities, transmission operators and power generation companies | Evaluate grid interconnection requirements, transformer demand, substation investments and electricity infrastructure expansion. |
| RENEWABLE ENERGY DEVELOPERS | Solar, wind, battery storage and on-site power generation companies | Understand transformer requirements for renewable energy integration, grid connectivity, energy storage and dedicated data center power supply. |
| INVESTORS & FINANCIAL INSTITUTIONS | Private equity firms, venture capital investors, infrastructure funds and financial advisors | Evaluate market growth opportunities, competitive positioning, manufacturing investments, acquisition opportunities and regional investment potential. |
| GOVERNMENT & POLICYMAKERS | Energy departments, infrastructure agencies and industrial development authorities | Assess transformer supply-chain requirements, domestic manufacturing opportunities, grid infrastructure needs and investment policies. |
| TRANSFORMER MANUFACTURERS | Power transformer, distribution transformer and dry-type transformer manufacturers | Assess market demand, competitor positioning, product opportunities, manufacturing capacity and regional expansion potential. |
Why Does This Report Matter In 2026?
The global transformers for data centers industry is taking on strategic importance in 2026 owing to the fast growth of data centers specializing in artificial intelligence computing capabilities, hyperscale computing centers and cloud computing platforms that drive up the need for power-intensive and dependable electrical equipment. Increasing power densities of servers in data center racks, rising electricity consumption rates and limitations on grid access make it necessary to pay more attention to transformer capacities, purchasing time and power distribution systems. Data centers' developers and operators now need to consider the voltage range, capacity, insulation systems, cooling design, energy efficiency and redundancy of transformers. These issues have made transformer selection and availability of transformers crucial considerations in the design and planning of data centers.
Meanwhile, transformer manufacturers and infrastructure developers are encountering difficulties with regard to specialized electrical steel, copper shortages, manufacturing capabilities and longer lead times related to procurement. Meanwhile, the increasing adoption of artificial intelligence infrastructure presents new possibilities for dry-type transformers, modular transformer installation systems, digital monitoring systems and innovative solid-state transformers. There is an increasing need for comprehensive knowledge about the transformer manufacturing capabilities, product specifications, positioning of suppliers, regional demand, interconnections with utilities and data center building pipelines. Knowledge about these aspects is crucial for the recognition of growth opportunities, procurement activities, competitive capabilities analysis and investment considerations in the global data center transformers market.
Global Data Center Transformer Market: Analyst View / Opinion
The global data center transformer industry is getting influenced by two inter-related infrastructure needs: traditional power infrastructure for hyperscale, colocation and enterprise data centers and power infrastructure that needs to have more capacity to accommodate the demands of artificial intelligence and high-performance computing (HPC) centers. Both types of applications cannot be judged on the basis of a single set of transformer requirements and specifications. Traditional data centers need transformers that can offer reliability of power supply, voltage regulation, efficiency and longevity. However, AI data centers require more power, compatibility with advanced cooling systems, scalability of the power infrastructure and power density solutions. Therefore, transformer manufacturers have to ensure that their products match the changing voltages, capacity levels, insulation technologies and installation designs in data centers.
There are three areas that present competition challenges. First, there is the issue of increased production costs due to inadequate manufacturing capacity for transformers, long procurement lead times and variable prices for copper and electrical steel. Manufacturers have to increase their production capacity, acquire necessary raw materials and coordinate well with utilities companies, EPCs and data center builders. The second challenge is the issue of increased electricity demand and grid connection difficulties, which can make project timelines and transformer design specifications uncertain. Proper planning of electricity infrastructures, effective load forecasting and flexible transformer designs should be done to solve these challenges. The third challenge is the rapid technological advancements, such as the use of solid-state transformers, digital metering devices and sophisticated power distribution technologies, which are modifying future requirements for products. Manufacturers have to strike a balance between investments in new technologies and traditional transformers, which have to be reliable, cost-effective and in accordance with electrical standards.


























































