


Data Center Motors and Drives Market: Overview
The demand for data center motors and drives is rising owing to the fast-growing market for hyperscale data centers and other technologies such as cloud computing, AI, high-performance computing (HPC) and digital infrastructure. AI workloads and high-density server racks are leading to higher demands for cooling and the use of energy-efficient motors, VFDs and motor drive systems in ventilation fans, cooling pumps, chillers, compressors and other thermal management systems. Moreover, the emerging focus on energy efficiency, operational reliability and sustainability of data centers is leading to the use of premium efficiency AC induction motors, PMSMs, EC motors and smart drives in data centers. The increased use of liquid cooling, immersion cooling and hybrid cooling is also leading to the need for specialty pumps and variable speed control in the industry. In addition, the investments made by cloud service providers, hyperscalers, data center developers and governments in digital infrastructure and energy-efficient facilities will aid in developing and deploying advanced motor and drive technologies.
Data Center Motors and Drives Market: Strategic Insights
- AI-Driven Cooling Demand Expansion: As the workload of AI increases along with the densification of computing infrastructure, there will be increased demand for cooling capacity in both hyperscale and enterprise data centers. As per IEA estimates, the operators of the global hyperscale data centers will make capital investments exceeding USD 700 billion by 2026, most of which will go towards constructing data centers. Increased power density per server racks is fueling the need for high-efficiency motors, VFDs, fans, pumps and compressors.
- Liquid-Cooling Adoption and Specialized Motor Demand: The growing use of direct-to-chip liquid cooling, immersion cooling and other innovative heat management technologies opens up great opportunities for specialized pumps and variable-speed drives. The latest data center infrastructure outlook by S&P Global shows that 21% of enterprise data center decision-makers interviewed intend to introduce liquid cooling within one year, while 25% of them plan this technology implementation in two-four years. It follows that this trend only increases the requirement for efficient fluid circulation and accurate motor-speed control.
- Energy Efficiency and Operational Reliability Priorities: The increase in cost of electricity generation, the need for cooling and concerns related to the efficiency of the power system are pushing data centers towards adopting motors that have a higher efficiency. The Uptime Institute Global Data Center Survey 2026 outlines high operating costs, power availability and disruptions in supply chains as major issues in the data centers sector. Such priorities are reinforcing the case for efficiency in motor performance, maintenance and coolers optimization.
- Regional Infrastructure Expansion and Investment Opportunities: The increased data center capacity in numerous locations presents opportunities for manufacturers of motors and drives for cooling, ventilation and pumping systems. Data from India's Ministry of Electronics and Information Technology highlights that the installed capacity for data centers has increased from 375 MW in 2020 to 1,575 MW in August 2026. Emerging state investment locations such as Andhra Pradesh, Madhya Pradesh, Chhattisgarh and West Bengal will further increase opportunities for the development of infrastructure. All of these developments imply an increase in the tendency to use energy efficient motors, VFDs and motor-drive systems in these applications.
WHY CHOOSE DATAM?
- Accelerated Customer Identification – Target 2.0× Qualified Sales Leads: Help the manufacturers of data center motors and drives in increasing their number of qualified customers through the identification of data center operators, OEM mapping, profiling of buyers and customer segmentation. DataM allows for businesses to increase their high value prospects among hyperscale, collocation, enterprise and edge data center operations, lead qualification and rapid customer acquisition.
- Faster Market Entry & Business Expansion – Target 25% Reduction in Market Entry Time: Help data center motors and drive manufacturers reduce their market entry time through regional opportunity assessment, regulatory intelligence, investment tracking in data centers and distributor identification. DataM helps in accelerating market penetration, developing partnerships and expansion into existing and emerging data center markets.
- Stronger Competitive Positioning – Target 25% Improvement in Sales Win Rate: Aid in improving the sales of manufacturers through competitor benchmarking, pricing intelligence, product portfolio analysis and technology comparisons. DataM enables the identification of competitive weaknesses, differentiation of AC motors, PMSMs, EC motors, VFDs and integrated motor-drive systems and enhance customer acquisition prospects.
- Higher Customer Revenue & Account Expansion – Target 1.25× Revenue per Key Account: Promote revenue increase from strategic accounts by means of customer wallet-share analysis, cross-selling opportunities and product gaps analysis. DataM assists manufacturers in determining what is still required from their customers in terms of cooling fans, pumps, chillers, compressors and liquid cooling systems to create value and maintain commercial relationships.
- Improved Pricing & Profitability – Target 2 Percentage-Point Gross Margin Improvement: Drive the motor and drives manufacturers to gain from pricing intelligence, benchmarking of products, analysis of customer value and application-oriented demand. DataM will help make sound pricing decisions, better negotiating position and higher profits in data center cooling applications.
- Strategic Partnerships & Channel Expansion – Target 1.5× Customer Acquisition: Facilitate the growth of channel-driven customer acquisition by helping manufacturers map out their distributors, identify OEMs of cooling systems, profile system integrators and analyze their ecosystems. DataM will facilitate a greater partnership with data center operators, HVAC firms, cooling systems manufacturers and engineering contractors for increased commercial access.
- Improved Demand Forecasting & Revenue Protection – Target 25% Reduction in Forecast Errors: Enable manufacturing companies to enhance their forecasting capabilities by way of data center capacity, regional infrastructure investment, cooling technology trends and logistics. DataM helps manufacturers in planning for production, inventory, procurement and order fulfillment.
Data Center Motors and Drives Market: Trends & Disruption Impacting Client Customers
Global Data Center Motors and Drives Market: Commercial Use Cases Across Industries
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
 | High-efficiency motors and variable-frequency drives for data center cooling pumps, fans and HVAC systems. | Improved energy efficiency, optimized motor operation and reliable cooling performance. |
 | Intelligent motor and drive technologies for data center ventilation, air handling and cooling infrastructure. | Precise speed control, improved operational efficiency and reduced energy consumption. |
 | Variable-frequency drives for cooling pumps, ventilation fans and compressor applications in data centers. | Optimized cooling capacity, reduced power consumption and flexible system control. |
 | Motors and thermal management solutions for server cooling fans and data center equipment. | Efficient heat dissipation, compact motor designs and reliable cooling operation. |
 | Electronically commutated fans and motor technologies for server cooling, CRAH units and data center ventilation. | Energy-efficient airflow, intelligent speed regulation and reduced cooling power requirements. |
Data Center Motors and Drives Market Ecosystem
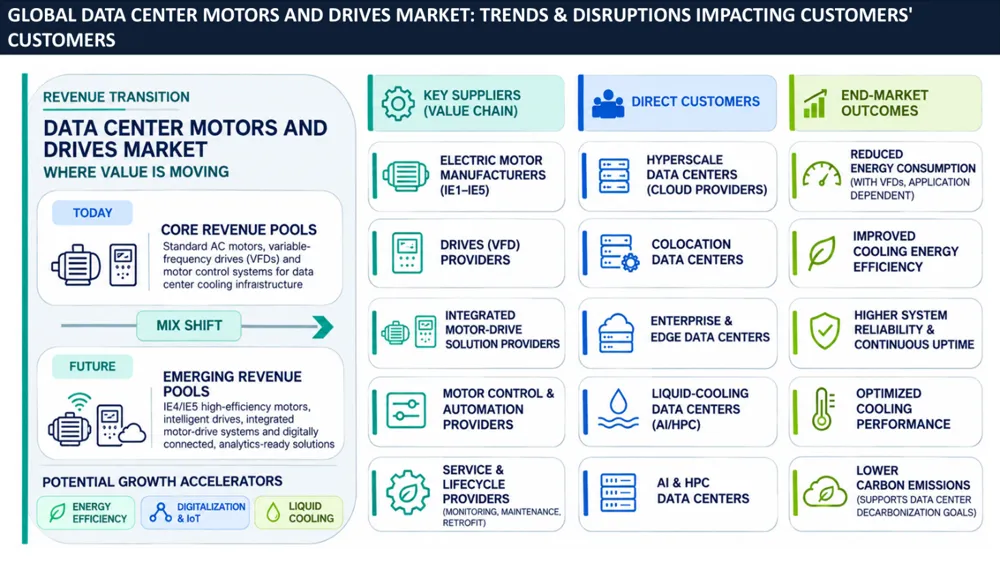
The global data center motors and drives market ecosystem consists of electric motor manufacturers, providers of motor drives and variable-frequency drives (VFDs), manufacturers of cooling equipment, specialists in ventilation, automation and control service providers, component suppliers, system integrators and operators of data centers. The aforementioned parties work together in the development, manufacturing, integration, installation and maintenance of motor and drive technologies in cooling, ventilation, pumping and thermal management in data centers.
| ELECTRIC MOTOR MANUFACTURERS | MOTOR DRIVE AND VFD MANUFACTURERS | DATA CENTER COOLING EQUIPMENT OEMs |
| ABB Ltd. | Danfoss A/S | Vertiv Holdings Co. |
| Siemens AG | Schneider Electric SE | Johnson Controls International plc |
| Nidec Corporation | Yaskawa Electric Corporation | Trane Technologies plc |
| WEG S.A. | Mitsubishi Electric Corporation | Carrier Global Corporation |
| Regal Rexnord Corporation | Fuji Electric Co., Ltd. | STULZ GmbH |
Data Center Motors and Drives Market: BCG Matrix Analysis
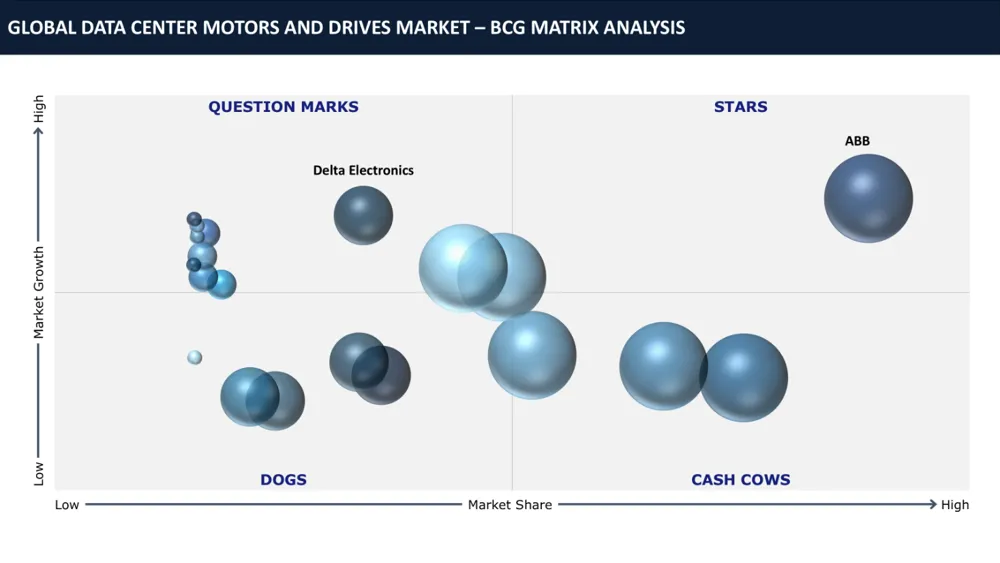
- Stars: Variable frequency drives (VFDs), electronically commutated (EC) motors and integrated motor-drive systems have great growth potential due to high demands for energy-efficient cooling, intelligent motor controls and AI-powered data centers.
- Cash Cows: AC induction motors and conventional low-voltage motor-drive systems generate reliable demand within traditional data center cooling applications such as ventilation fans, chilled water pumps and HVAC systems.
- Question Marks: Permanent magnet synchronous motors (PMSMs), synchronous reluctance motors (SynRMs) and specialized pump motors for liquid-cooling systems represent potential opportunities with data centers implementing new cooling technologies and more efficient equipment.
- Dogs: Low-efficiency, fixed-speed motor systems are becoming less competitive as data center operators place more importance on energy efficiency, variable-speed motors, digital monitoring and infrastructure modernization.
Data Center Motors and Drives Market: Key Market Players
- ABB Ltd. (Switzerland)
- Siemens AG (Germany)
- Danfoss A/S (Denmark)
- Nidec Corporation (Japan)
- WEG S.A. (Brazil)
- Schneider Electric SE (France)
- Regal Rexnord Corporation (United States)
- Mitsubishi Electric Corporation (Japan)
- Rockwell Automation, Inc. (United States)
- Yaskawa Electric Corporation (Japan)
- Innomotics GmbH (Germany)
- Toshiba International Corporation (United States)
- Fuji Electric Co., Ltd. (Japan)
- Delta Electronics, Inc. (Taiwan)
- Wolong Electric Group Co., Ltd. (China)
- ebm-papst SE (Germany)
- ZIEHL-ABEGG SE (Germany)
- Eaton Corporation plc (Ireland)
- TECO Electric & Machinery Co., Ltd. (Taiwan)
- Hitachi Industrial Equipment Systems Co., Ltd. (Japan)
Data Center Motors and Drives Market: Recent Developments
- October 21, 2026: ABB concluded a technology licensing deal with Electric Torque Machines (ETM), an affiliate of Graco, to create transverse flux motors that will be used in the cooling tower of data center heat rejection systems. The high-torque, low-speed direct-drive technology aims to make cooling systems more straightforward and reliable.
- October 8, 2026: WEG provided 40 electric motors at 30 kW apiece and 40 CFW500 variable frequency drives for 10 pre-assembled cooling modules designed by Enfrio in Italy. The case shows how motor drive solutions can be implemented in high-power cooling systems providing data center infrastructure.
- September 23, 2026: Schneider Electric has announced its Motivair WCDU coolant distribution unit featuring pumps and heat exchangers, which enable implementation of hybrid air and liquid cooling designs in high-density AI data centers. The unit delivers 3.5 MW of cooling and represents an option for the use of integrated motor drives.
- September 22, 2026: ABB released Infinitus direct current portfolio for artificial intelligence data center, which involves variable-speed drives and motors operating on direct current for cooling optimization. The portfolio is suitable for new generation of direct current power architectures that aim to increase energy efficiency, flexibility and scalability.
- September 8, 2026: Nidec has confirmed its participation in the Data Center World Asia 2026 conference during which it will be presenting its liquid cooling solutions intended for new generation AI data centers. The company's offered products include in-rack cool distribution units with a cooling capacity of 300 KW and in-row CDUs with a power capacity of 2 MW indicating its positive market trends within cooling and pumping technologies.
Data Center Motors and Drives Market: Delivered Customization
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
| Electric Motor Manufacturer |
|
|
| Motor Drive and VFD Manufacturer |
|
|
| Data Center Cooling Equipment OEM |
|
|
| Data Center Operator / Hyperscaler |
|
|
| HVAC and Cooling System Integrator |
|
|
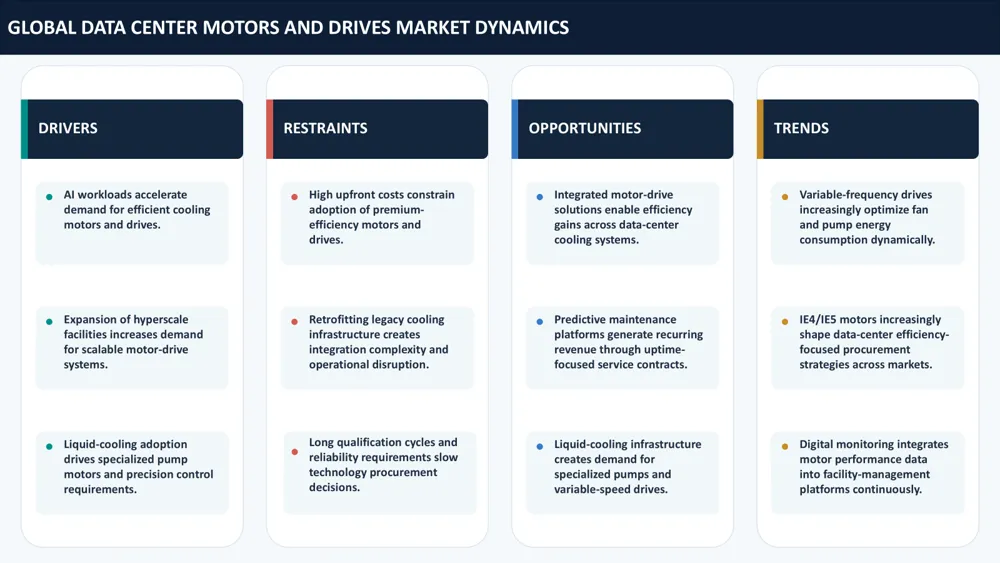
Data Center Motors and Drives Market: Market Dynamics
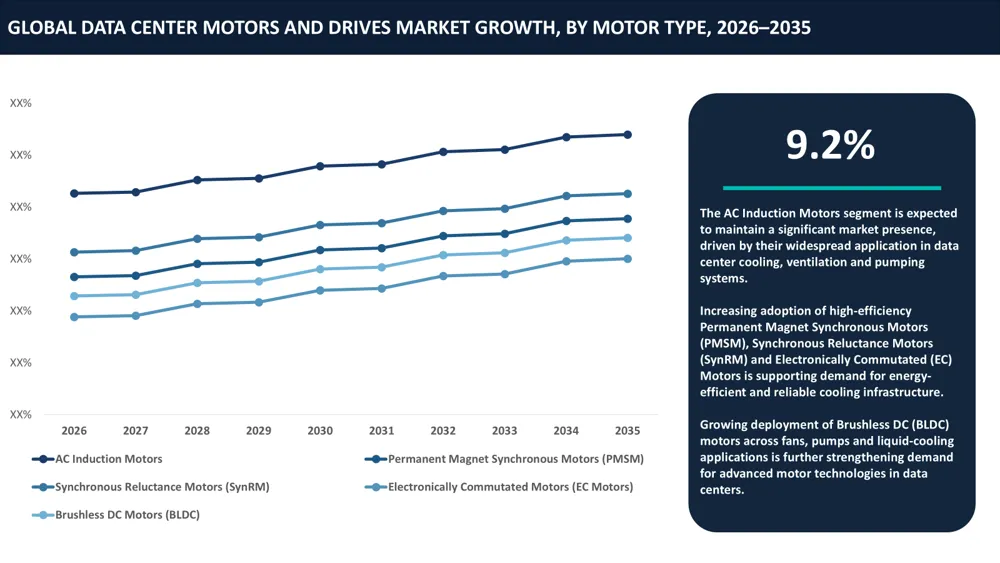
Data Center Motors And Drives Market: Market Segment Analysis
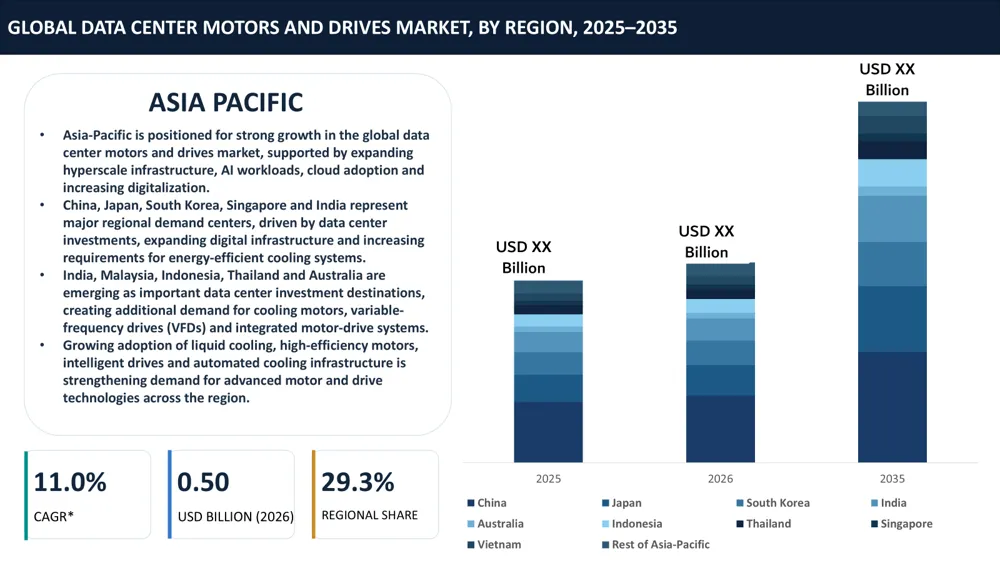
Data Center Motors and Drives Market: Region Wise Analysis
Data Center Motors and Drives Market: Market Scope
| Metrics | Details | |
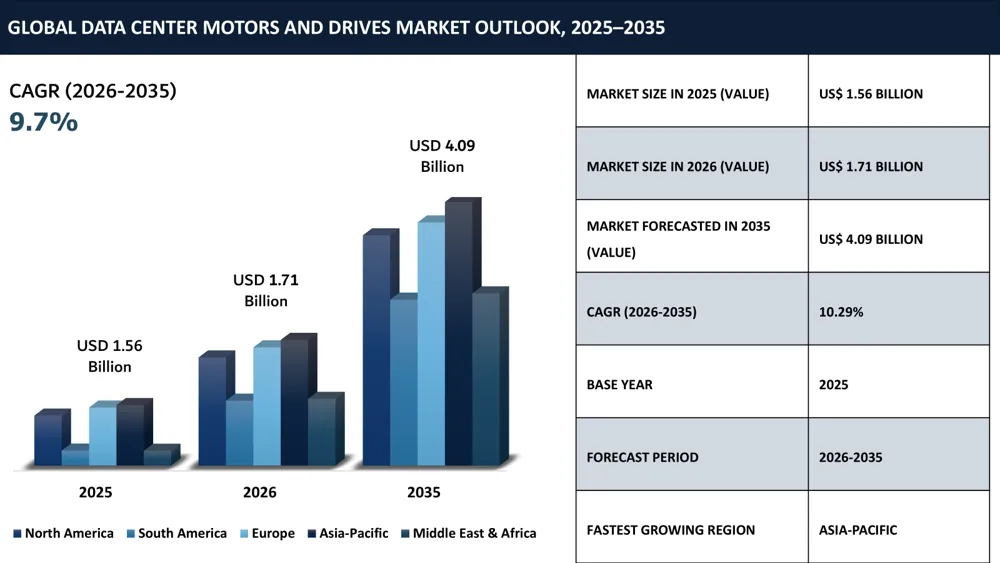
| Market Size in 2025 (Value) | USD 1.56 Billion | |
| Market Size in 2026 (Value) | USD 1.71 Billion | |
| Market Forecasted in 2035 (Value) | USD 4.09 Billion | |
| CAGR (2026-2035) | 9.7% | |
| Years Considered | 2024-2035 | |
| Base Year | 2025 | |
| Forecast Period | 2026-2035 | |
| By Motor Type | AC Induction Motors Permanent Magnet Synchronous Motors (PMSM) Synchronous Reluctance Motors (SynRM) Electronically Commutated Motors (EC Motors) Brushless DC Motors (BLDC) | |
| By Drive Type | Variable Frequency Drives (VFDs) Soft Starters Integrated Motor-Drive Systems Other Electronic Motor Drives | |
| By Power Rating | Micro and Fractional Power (Below 0.75 kW) Low Power (0.75–7.5 kW) Medium Power (Above 7.5–75 kW) High Power (Above 75–375 kW) Very High Power (Above 375 kW) | |
| By Voltage | Low Voltage (Up to 1 kV) Medium Voltage (Above 1 kV to 11 kV) | |
| By Motor Efficiency Class | IE2 – High Efficiency IE3 – Premium Efficiency IE4 – Super Premium Efficiency IE5 – Ultra Premium Efficiency | |
| By Cooling Application | Fan and Ventilation Systems CRAC and CRAH Units Chiller and Compressor Systems Cooling Tower and Dry Cooler Systems Chilled Water and Condenser Water Pumping Systems Liquid Cooling and Coolant Distribution Systems | |
| By Cooling Technology | Air-Based Cooling Liquid-Based Cooling Hybrid Cooling | |
| By Control and Integration | Fixed-Speed Motor Systems Variable-Speed Motor Systems Standalone Motor and Drive Systems Integrated Motor-Drive Systems Digitally Connected Motor-Drive Systems | |
| By Data Center Type | Hyperscale Data Centers Colocation Data Centers Enterprise Data Centers Edge Data Centers Government and Institutional Data Centers | |
| By Data Center Tier | Tier I Tier II Tier III Tier IV | |
| By Sales Channel | Original Equipment Manufacturers (OEMs) Aftermarket and Replacement | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Turkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Market Share, Market Growth | |
Data Center Motors and Drives Market: Target Audience
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| ELECTRIC MOTOR MANUFACTURERS | AC motor, PMSM, SynRM, EC and BLDC motor manufacturers | Evaluate motor technology demand, efficiency requirements, product positioning and growth opportunities across data center cooling applications. |
MOTOR DRIVE AND VFD MANUFACTURERS | Variable-frequency drive, soft starter and integrated motor-drive solution providers | Assess demand for variable-speed control, energy-efficient drives, product innovation and competitive positioning. |
DATA CENTER COOLING EQUIPMENT OEMs | Manufacturers of fans, pumps, chillers, CRAH/CRAC units and cooling towers | Identify motor and drive requirements, cooling technology trends and equipment integration opportunities. |
| DATA CENTER OPERATORS | Hyperscalers, colocation providers and enterprise data center operators | Evaluate motor and drive technologies, energy efficiency, operational reliability and infrastructure investment requirements. |
CLOUD AND AI INFRASTRUCTURE PROVIDERS | Cloud service providers, AI infrastructure developers and hyperscale operators | Understand cooling-related motor demand, liquid-cooling adoption and infrastructure efficiency requirements. |
HVAC AND COOLING SYSTEM INTEGRATORS | Mechanical contractors, HVAC integrators and thermal management solution providers | Assess application-level demand, system integration opportunities and emerging cooling infrastructure requirements. |
INDUSTRIAL AUTOMATION AND CONTROL PROVIDERS | Automation, motor control, sensor and industrial control system manufacturers | Track demand for intelligent motor control, digital monitoring, variable-speed operation and predictive maintenance solutions. |
ELECTRICAL AND COMPONENT SUPPLIERS | Motor component, power electronics, semiconductor and control component manufacturers | Identify component demand, technology developments, supply-chain opportunities and customer requirements. |
DISTRIBUTORS AND SERVICE PROVIDERS | Motor and drive distributors, maintenance providers and aftermarket service companies | Evaluate replacement demand, service opportunities, distribution strategies and lifecycle maintenance requirements. |
ENGINEERING CONSULTANTS AND PROCUREMENT SPECIALISTS | MEP consultants, electrical engineering firms, EPC contractors and procurement managers | Understand technical specifications, vendor selection criteria, project requirements and procurement trends. |
Why Does This Report Matter In 2026?
The data center motors and drives industry around the world is entering a crucial period of growth and evolution in 2026 amid heightened investments by hyperscale tech players, cloud service providers, colocation facilities and data center developers in AI infrastructure, supercomputing and digital services. The fast proliferation of AI workload demands, higher server rack power density levels and the need to have constant access to computing services are driving up the need for effective cooling solutions, ventilation and thermal management systems. This trend is increasing the significance of high-performance motors and drives as essential parts to ensure the energy efficiency, cooling capabilities and reliability of digital infrastructure operations in North America, Europe, the Asia-Pacific region and other emerging digital infrastructure markets.
At the same time, there is a great pressure on the data centers and the manufactures of the equipment to minimize the energy consumption, to increase the effectiveness of the cooling process and improve the reliability of the infrastructure due to the increased cost of energy and the increased complexity of thermal management. Improvements in high-efficiency AC motors, PMSM, EC motors, variable-frequency drives, smart motor controllers and integrated motor and drive system are significantly changing competitive position among different suppliers. In addition to this, the increasing use of the direct-to-chip liquid cooling, immersion cooling, automatic ventilation and predictive maintenance technologies is creating the need for motor and drives that will be able to operate in these conditions. There is a great demand from buyers, investors and technology companies for more information about motor efficiencies, product lines, cooling applications, production capacity, competitive position, regional investments, replacement opportunities and technology to assess long-term market competitiveness, recognize commercially viable options and improve supply chain strategy.
Data Center Motors and Drives Market: Analyst View / Opinion
There are two important aspects that are responsible for shaping the global data center motors and drives market. One crucial development in that area is closely connected with advancing of AI-based computing architecture. Another important idea influencing this market is forming of increasing requirements for energy-efficient cooling equipment. With the growing number of computing servers’ rack power levels, the importance of cooling systems along with energy-efficient motors and drive systems are increasing as well. It can be expected that the development of huge data collection facilities, cloud computing systems, among other things including colocation capacity will stimulate the demand. However, motor and drive specifications vary according to application within the cooling process. Fan, pump, chiller, compressor and liquid cooling applications all have different specifications.
There are three competitive concerns worth considering. Firstly, growing power density of data centers and increased cooling system complexity have created a demand for new solutions related to motor-driven cooling system. It is necessary to offer a range of motors with drives, specifically suitable for air cooling and especially for liquid cooling systems. Secondly, high initial expenses, electricity prices and complicated process of implementation may hinder the implementation of energy efficient motors and drives in particular. The variety of products and optimal life cycle cost as well as proper retrofits strategy may help to overcome such concerns. Thirdly, fast technological progress related to liquid cooling, intelligent controls of motors and predictive maintenance has changed demands on products and competitive position of manufacturers. Firms which bolster their digital monitoring skills, enhance their motor drives and offer services for the replacement of components will be more adept at exploiting these opportunities.


























































