


GLOBAL DATA CENTER CABLES AND WIRES MARKET OVERVIEW
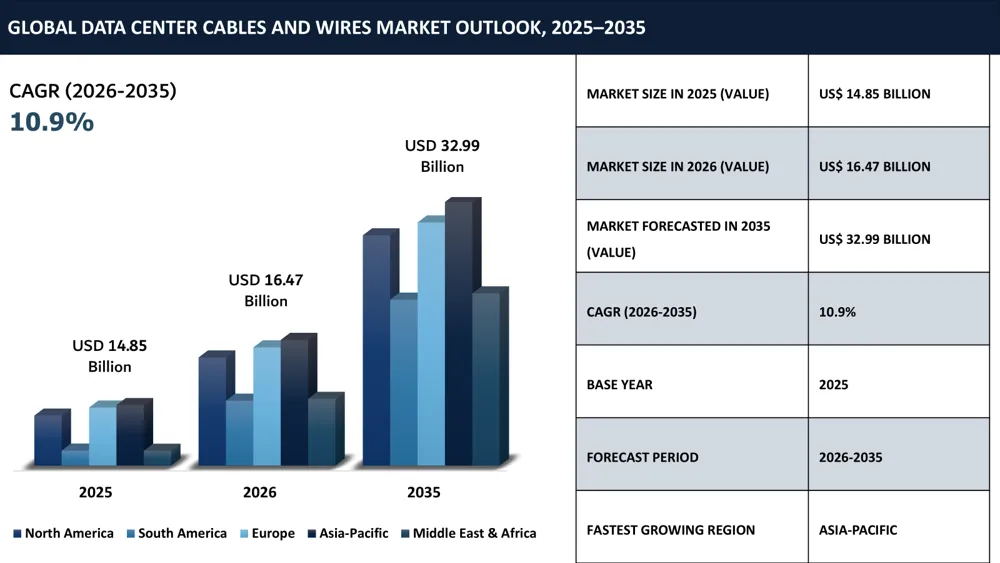
The growth of the global data center cables and wires market is due to the growing need for dependable power supply systems and quick data transmission in hyperscale, colocation, enterprise and edge data centers. The rapid advancement of AI technologies, cloud computing, high-performance computing and extensive data processing contributes to the increase in demand for cabling infrastructure in order to achieve higher bandwidth, increased power capacity and stable connectivity. The expansion of AI technology is expected to enhance the market growth due to the increased demand for high-density fiber-optic links, speed-oriented copper circuits, power distribution systems and specialized cables like DAC cables, AEC cables and AOC cables. Increase in investments in digital infrastructure, computing capabilities of the country and cloud service ecosystems in the form of investments made by governments, technology companies and data center operators are equally contributing toward this market. The shift towards faster networking solutions with 800G and 1.6T connectivity is further encouraging the upgrading of existing cabling systems. Manufacturers have been putting emphasis on optical connectivity, denser cables, better handling of power and scalable cables to cope with the changing demands of future data centers.
DATA CENTER CABLES AND WIRES MARKET STRATEGIC INSIGHTS
- AI-Driven Demand and Power Infrastructure Expansion: The increasing use of artificial intelligence and investment in hyperscale data centers are leading to a greater demand for power cables, fiber-optic cables and other advanced cabling options. According to IEA (International Energy Agency), electricity consumption of worldwide data centers is anticipated to rise from around 485 TWh in 2025 to about 950 TWh in year 2030. This growth will result in increased demand for efficient electricity distribution and over-the-top cabling options thus allowing the use of demanding AI applications.
- Hyperscaler Capital Expenditure and Data Center Buildout: Investments by large technology firms are driving faster growth in data centers and opening up new avenues for the cable industry. In the IEA's forecast till 2026, the capital expenditure spending of large technology firms was more than USD 400 billion in 2025 and expected to grow by 75% in 2026. Such investments are helping power cables, fiber-optics, copper interconnects and cable assemblies.
- Transition Toward High-Speed Optical Connectivity: As more bandwidth is required in the domains of artificial intelligence and hyperscale data centers, the need for advanced optical connectivity solutions continues to grow. In July 2026, HFCL launched the OptiQ AI brand name which is used to identify the company's optical connectivity product line comprising of fiber optic cables, assemblies, patch cords and trunks for data centers. This indicates that there is rising interest in developing fiber optics infrastructure for future data center networking.
- Manufacturing Capacity Expansion and Strategic Supply Agreements: The cable manufacturing companies are increasing production capacity to meet the growing demand for data centers. In July 2026, Prysmian signed a long-term optical cable supply contract with Molex valued at EUR 5.5 billion over a period of ten years. Furthermore, the company intends to invest EUR 1.25 billion to more than double its fiber capacity in the United States market, which will help solidify its position in the data center cabling supply chain.
WHY CHOOSE DATAM?
- Accelerated Customer Identification – Target 2.0× Qualified Sales Leads: Assist data center cable and wire companies in doubling their qualified sales lead pipeline by identifying hyperscale operators, mapping colocation providers, customer profiling and segmentation of customers. DataM allows companies to identify valuable prospects, improve customer targeting and accelerate customer acquisition.
- Faster Market Entry & Business Expansion – Target 25% Reduction in Market Entry Time: Assist cable manufacturers in reducing market entry time with regional demand assessments, tracking investments in data centers, regulation analysis and distribution identification. DataM facilitates rapid market entry, strategic alliances and geographic expansion.
- Stronger Competitive Positioning – Target 25% Improvement in Sales Win Rate: Assist cable companies in enhancing sales win rate through benchmarking against competition, pricing intelligence, product portfolio evaluation and assessment of supplier capabilities. DataM helps fill the competitive gaps, differentiate products and gain more supply contracts.
- Higher Customer Revenue & Account Expansion – Target 1.25× Revenue per Key Account: Drive revenue through key accounts via hyperscale customer analysis, cross-sell, product gap analysis and demand mapping in power cables, fiber optics, copper interconnects and cable assemblies. DataM helps maximize customer value and strengthen long-term commercial relationships.
- Improved Pricing & Profitability – Target 2 Percentage-Point Gross Margin Improvement: Assist cable manufacturers to boost their gross margin gains by means of competitive pricing, cost analysis for copper, aluminum, optical fiber and polymers, price benchmarking across regions and product positioning. DataM helps make more informed pricing, better negotiation and increase in profitability.
- Strategic Partnerships & Channel Expansion – Target 1.5× Customer Acquisition: Assist cable manufacturers in growing customer acquisition through distributors, identification of electrical contractors, analysis of EPC partners and investigation of data center ecosystem. DataM will help build better distribution channels, make strategic alliances and widen the commercial presence.
- Improved Demand Forecasting & Revenue Protection – Target 25% Reduction in Forecast Errors: Assist cable manufacturers in improving demand forecasting with the help of data center construction pipeline analysis, hyperscalers investments tracking, demand analysis for products and region-level market intelligence. DataM will assist in planning of production, inventory management, procurement decisions and order fulfillment.
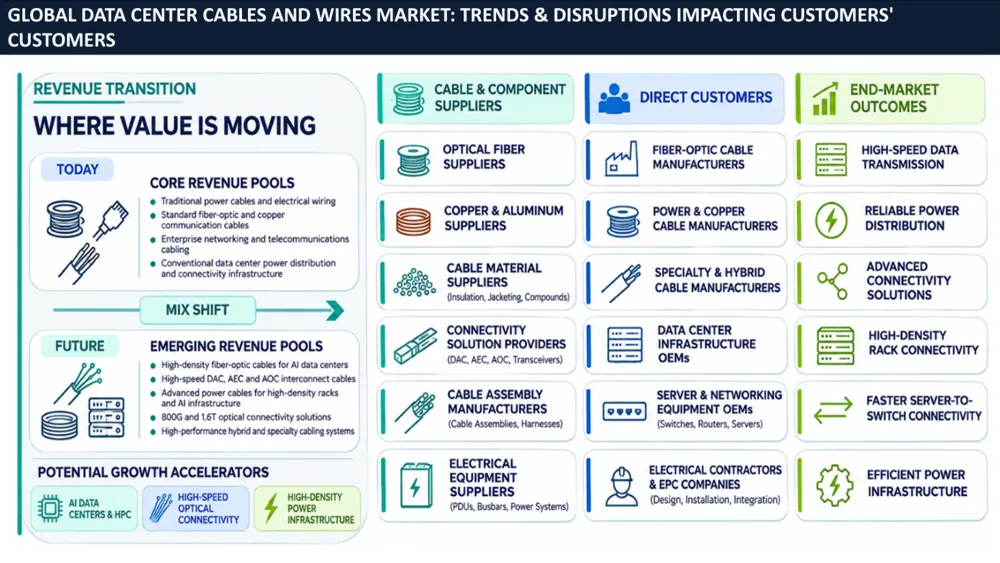
DATA CENTER CABLES AND WIRES MARKET: TRENDS & DISRUPTION IMPACTING CLIENT CUSTOMERS
DATA CENTER CABLES AND WIRES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
 | Supplies high-density fiber-optic cabling solutions for hyperscale data centers, AI infrastructure and high-speed optical connectivity between data center networking equipment. | Increases bandwidth capacity, reduces signal loss, supports faster data transmission and enables scalable data center connectivity. |
 | Provides fiber-optic and power cable solutions for data center communication networks, electrical distribution systems and large-scale infrastructure expansion. | Ensures reliable power distribution, supports high-speed connectivity, improves infrastructure reliability and enables scalable data center development. |
 | Develops high-speed copper and optical interconnect cable assemblies for server-to-server, server-to-switch, storage and AI computing connections. | Enables high-speed data transmission, supports compact connectivity, reduces signal interference and improves system integration. |
 | Supplies structured copper and fiber-optic cabling systems for data center networking, rack connectivity and communication infrastructure. | Provides reliable network connectivity, simplifies cable management, supports infrastructure flexibility and improves network performance. |
 | Supplies low-voltage power cables and fiber-optic connectivity solutions for data center electrical infrastructure and communication networks. | Supports reliable electrical distribution, enhances connectivity, improves installation flexibility and strengthens infrastructure resilience. |
DATA CENTER CABLES AND WIRES MARKET ECOSYSTEM
The global data center cables and wires market ecosystem includes the raw material providers, optical fiber manufacturers, power and communication cable manufacturers, specialty cables suppliers, cable assemblies manufacturers, connectivity solutions providers, distributors, electrical infrastructure suppliers and data center owners. In unison, they provide the means to manufacture, supply, deploy and install power distribution and high-speed communication cabling for the infrastructure of hyperscale, colocation, enterprise, edge and AI data centers.
| RAW MATERIAL SUPPLIERS | CABLE, WIRE AND CONNECTIVITY MANUFACTURERS | DATA CENTER OPERATORS AND END USERS |
| Aurubis AG | Corning Incorporated | Amazon Web Services (AWS) |
| Wieland Group | Prysmian Group | Microsoft Corporation |
| Norsk Hydro ASA | Nexans | Google LLC |
| Novelis Inc. | Amphenol Corporation | Meta Platforms, Inc. |
| MediaTek Inc. | Tower Semiconductor Ltd. | Infineon Technologies AG |
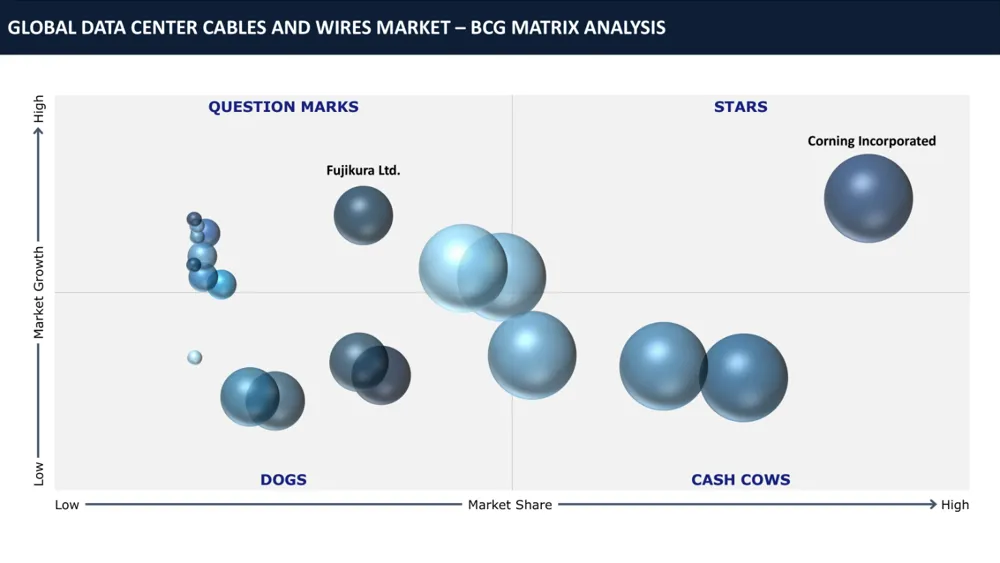
DATA CENTER CABLES AND WIRES MARKET: BCG MATRIX ANALYSIS
- Stars: High-density fiber optic cables, high-speed optical interconnects and highly advanced cable assemblies for AI data centers have a high growth potential due to the rise in bandwidth needs and AI infrastructure.
- Cash Cows: Conventional power cables, standard copper cables and established fiber optic cabling solutions earn steady income due to the ongoing data center building and development processes.
- Question Marks: Active Electrical Cables (AEC), Active Optical Cows (AOC) and highly advanced hybrid cable solutions provide new business opportunities amid growing AI infrastructure and high-speed networking applications.
- Dogs: The traditional low-speed cabling solutions and cable technologies experience falling demand due to data centers upgrading their bandwidth capabilities and power capacities.
DATA CENTER CABLES AND WIRES MARKET: KEY MARKET PLAYERS
- Corning Incorporated (United States)
- Prysmian Group (Italy)
- Nexans S.A. (France)
- Sumitomo Electric Industries, Ltd. (Japan)
- Fujikura Ltd. (Japan)
- Furukawa Electric Co., Ltd. (Japan)
- Amphenol Corporation (United States)
- Belden Inc. (United States)
- Panduit Corp. (United States)
- Molex, LLC (United States)
- TE Connectivity Ltd. (Switzerland)
- LS Cable & System Ltd. (South Korea)
- Southwire Company, LLC (United States)
- Yangtze Optical Fibre and Cable (YOFC) (China)
- Hengtong Group (China)
- Sterlite Technologies Limited (STL) (India)
- AFL Global (United States)
- Superior Essex Inc. (United States)
- Rosenberger Group (Germany)
- Hexatronic Group AB (Sweden)
DATA CENTER CABLES AND WIRES MARKET: RECENT DEVELOPMENTS
- September 29, 2026: LS Cable & System unveiled new busbars and connectors for AI data center server racks at Data Centre World Asia 2026. These developments enhance the power infrastructure offering by extending beyond the grid-to-rack distribution of power to provide an internal rack solution to meet the higher power needs of AI computers.
- September 24, 2026: Sterlite Technologies Limited (STL) extended its Neuralis data center product family with pre-terminated trunk assemblies for the hyperscale data centers. Trunks offer high-density optical connectivity with pre-installed and pre-tested connectors that reduce the need for field splicing and help to speed up the process of data center installation.
- September 21, 2026: Molex launched VersaBeam Mini, a highly compact optical connector employing expanded beam technology meant for the next-generation AI and hyperscale data centers. This technology offers three times higher density of connections and allows to fit up to 3,456 fibers per 1RU panel, providing for growing need for high-density optical connectivity.
- September 17, 2026: Corning offered new products for the AI data center networks at ECOC 2026 event, which included Contour Form Micro Cable, multicore fibers and optical connectors. Multicore fiber is a novel Corning's solution that offers four cores within one fiber strand and expands the capacity of the network.
- September 10, 2026: Sterlite Technologies Limited (STL) launched fiber trunk assemblies for AI data center connectivity that conform to NFPA 262 standards in its 48F-576F intermittently bonded ribbon assembly portfolio. These developments reinforce STL’s fire safety compliant and high-density optical cable solutions for data center installations above and below floor levels.
DATA CENTER CABLES AND WIRES MARKET: DELIVERED CUSTOMIZATION
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
| Data Center Cable Manufacturer |
|
|
| Hyperscale Cloud and Data Center Operator |
|
|
| Optical Fiber and Connectivity Provider |
|
|
| Raw Material and Cable Component Supplier |
|
|
| Electrical Infrastructure OEM / EPC Provider |
|
|
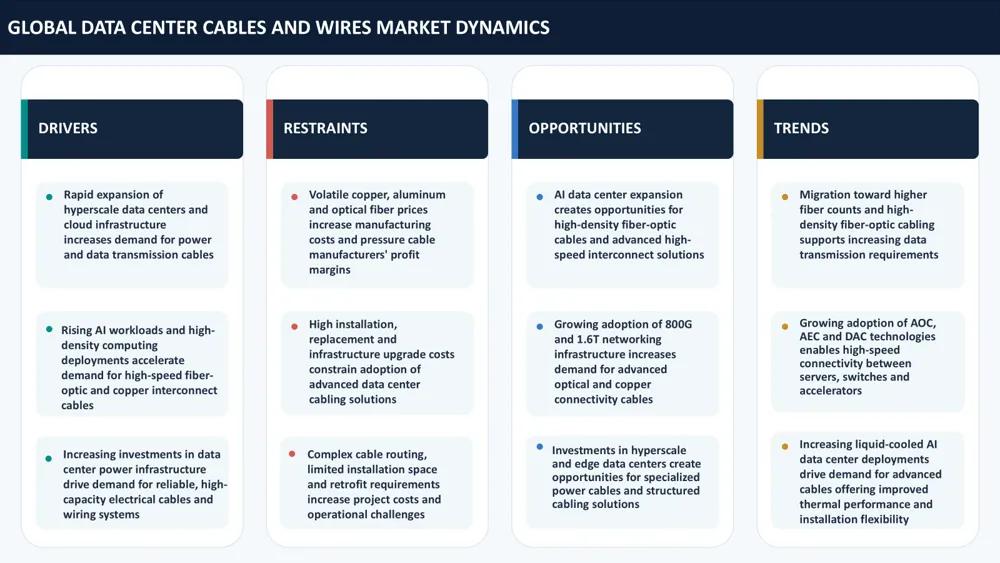
GLOBAL DATA CENTER CABLES AND WIRES MARKET: MARKET DYNAMICS
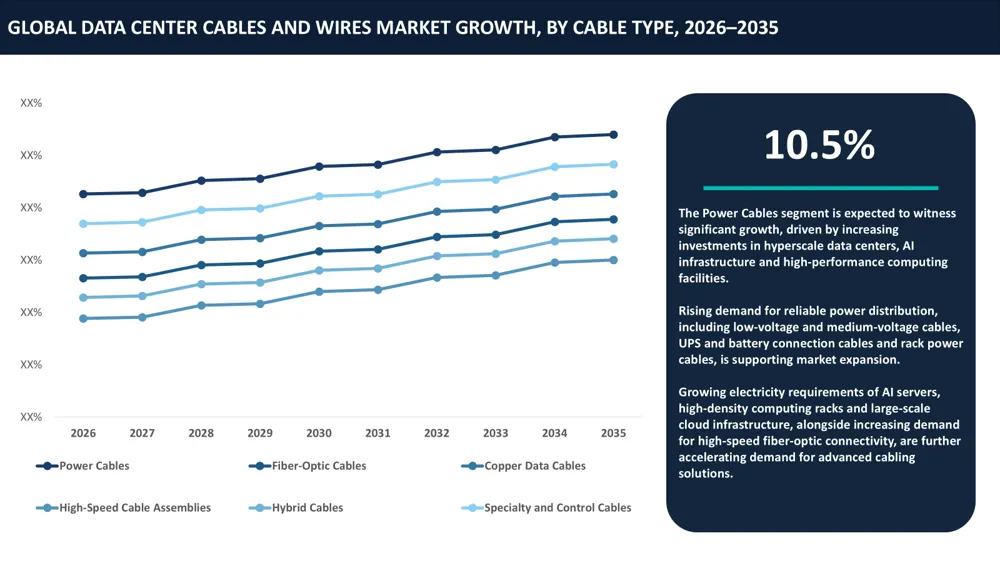
GLOBAL DATA CENTER CABLES AND WIRES MARKET: MARKET SEGMENT ANALYSIS
GLOBAL DATA CENTER CABLES AND WIRES MARKET: REGION WISE ANALYSIS
GLOBAL DATA CENTER CABLES AND WIRES MARKET: MARKET SCOPE
| Metrics | Details | |
| Market Size in 2025 (Value) | USD 14.85 Billion | |
| Market Size in 2026 (Value) | USD 16.47 Billion | |
| Market Forecasted in 2035 (Value) | USD 32.99 Billion | |
| CAGR (2026-2035) | 10.9% | |
| Years Considered | 2024-2035 | |
| Base Year | 2025 | |
| Forecast Period | 2026-2035 | |
| By Cable Type | Power Cables Fiber-Optic Cables Copper Data Cables High-Speed Cable Assemblies Hybrid Cables Specialty and Control Cables | |
| By Shielding Type | Shielded Cables Unshielded Cables | |
| By Armoring Type | Armored Cables Unarmored Cables | |
| By Fire Performance | Fire-Resistant Cables Fire-Retardant Cables | |
| By Smoke and Halogen Characteristics | Low-Smoke Zero-Halogen (LSZH) Cables Non-LSZH Cables | |
| By Installation Rating | Plenum-Rated Cables Riser-Rated Cables | |
| By Application | Power Distribution and Electrical Connectivity Structured Cabling and Network Connectivity High-Speed Data Transmission and Interconnects Storage and Rack-Level Connectivity Campus and Backbone Connectivity Monitoring, Control and Safety Systems | |
| By Data Center Type | Hyperscale Data Centers Colocation Data Centers Enterprise Data Centers Edge and Micro Data Centers Modular Data Centers | |
| By Data Center Size | Tier I Data Centers Tier II Data Centers Tier III Data Centers Tier IV Data Centers | |
| By Deployment Location | Internal Rack and Server Cabling Data Hall and Row-Level Cabling Electrical Room and Power Distribution Cabling Raised-Floor and Underfloor Cabling Overhead Cable Tray and Ceiling Cabling External Campus and Inter-Facility Cabling | |
| By End-User | Cloud Service Providers Colocation Service Providers Enterprises and Private Data Center Operators Telecommunications and Network Service Providers Government and Defense Data Center Operators | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Turkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Market Share, Market Growth | |
GLOBAL DATA CENTER CABLES AND WIRES MARKET: TARGET AUDIENCE
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| CABLE AND WIRE MANUFACTURERS | Power cable, copper cable, fiber-optic cable and specialty cable producers | Evaluate product demand, manufacturing capacity, pricing trends, competitive positioning and market expansion opportunities. |
| OPTICAL FIBER AND CONNECTIVITY PROVIDERS | Optical fiber producers, high-speed interconnect manufacturers and connectivity solution providers | Assess fiber demand, high-density connectivity adoption, 800G and 1.6T infrastructure requirements and emerging technology opportunities. |
| CABLE ASSEMBLY MANUFACTURERS | Direct Attach Copper (DAC), Active Electrical Cable (AEC), Active Optical Cable (AOC) and hybrid cable assembly manufacturers | Identify AI data center opportunities, high-speed interconnect demand, product development priorities and evolving customer requirements. |
| RAW MATERIAL SUPPLIERS | Copper, aluminum, optical fiber, polymer and cable insulation material suppliers | Analyze raw material consumption, price trends, supply-chain requirements and future demand from cable manufacturers. |
| DATA CENTER OPERATORS | Hyperscale cloud providers, enterprise data center operators and AI infrastructure developers | Evaluate cable procurement requirements, power distribution needs, connectivity technologies and infrastructure expansion strategies. |
| COLOCATION AND EDGE DATA CENTERS | Colocation providers, edge data center developers and managed infrastructure operators | Assess cabling requirements, network scalability, infrastructure modernization and regional investment opportunities. |
| ELECTRICAL EQUIPMENT AND INFRASTRUCTURE OEMs | Power distribution equipment manufacturers, server OEMs, networking equipment suppliers and rack infrastructure providers | Understand cable compatibility, power density requirements, connectivity trends and evolving data center infrastructure needs. |
| DISTRIBUTORS AND SYSTEM INTEGRATORS | Cable distributors, electrical contractors, EPC companies and data center infrastructure integrators | Identify procurement opportunities, regional demand patterns, supplier capabilities and emerging customer requirements. |
| INVESTORS AND POLICYMAKERS | Strategic investors, financial institutions, government agencies and industry consultants | Assess market opportunities, investment potential, manufacturing expansion, regional supply-chain exposure and infrastructure development trends. |
| CABLE AND WIRE MANUFACTURERS | Power cable, copper cable, fiber-optic cable and specialty cable producers | Evaluate product demand, manufacturing capacity, pricing trends, competitive positioning and market expansion opportunities. |
WHY DOES THIS REPORT MATTER IN 2026?
The global data center cables and wires market is going to see a period of crucial development and transformation in 2026 with hyperscale cloud companies, artificial intelligence (AI) firms, colocation facilities and technology companies making more investments in advanced data center infrastructures. The growth of AI workload, high-performance computing, expansion of cloud infrastructures and growing demands on data processing are driving the investments in the US, China, India, Japan, South Korea and Europe. This shift is making data center cabling an important technology rather than just an infrastructural part of the system by facilitating high-speed data transfer, power distribution, large-scale connectivity and AI infrastructure development.
Meanwhile, cable producers and connectivity suppliers have come under increased demands for better bandwidth, better signal quality, more power handling and reliable connectivity in the face of increasing complexity of the infrastructure and fluctuating cost of raw materials. The fast evolution of technologies related to high density fiber optic cables, copper interconnects, DAC, AEC, AOC and 800G, 1.6T networking is changing competitive positioning within the industry. The buyers, investors and technology players need to have better insight into the manufacturing capacities of cable producers, product demand, average selling price, cost of the raw materials, capabilities of suppliers, adoption of the new technologies, regional investments in infrastructure and competitive positioning to make the right strategic decision regarding future market opportunities.
GLOBAL DATA CENTER CABLES AND WIRES MARKET: ANALYST VIEW / OPINION
The global data center cables and wires market is increasingly characterized by two simultaneous demand patterns: conventional power and structured cabling requirements supporting ongoing data center construction and advanced high-speed connectivity requirements driven by AI infrastructure and hyperscale computing. It is not possible to forecast these two segments using the same assumptions regarding demand and price considerations. In traditional infrastructure, power cables, copper cables and standard fiber-optics are used for electricity transmission and networks. For advanced AI infrastructures, dense fiber-optic cables, DAC, AEC and AOC assemblies have emerged as key components as the need for higher bandwidths, rack density and speeds increases.
Three competitive challenges require attention. First, the increasing workloads of AI systems and the rising power densities of racks make the need for better cable properties and higher connectivity reliability more prominent. These threats must be addressed by increased R&D efforts, improved manufacturing capabilities and cooperation with data center owners and infrastructure OEMs. Second, changes in the price level of copper, aluminum, optical fiber and polymers may result in increased manufacturing costs and lower margin rates for the manufacturer. Long-term contracts and improved manufacturing efficiency are needed for protection. Third, fast changes in networking technologies increase the risk of obsolescence of existing cable solutions due to higher bandwidths and new interconnection technologies. Having flexible products, investing in technologies and making capacity management would help to diminish this risk.
QUESTIONS THIS REPORT ANSWERS
- What are the principal demand drivers, restraints, execution risks and investment opportunities shaping the global data center cables and wires market through 2035?
- How do fiber-optic cables, copper cables, power cables, coaxial cables, hybrid cables and specialty cables differ in technology, applications and commercial demand?
- Which cable products support power distribution, structured cabling, rack interconnection, high-speed data transmission and data center campus connectivity?
- How are AI workloads, high-performance computing and high-density server racks influencing power cable and high-speed connectivity requirements?
- How will 800G and 1.6T networking infrastructure influence demand for advanced optical and copper connectivity solutions?
- What roles do DAC, AEC and AOC technologies play in server-to-server, server-to-switch and accelerator interconnections?
- How do copper, aluminum, optical fiber and polymer price fluctuations influence cable manufacturing costs, product pricing and profit margins?
- Which manufacturers offer differentiated cable portfolios, manufacturing capacity, technological capabilities and regional supply-chain advantages?
- How do North America, Europe, Asia Pacific, Latin America and the Middle East & Africa differ across data center cabling demand and infrastructure investments?
- What procurement practices, technical specifications, installation requirements and supplier selection criteria influence data center cable purchasing decisions?
- Which opportunities are emerging from hyperscale expansion, AI data center development, cloud infrastructure investments and edge data center deployments?
- What additional numerical inputs and assumptions are required to establish credible 2035 segment forecasts and a 2026–2035 CAGR?


























































