China Industrial Motors Market Size and Overview
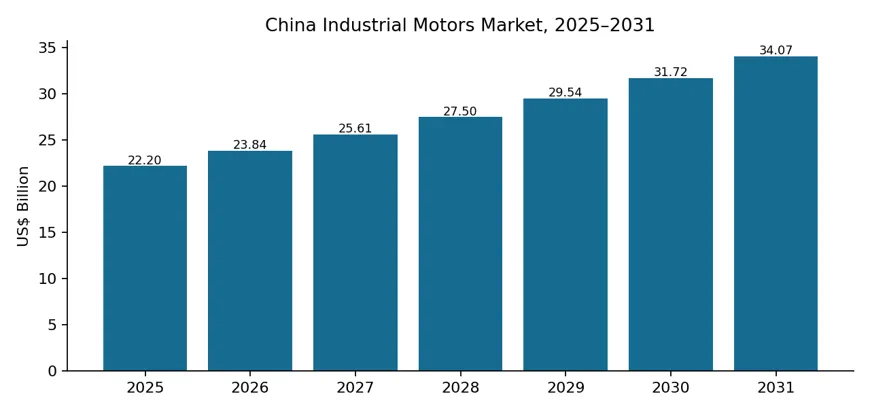
The China Industrial Motors Market is estimated at US$ 22.20 billion in 2025. Applying a 7.4% annual growth path to the industrial end-user motor series gives an estimated US$ 34.08 billion market in 2031. Demand comes from factory machinery, pumps, fans, compressors, water systems, metals, chemicals and other industrial equipment. Investment in energy-efficient equipment and replacement of older motors supports growth alongside new machinery orders.
Industrial users are placing more emphasis on total electricity costs, reliability and motor selection for specific operating loads. High-efficiency induction motors remain important, while permanent-magnet motors gain attention for applications that benefit from lower losses and better part-load performance.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026-2031) |
| US$ 22.20 Billion | US$ 34.08 Billion | 7.4% |
China Industrial Motors Key Takeaways
Industrial motor sales are estimated to rise from US$ 22.20 billion in 2025 to US$ 34.08 billion in 2031.
Motor replacements provide an ongoing market as factories seek lower energy consumption and better reliability.
Pumps, compressors and ventilation systems are important targets for efficient motors and improved motor-system designs.
Permanent-magnet synchronous motors are attracting new manufacturing investment for medium- and high-power applications.
Domestic suppliers offer broad product ranges, while large international manufacturers remain active in specialist industrial applications.
Efficiency rules and factory energy-saving programs influence equipment specifications and purchasing decisions.
China Industrial Motors Industry Trends and Strategic Insights
Factory buyers increasingly compare energy savings over the operating life of a motor rather than purchase price alone.
Permanent-magnet technology is expanding beyond small industrial drives into higher-power equipment.
Local manufacturing and technical service are important for large, custom and explosion-proof industrial motors.
Reliability, repair support and compatibility with existing machinery are major considerations in retrofit projects.
China Industrial Motors Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 22.20 Billion |
| 2031 Projected Market Size | US$ 34.08 Billion |
| CAGR (2026-2031) | 7.4% |
| By Motor Type | Induction, permanent-magnet synchronous, synchronous, DC and other motors |
| By Power Rating | Below 0.75 kW through above 375 kW |
| By Efficiency | IE2 and below, IE3, IE4, IE5 and higher-efficiency designs |
| By Application | Pumps, fans, compressors, conveyors, machine tools and process equipment |
| By End-Use | Manufacturing, chemicals, metals, mining, water, energy and food processing |
| By Sales Channel | New OEM equipment, replacements, direct and distributor sales |
| Competitive Landscape | Chinese motor makers and international suppliers active in China |
| Market Data Coverage | 2025-2031 industrial motor demand and market trends in China |
China Industrial Motors Market White Space & Investment Opportunities
High-efficiency retrofits: identify large installed motor fleets at plants with continuous pump, fan and compressor loads.
Permanent-magnet motors: target applications where savings justify a higher initial equipment cost.
Heavy-industry solutions: supply engineered motors for mining, metals, chemicals and oil and gas sites.
Industrial buyers increasingly need support in specifying motor efficiency, duty cycles and operating conditions. Suppliers with local test facilities, application engineering and dependable replacement stock are better positioned to serve large plant groups.
Driver Impact Analysis
Factory modernization and industrial energy-saving programs create demand for new and replacement motors across China. Plants are upgrading older induction motors on pumps, fans, conveyors and compressors where long operating hours make electricity savings material. Machinery OEMs also require compact, dependable motors for equipment shipments, while mining, metals and chemical producers continue to procure higher-power and application-specific units. Purchases depend on process duty, efficiency, reliability and the total cost of operation.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 IMPACT | STRATEGIC IMPACT |
| Industrial energy-efficiency upgrades | High | IE3 and IE4 motors for pumps, fans and compressors | Prioritize large installed fleets with long daily operating hours |
| Machinery OEM production | High | Low-voltage induction and permanent magnet motors | Work with machinery builders on repeat-volume motor packages |
| Permanent magnet adoption | Medium-High | Direct-drive and high-efficiency process motors | Prove energy savings at the full motor-system level |
| Heavy industry and infrastructure | Medium-High | High-power, medium-voltage and explosion-proof motors | Strengthen technical approvals and site commissioning support |
High annual utilization supports investment in IE3 and IE4 motors, but the economics vary by plant and application. Permanent magnet technology can deliver gains in direct-drive and variable-load equipment. Suppliers need to work with plant engineers to verify motor sizing, starts per hour, load profile, enclosure requirements and installation constraints before making a replacement recommendation.
Restraint Impact Analysis
Strong price competition among local motor manufacturers puts pressure on margins, particularly for standard low-voltage products. Factory operators may also postpone replacement projects when motors are still operational or planned maintenance shutdowns are limited. The higher initial cost of premium-efficiency and permanent magnet motors can slow adoption where utilization is low or electricity savings are uncertain. High-power and hazardous-area designs also require testing, certification and longer approval cycles.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Local price competition | Standard induction motors | High | Differentiate through performance, efficiency and service |
| Replacement cost and downtime | Installed motors at continuous-process sites | Medium-High | Offer plant-level payback and phased retrofit plans |
| Material-cost volatility | Copper, electrical steel and rare-earth inputs | Medium-High | Use dual sourcing and contract price-review terms |
| Technical qualification | High-power and hazardous-area motor designs | Medium-High | Complete testing and specification approvals early |
Upgrading existing motor systems can require alignment with drives, gearboxes, foundations and process controls. Some facilities lack reliable operating data to prove payback. Copper, electrical steel and rare-earth magnet price movements create additional sourcing risk, while slower capital expenditure in selected heavy-industry sectors can delay orders for larger motors. Suppliers can reduce these barriers through energy audits, staged replacement plans, local technical support and verified operating-cost comparisons.
China Industrial Motors Market Competitive Landscape
China has a broad domestic manufacturing base, ranging from standard low-voltage induction motors to high-power synchronous and explosion-proof machines. Wolong, Jiamusi, Wannan and Shanghai Electric compete in industrial motor supply, while Inovance provides permanent magnet motors and automation-related solutions. International companies compete through specialist portfolios, application engineering and established customer relationships. Buyers evaluate efficiency, price, delivery, reliability and service coverage.
| COMPANY | DATA CENTER TRANSFORMER POSITIONING |
| Wolong Electric Drive | Broad low- and high-voltage motor portfolio, including high-efficiency and explosion-proof designs. |
| Inovance Technology | Industrial automation and permanent-magnet motor systems, with new high-power production investment. |
| Jiamusi Electric Machine | Specialist motors for heavy-duty, high-voltage and explosion-proof applications. |
| Shanghai Electric | Large industrial and power-related motor equipment. |
| Anhui Wannan Electric Machine | Low- and medium-voltage industrial motors and efficiency-focused motor solutions. |
| ABB | Industrial motors serving machinery and process industries. |
| Siemens | Industrial motors across general-purpose and demanding applications. |
| WEG | Industrial and commercial motor manufacturing and engineered motor solutions. |
| Nidec | Industrial AC motors and energy-efficiency products. |
| TECO Electric & Machinery | General-purpose and energy-efficient industrial motors. |
Industrial motor competition is increasingly shaped by application expertise rather than equipment price alone. Leading suppliers are investing in permanent magnet technology, high-power manufacturing, service networks and efficiency-oriented product lines. Proven performance and compliance are particularly important for chemicals, mining and continuous-process facilities.
China Industrial Motors Market Recent Developments
April 2, 2026: Wolong expanded its Quantum motor range with a new 500-frame medium-voltage motor. The design targets replacement demand in mining, oil and gas, pumps and compressors.
April 23, 2026: Inovance began construction of a RMB 2 billion high-power motor research and manufacturing facility in Dalian. The site will produce high-voltage permanent magnet synchronous motors.
May 16, 2026: Wolong Electric Group introduced a 50 Mvar two-pole distributed synchronous condenser through its Nanyang business, expanding its large rotating electrical machine portfolio.
June 17, 2026: Wolong reported successful application of a 105 MW two-pole high-speed motor at the Feicheng compressed-air energy storage project in Shandong.
June 25, 2026: Wolong Nanyang published a retrofit solution for a 900 kW, 10 kV wound-rotor motor, highlighting modernization requirements for existing industrial equipment.
August 14, 2026: Wolong Nanyang presented a customized industrial motor application for seawater desalination, highlighting motor selection for water-treatment processes.