


Canada Power Transformer Market Size and Overview
The Canada Power Transformer Market reaches US$ 2.62 billion in 2025 and is forecast at US$ 3.17 billion by 2031, representing 3.28% annualized growth. The quantified workbook series is LV/MV Transformers; high-voltage transmission and large-power transformer applications are included in industry analysis rather than added to the stated market total.
Canada’s demand is shaped by Hydro-Quebec transmission and distribution investments, Ontario grid reinforcement, new industrial loads, resource-sector electrification and expanding data-center campuses. Transformer procurement prioritizes utility qualification, low-loss engineering, cold-weather reliability, domestic service coverage and timely capacity allocation.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
| US$ 2.62 Billion | US$ 3.17 Billion | 3.28% |
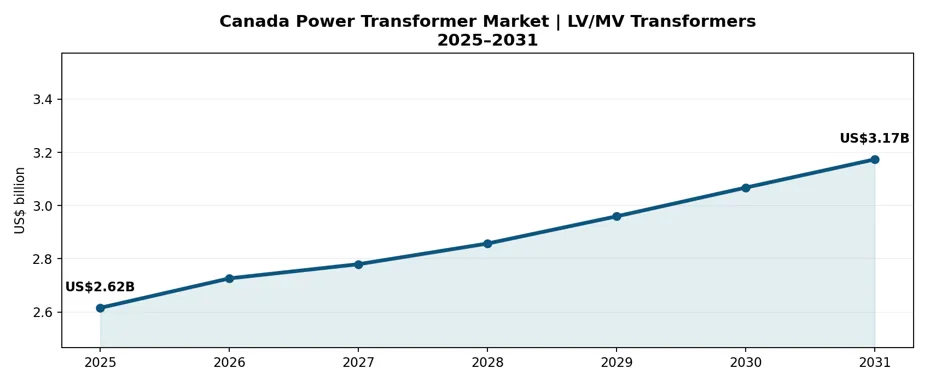
Canada LV/MV transformer revenue increases from US$ 2.62 billion in 2025 to US$ 3.17 billion in 2031.
The quantified LV/MV transformer category records 3.28% annualized growth across 2025–2031.
Ontario and Quebec utility investment supports replacement, substation capacity and medium-voltage equipment procurement.
Data centers, mining electrification and EV supply-chain manufacturing create demand for dedicated medium-power substations.
Pressboard insulation, grain-oriented electrical steel, bushings and transformer testing availability remain critical procurement considerations.
Canadian insulation production investment and domestic engineering capacity create opportunities for transformer supply-chain localization.
Canada Power Transformer Industry Trends and Strategic Insights
Provincial utilities are prioritizing reliability, climate resilience, transformer replacement and substation capacity additions.
Data-center project developers increasingly reserve transformer manufacturing slots during site selection and utility interconnection planning.
Canadian transformer manufacturing is gaining importance as North American suppliers expand regional insulation and component capacity.
Procurement criteria increasingly emphasize total ownership cost, transformer losses, ester dielectric options and remote condition monitoring.
Canada Power Transformer Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 2.62 Billion |
| 2031 Projected Market Size | US$ 3.17 Billion |
| CAGR (2026–2031) | 3.28% |
| By Transformer Type | Canada; provincial electricity utilities; industrial power users |
| By End-Use Industry | Distribution; medium-power; high-power applications and retrofits |
| By Voltage Rating | LV; MV; HV; EHV |
| By Cooling and Insulation | Oil-immersed; ester-filled; dry-type; alternative insulation |
| By Component | Core; windings; bushings; tap changers; cooling; monitoring |
| By Phase and Installation | Single-phase; three-phase; pad/pole/ground-mounted; substations |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, market developments and partnerships |
| Market Data Coverage | Cable-family and cable-subtype market values, 2025–2031 (US$ million); segmentation, competition and market dynamics |
Coverage: Canada. Quantified series: LV/MV Transformers. Analysis includes distribution and medium-power transformers, relevant transmission applications, cooling and insulation technology, voltage classes, utility and industrial demand, manufacturing capabilities and aftermarket services.
Canada Power Transformer Market White Space & Investment Opportunities
Utility fleet renewal: pursue long-term framework contracts for distribution units, spares and substation replacement programs.
Data-center and heavy-industry substations: provide engineered medium-power transformers aligned with grid-connection milestones.
Insulation supply-chain localization: invest in pressboard, core assembly, winding capacity, testing and refurbishment services.
Opportunities concentrate around Ontario and Quebec utilities, Alberta industrial electrification and renewable projects across the provinces. Supplier differentiation increasingly depends on approved-vendor status, service response and guaranteed delivery.
Driver Impact Analysis
Aging utility fleets, electricity-load growth and hardening of distribution networks drive transformer replacements and capacity additions. Ontario manufacturing, Quebec transmission projects and major data-center loads increase demand for medium-voltage interconnections.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Utility replacements and reliability | High | Provincial fleet upgrades | Secure multi-year utility qualifications |
| Data-center and mining loads | High | New substations and capacity additions | Early engineer-to-order engagement |
| Clean-power connections | Medium-High | Transformer step-up demand | Align project design and commissioning |
| Domestic insulation expansion | Medium-High | Supply reliability benefits | Local component partnerships |
Hydroelectric and renewable generation connections, mining electrification and greater integration with North American equipment supply chains stimulate specification-driven purchases and long-term transformer manufacturing reservations.
Restraint Impact Analysis
Long lead times for grain-oriented electrical steel, copper conductors, pressboard, specialty bushings and factory acceptance testing can constrain deliveries. Canadian utilities often require extensive certifications and operational track records.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Specialty electrical steel and copper | High | Input cost and availability | Long-term material supply terms |
| Testing and factory capacity | High | Equipment delivery bottlenecks | Reserve manufacturing slots |
| Utility qualification requirements | Medium-High | Long entry cycles | Certifications and reference projects |
| Provincial utility scheduling | Medium | Interconnection timing risks | Staged procurement |
Interconnection delays, logistics for heavy units, provincial specification differences and currency exposure can shift project economics and equipment schedules. Cold-climate reliability further raises qualification and engineering requirements.
Canada Power Transformer Market Competitive Landscape
The market comprises Canadian transformer specialists, global OEM manufacturing and service networks and North American distribution-transformer suppliers. Competition focuses on utility qualification, electrical efficiency, engineering flexibility, lead-time certainty and onshore support.
| COMPANY | CANADA POWER TRANSFORMER POSITIONING |
| Hitachi Energy Canada | Canada-based power transformer manufacturing; Varennes, Quebec facility and insulation investments. |
| Hammond Power Solutions | Canadian dry-type and custom transformer manufacturer; power quality and industrial markets. |
| Siemens Energy Canada | Transmission and large-power transformer solutions for utility and industrial customers. |
| Schneider Electric Canada | Distribution and dry-type transformers, monitoring, retrofit and industrial equipment. |
| Eaton Canada | Industrial and distribution transformer portfolio with Canadian service channels. |
| ABB Canada | Utility and industrial transformer offerings, insulation and monitoring capabilities. |
| GE Vernova / Prolec GE | North American distribution-transformer manufacturing and service network. |
| Northern Transformer | Canadian engineered-to-order large-power transformers and related services. |
| Delta Star | Power transformers serving utility and industrial transmission applications in North America. |
| Moloney Electric | North American utility distribution-transformer supplier with Canadian market relevance. |
Canadian manufacturing footprint, supplier resilience, technical responsiveness and transformer-monitoring services are strategic differentiators, especially for multi-year provincial infrastructure investment programs.
Canada Power Transformer Market Recent Developments
October 16, 2026 — Hitachi Energy announced a CAD 479 million transformer insulation factory in London, Ontario, establishing Canada’s first electrical-grade pressboard manufacturing capability.
October 16, 2026 — The Government of Canada announced CAD 30 million in federal support for Hitachi Energy’s London transformer insulation project, which is expected to create more than 100 jobs.
June 17, 2026 — Hitachi Energy signed a definitive agreement to acquire Ontario-headquartered Canduct Group, a manufacturer of transformer insulation kits and components. Closing was subject to customary conditions.
September 22, 2026 — Ontario-based Hammond Power Solutions announced a planned Fort Worth, Texas transformer factory, with an initial CAD 250 million manufacturing-capacity target and staged operations expected from 2027.
March 2026 — Hammond Power Solutions reported plans to increase custom transformer production capacity by CAD 100 million through 2026 and early 2027.
October 16, 2026 — Ontario announced provincial support for Hitachi Energy’s new London insulation facility, including a conditional investment grant of up to CAD 20 million.


























































