


Brazil Power Transformer Market Size and Overview
The Brazil Power Transformer Market is valued at US$ 1.72 billion in 2025 and is projected to reach US$ 1.82 billion in 2031, recording 0.96% annualized growth. The quantified category is LV/MV Transformers; larger transmission-class transformer opportunities are addressed as part of the wider market landscape.
Brazilian demand reflects replacement of aging distribution transformers, utility reliability investments, substations serving transmission concessions and industrial load additions across Sao Paulo, Minas Gerais, Rio Grande do Sul, Bahia and the Northeast. Utility qualification, transformer-loss performance, delivery certainty and local maintenance availability shape purchasing decisions.
| 2025 MARKET SIZE | 2031 FORECAST | CAGR (2026–2031) |
|---|---|---|
| US$ 1.72 Billion | US$ 1.82 Billion | 0.96% |
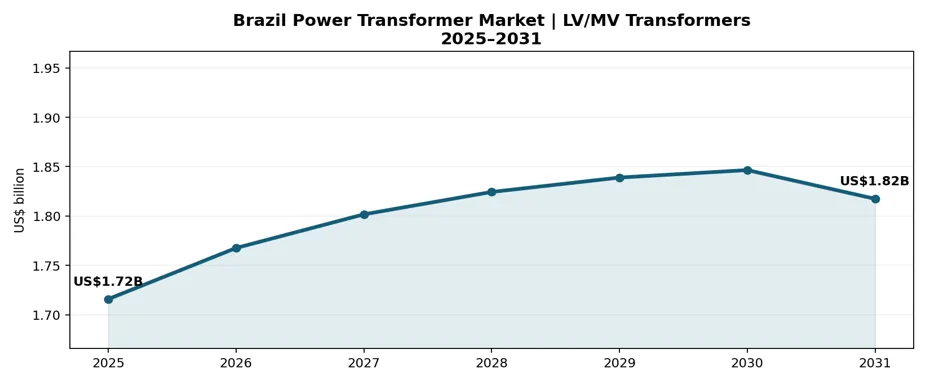
Market value advances from US$ 1.72 billion in 2025 to US$ 1.82 billion by 2031.
The LV/MV category records 0.96% annualized growth between 2025 and 2031.
The September 2026 approval of Transmission Auction 04/2026 includes 12,694 MVA of planned new transformation capacity.
Utility refurbishment and transformer-life extension provide aftermarket opportunities alongside new-unit procurement.
Renewable power connections, industrial electrification and data-center investment require resilient step-up and step-down infrastructure.
Domestic manufacturing slots, electrical steel, copper and transformer test capacity remain critical supply-side constraints.
Brazil Power Transformer Industry Trends and Strategic Insights
Transmission concessions and distribution asset-renewal programs sustain replacement and installation cycles.
Local transformer manufacturing, including WEG expansion programs, strengthens bidding competitiveness and lead-time control.
Renewable generation and industrial data-center connections elevate demand for efficiency, monitoring and electrical reliability.
Refurbishment, insulation replacement, digital monitoring and field services are commercially important recurring revenue opportunities.
Brazil Power Transformer Market Scope
| METRICS | DETAILS |
| 2025 Market Size | US$ 1.72 Billion |
| 2031 Projected Market Size | US$ 1.82 Billion |
| CAGR (2026–2031) | 0.96% |
| By Transformer Type | Brazil; distribution concessionaires; transmission operators; industrial customers |
| By End-Use Industry | LV/MV distribution and power transformers; transmission applications; utility and industrial equipment |
| By Voltage Rating | LV; MV; HV; EHV |
| By Cooling and Insulation | Oil-immersed; ester-filled; dry-type; alternative insulation |
| By Component | Core; windings; bushings; tap changers; cooling; monitoring |
| By Phase and Installation | Single-phase; three-phase; pad/pole/ground-mounted; substations |
| By Installation Method | Overhead; Underground / Buried; Submarine / Underwater; Indoor / Building; Outdoor / Industrial |
| Competitive Landscape | Competitive positioning, 10 company profiles, market developments and partnerships |
| Market Data Coverage | Cable-family and cable-subtype market values, 2025–2031 (US$ million); segmentation, competition and market dynamics |
Coverage: Brazil. Quantified market: LV/MV Transformers. Additional analysis covers power-transformer applications at higher voltage, dry-type and liquid-filled technologies, utility and industrial buyers, monitoring and diagnostic services, refurbishment and replacement.
Brazil Power Transformer Market White Space & Investment Opportunities
Utility replacement programs: pursue long-term supply and retrofit relationships with distribution concessionaires and transmission operators.
Renewable and transmission buildout: map transformer opportunities to ANEEL auctions, concession awards and grid-connection timetables.
Local service and refurbishment: expand testing, rewinding, insulating-material replacement and predictive monitoring offerings.
Commercial opportunities span Sao Paulo, Minas Gerais, southern industrial states and renewable-energy corridors in the Northeast. Winning strategies combine ANEEL-linked project visibility, factory capacity, technical qualification, installation support and aftermarket service.
Driver Impact Analysis
Electricity network reinforcement, distribution-system reliability investment and power-transmission concessions drive transformer procurement. Substation tenders generate demand for step-up and step-down transformers, bushings, oil processing and related maintenance services.
| DRIVER | AFFECTED PRODUCT / SIGNAL | 2026–2031 CAGR | STRATEGIC IMPACT |
| Grid and distribution renewal | High | Ongoing transformer replacement | Build utility supply programs |
| Transmission concession awards | High | Substation investment opportunities | Track ANEEL auction pipeline |
| Renewables and industrial demand | Medium-High | New step-up and MV needs | Map grid interconnections |
| Local manufacturing expansion | Medium-High | Reduced sourcing constraints | Secure factory allocation |
Industrial additions, renewable interconnections and data-center connections support demand for energy-efficient units, condition monitoring and resilient medium-voltage distribution. Local production capacity improves fulfilment and qualification.
Restraint Impact Analysis
Electrical steel, copper, insulation, bushings and testing availability can extend delivery schedules. Large power transformers also face road transport limits, commissioning complexity and repair-capacity bottlenecks.
| RESTRAINT | PRIMARY EXPOSURE | RISK LEVEL | STRATEGIC IMPACT |
| Core steel and copper supply | High | Input prices and lead-time pressures | Dual-source key inputs |
| Factory testing availability | High | Longer equipment lead times | Reserve production slots |
| Project permitting and transport | Medium-High | Delayed large-unit commissioning | Coordinate logistics early |
| Tender conditions and FX | Medium | Procurement and pricing risks | Strengthen local compliance |
Utility procurement requirements, local-content expectations, environmental permissions, currency movements and schedule changes in transmission projects create commercial uncertainty. Buyers balance purchase price against losses, reliability and total operating costs.
Brazil Power Transformer Market Competitive Landscape
Competition includes Brazilian transformer manufacturers, established global grid-equipment groups and specialist service providers. Procurement increasingly rewards local manufacturing capacity, validated efficiency, field service capability and firm delivery schedules.
| COMPANY | BRAZIL POWER TRANSFORMER POSITIONING |
| WEG | Brazil-headquartered manufacturer of distribution and power transformers with domestic production investment. |
| Hitachi Energy Brasil | Utility-class transformers, substation equipment and digital grid solutions supported by local operations. |
| GE Vernova / Prolec GE | Power and distribution transformer capabilities serving transmission, distribution and industrial projects. |
| Siemens Energy Brasil | Transmission and transformer systems with Brazilian engineering and grid-project participation. |
| Schneider Electric Brasil | Dry-type and medium-voltage distribution solutions for buildings and industrial operators. |
| ABB Brasil | Grid transformer solutions, insulation technology and industrial electrical applications. |
| Eaton Brasil | Electrical distribution, transformer-related solutions and industrial power infrastructure. |
| Toshiba Transmission & Distribution | Large power and transmission transformer technology applicable to the Brazilian grid. |
| Trafo Equipamentos Eletricos | Brazilian transformer equipment manufacturer serving utility and industrial electrification. |
| Mitsubishi Electric | Transformer technology and grid equipment for high-voltage electricity infrastructure. |
Manufacturing investment, distribution-utility relationships, substation project qualification and maintenance contracts support supplier differentiation and share growth.
Brazil Power Transformer Market Recent Developments
January 22, 2026 - WEG published details of a complex power-transformer revitalization project for a major Brazilian electricity distributor, highlighting asset-life extension and in-house engineering capabilities.
March 2026 - ANEEL conducted the first stage of Transmission Auction 01/2026, with approximately R$3.3 billion of planned transmission investments.
July 3, 2026 - ANEEL held the second stage of Transmission Auction 01/2026, awarding transmission concessions covering new electricity infrastructure in Mato Grosso, Mato Grosso do Sul and Sao Paulo.
August 11, 2026 - ANEEL ratified the results of lots 7–10 of the July transmission auction, advancing those transmission infrastructure concessions.
September 22, 2026 - ANEEL approved Transmission Auction 04/2026 for October 30, with R$8.9 billion of planned investments and 12,694 MVA of new transformation capacity.
October 2026 - WEG’s previously announced Betim and Gravatai transformer-manufacturing capacity investments remained scheduled for completion in the second half and final quarter of 2026, respectively.


























































