


Bladder Cancer Treatment Market Size and Overview
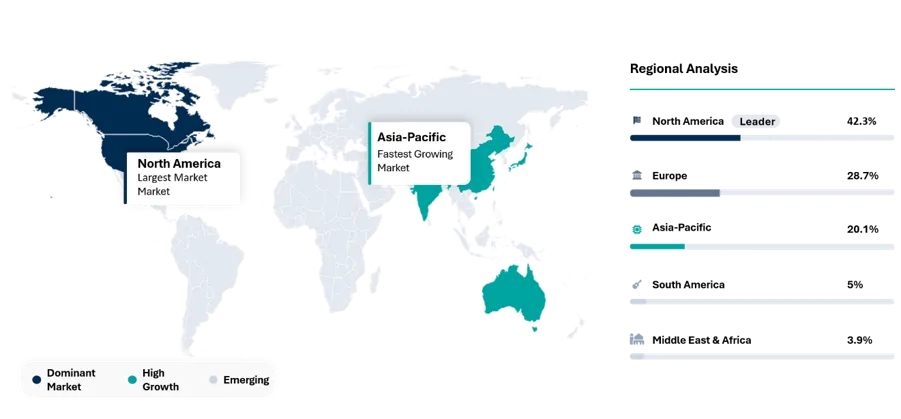
The bladder cancer treatment market reached US$5.39 billion in 2025 and is expected to reach US$9.11 billion by 2035, growing with a CAGR of 5.4% during the forecast period 2026-2035. The global bladder cancer treatment market is undergoing a significant therapeutic transition as treatment strategies move beyond conventional chemotherapy toward immunotherapy, antibody-drug conjugates, targeted therapies, gene therapies and advanced intravesical treatments. Non-muscle invasive bladder cancer remains the largest clinical segment, accounting for approximately 70-80% of newly diagnosed cases, which sustains demand for BCG therapy, transurethral resection, intravesical chemotherapy and long-term surveillance. Treatment innovation is increasingly focused on BCG-unresponsive patients and bladder-preserving alternatives that can reduce dependence on radical cystectomy. In muscle-invasive and advanced disease, combinations of immune checkpoint inhibitors and antibody-drug conjugates are increasingly moving into earlier and perioperative treatment settings. Biomarker-driven approaches, particularly therapies targeting FGFR3 alterations, are also supporting precision oncology adoption. North America accounts for about 42.3% of the global market, while Asia Pacific is gaining importance through expanding cancer-care infrastructure and improving access to advanced oncology therapies.
Bladder Cancer Treatment Market Key Takeaways
- North America dominates the global market with a 42.3% share, supported by strong oncology infrastructure, established reimbursement, high pharmaceutical spending and rapid uptake of newly approved therapies.
- Chemotherapy remains the leading treatment segment with a 36.4% market share in the existing treatment analysis, although immunotherapy and antibody-drug conjugate combinations are increasingly gaining share.
- Non-muscle invasive bladder cancer is the largest disease segment, accounting for approximately 70%-80% of newly diagnosed bladder cancer cases, creating sustained demand for TURBT, BCG, intravesical chemotherapy and bladder-preserving therapies.
- Asia Pacific is expected to be the fastest-growing regional market through 2035, driven by a large patient population, expanding oncology infrastructure and improving access to immunotherapies, targeted treatments and other advanced systemic therapies.
Bladder Cancer Treatment Market Scope
| Metrics | Details | |
| 2025 Market Size | US$5.39 Billion | |
| 2035 Projected Market Size | US$9.11 Billion | |
| CAGR (2026-2035) | 5.4% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Cancer Type | Non-Muscle Invasive Bladder Cancer, Muscle Invasive Bladder Cancer, Metastatic Bladder Cancer, Urothelial (Transitional Cell) Bladder Cancer, Squamous Cell Bladder Cancer, Papillary Bladder Cancer, Others | |
| By Grade | Low-Grade Bladder Cancer, High-Grade Bladder Cancer | |
| By Treatment Type | Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy, Surgery, Medications, Gene Therapy, Others | |
| By End-User | Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Academic and Research Institutes, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Bladder Cancer Treatment Market White Space & Investment Opportunities
- Next-Generation Bladder-Preserving Therapies for BCG-Unresponsive NMIBC: Invest in novel intravesical immunotherapies, gene therapies, oncolytic platforms and sustained-release drug delivery systems that can provide durable responses while reducing the need for radical cystectomy. Opportunities are particularly attractive for therapies that can be administered in outpatient settings, demonstrate prolonged recurrence-free survival and address patients who fail or cannot tolerate BCG.
- Biomarker-Guided and Precision Treatment Selection: Develop companion diagnostics and molecular profiling tools capable of identifying FGFR alterations, immune-response markers and other actionable biomarkers. Better patient stratification can improve treatment selection across targeted therapies, immunotherapies and antibody-drug conjugates while reducing ineffective treatment cycles and supporting more personalized sequencing of bladder cancer therapies.
- Earlier-Line Combination and Perioperative Treatment Strategies: Invest in combination regimens that move advanced therapies into neoadjuvant, adjuvant and earlier-stage disease settings. Immunotherapy, antibody-drug conjugates and targeted agents used around surgery create opportunities to improve pathological response, reduce recurrence risk and expand addressable patient populations beyond metastatic disease, particularly in muscle-invasive bladder cancer.
Bladder Cancer Treatment Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Overall Response and Complete Response Rates
- Progression-Free and Overall Survival Outcomes
- Durability of Treatment Response
- Recurrence and Disease Progression Reduction
- Safety and Tolerability Profile
- Bladder Preservation Potential
- Compatibility With BCG and Other Standard Therapies
- Suitability by Disease Stage and Risk Category
- Biomarker and Molecular Eligibility Requirements
- Route of Administration and Treatment Convenience
- Frequency and Duration of Treatment
- Need for Hospital-Based Administration and Monitoring
- Regulatory Approval and Guideline Inclusion
- Reimbursement Coverage and Treatment Cost
- Physician Familiarity and Clinical Adoption
Bladder Cancer Treatment Market BCG Matrix: Company Evaluation
STAR
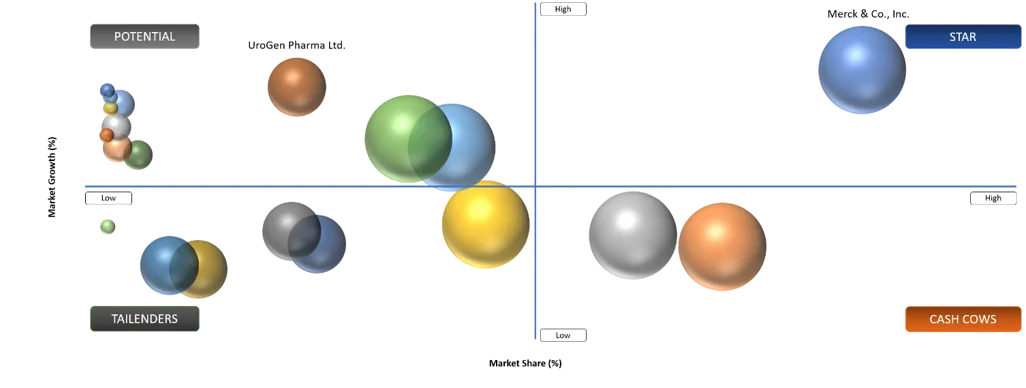
Merck & Co., Inc., Astellas Pharma Inc., AstraZeneca PLC, Bristol Myers Squibb Company, and ImmunityBio, Inc. represent the Star category due to their strong presence in bladder cancer treatment, established oncology portfolios, and continued expansion through regulatory approvals and clinical development. Merck and Astellas have strengthened their position through the KEYTRUDA and PADCEV combination, which received expanded U.S. FDA approval in July 2026 for neoadjuvant treatment followed by adjuvant therapy in muscle-invasive bladder cancer. AstraZeneca and Bristol Myers Squibb maintain substantial immuno-oncology capabilities across urothelial cancer, while ImmunityBio has developed a differentiated position in BCG-unresponsive NMIBC. Strong commercialization infrastructure, broad clinical programs, regulatory experience, and expansion into earlier treatment settings support continued competitive strength for these companies.
POTENTIAL
UroGen Pharma Ltd., CG Oncology, Inc., enGene Holdings Inc., Protara Therapeutics, Inc., and Bicycle Therapeutics plc represent the Potential category in the bladder cancer treatment market due to their expanding clinical pipelines and focus on areas of unmet need, particularly non-muscle invasive bladder cancer. UroGen Pharma is advancing UGN-103, while CG Oncology is progressing cretostimogene for BCG-unresponsive NMIBC. enGene Holdings is developing detalimogene voraplasmid as a non-viral gene therapy, whereas Protara Therapeutics and Bicycle Therapeutics are exploring differentiated therapeutic approaches. These companies have the potential to strengthen their competitive positions if ongoing programs demonstrate durable efficacy, achieve regulatory approvals, and gain physician acceptance. However, their commercial scale remains comparatively lower than established oncology leaders, making execution of late-stage development and commercialization strategies critical.
Bladder Cancer Treatment Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Expansion of Immunotherapy and Antibody-Drug Conjugate Combinations | 16.2% | Treatment adoption and earlier-line therapy | Muscle-invasive and advanced bladder cancer | Expansion of KEYTRUDA plus PADCEV into perioperative MIBC is increasing the addressable patient population and accelerating adoption of advanced combination therapies. |
Growing Adoption of Bladder-Preserving Therapies | 13.6% | Treatment choice and outpatient management | Non-muscle invasive bladder cancer | New intravesical treatments are providing alternatives to repeated surgery and supporting greater use of localized, bladder-preserving treatment strategies. ZUSDURI received FDA approval in June 2025 for recurrent LG-IR-NMIBC. |
Increasing Integration of Immunotherapy With BCG | 11.4% | High-risk NMIBC treatment expansion | BCG-naïve high-risk NMIBC patients | Combining established BCG therapy with checkpoint inhibitors is expanding therapeutic options. The FDA approved durvalumab plus BCG for BCG-naïve high-risk NMIBC in May 2026. |
Driver: Expansion of Immunotherapy and Antibody-Drug Conjugate Combinations
The expansion of immunotherapy and antibody-drug conjugate combinations is a major driver of the bladder cancer treatment market. These regimens are moving beyond advanced disease into earlier treatment settings, significantly widening their eligible patient populations. In July 2026, the FDA approved pembrolizumab with enfortumab vedotin as neoadjuvant treatment followed by adjuvant therapy for cystectomy-eligible adults with muscle-invasive bladder cancer, extending use to both cisplatin-eligible and ineligible patients. Such indication expansion is reshaping treatment pathways, increasing utilization of high-value oncology therapies and encouraging continued investment in combination regimens that can improve outcomes across multiple stages of bladder cancer.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
BCG Supply Constraints | 14.3% | Treatment availability | High-risk NMIBC patients | Limited BCG manufacturing capacity and periodic shortages can delay treatment, alter dosing schedules and increase reliance on alternative therapies. |
High Recurrence and Surveillance Burden | 11.8% | Patient monitoring and healthcare utilization | Recurrent NMIBC patients | Frequent cystoscopy, imaging and retreatment increase long-term care burden, patient inconvenience and overall treatment costs. |
Limited Eligibility for Biomarker-Driven Therapies | 9.4% | Precision treatment adoption | FGFR-altered urothelial cancer patients | Targeted therapies require specific molecular alterations and companion testing, restricting the eligible patient pool and limiting broader adoption. |
Restraint: BCG Supply Constraints
Persistent BCG supply limitations remain a significant restraint on the bladder cancer treatment market, particularly for patients with high-risk non-muscle invasive bladder cancer. BCG is a standard intravesical therapy, but constrained manufacturing capacity and periodic shortages can delay treatment initiation and disrupt planned maintenance schedules. Hospitals may need to ration available doses, modify treatment protocols, or shift patients toward alternative intravesical or systemic therapies. These supply challenges also create regional disparities in treatment access and increase pressure on healthcare providers to prioritize eligible patients. Continued dependence on limited manufacturing sources may therefore restrict consistent treatment delivery and slow overall market expansion.
Bladder Cancer Treatment Market Segment Analysis
By Cancer Type
Non-muscle-invasive bladder cancer represents 70%-80% of newly diagnosed cases, making it the largest bladder cancer segment by patient volume. These tumors include Ta, carcinoma in situ and T1 disease and are generally managed initially with TURBT. Patients at intermediate or high risk can subsequently receive intravesical chemotherapy or BCG.
The large patient pool, combined with recurrent disease and maintenance treatment requirements, gives NMIBC substantial commercial importance. Growth is becoming stronger as pharmaceutical treatment expands beyond BCG to include durvalumab combinations, ANKTIVA, ADSTILADRIN and newer intravesical chemotherapy formulations.
Muscle-invasive bladder cancer represents the smaller but more treatment-intensive segment. MIBC generally accounts for 20%-30% of cases at diagnosis and can require neoadjuvant systemic therapy, radical cystectomy, radiation, chemotherapy and adjuvant treatment. The entry of perioperative immunotherapy and ADC combinations increases revenue per treated patient and expands pharmaceutical participation in curative-intent disease.
Metastatic bladder cancer represents a smaller patient population but remains one of the most commercially intensive segments because treatment can involve ADCs, immune checkpoint inhibitors, platinum chemotherapy and FGFR-targeted therapy.
By Histology
Urothelial or transitional cell carcinoma accounts for more than 90% of bladder cancers, making it the dominant histological segment. Squamous cell carcinoma represents 2%-7%, while adenocarcinoma accounts for close to 2%.
The dominance of urothelial carcinoma explains why most major pharmaceutical development programs and regulatory approvals are concentrated in urothelial disease.
By Treatment Type
Chemotherapy held 36.4% of the bladder cancer treatment market in 2024, making it the largest treatment category in the existing market analysis.
Chemotherapy remains important across multiple settings. Intravesical gemcitabine and mitomycin are used in NMIBC, while cisplatin-containing combinations remain relevant in MIBC and advanced urothelial cancer.
Its market position is changing, however, as immunotherapy and ADC combinations move into earlier lines of treatment. Pembrolizumab plus enfortumab vedotin can now be used perioperatively in MIBC, while durvalumab has entered both MIBC and BCG-naïve high-risk NMIBC.
Immunotherapy Is One of the Fastest-Expanding Treatment Categories
Immunotherapy now includes BCG, PD-1/PD-L1 checkpoint inhibitors, IL-15-based therapy and gene-based immune stimulation.
The May 2026 approval of durvalumab plus BCG broadened checkpoint-inhibitor use to BCG-naïve high-risk NMIBC. ANKTIVA plus BCG addresses BCG-unresponsive NMIBC, while pembrolizumab, nivolumab, atezolizumab and avelumab participate in later-stage or perioperative treatment.
Targeted Therapy Is Becoming More Biomarker-Defined
Erdafitinib is used for selected locally advanced or metastatic urothelial cancers carrying susceptible FGFR3 alterations. This segment remains smaller than chemotherapy or immunotherapy but carries high strategic value because treatment is directly connected to molecular testing.
Gene and Intravesical Therapy Are Expanding the NMIBC Market
ADSTILADRIN provides an intravesical gene-therapy option for high-grade BCG-unresponsive NMIBC, while ZUSDURI addresses recurrent low-grade intermediate-risk disease.
These treatments expand the market for bladder-preserving therapy and reduce the historical dependence on repeated surgery or radical cystectomy in selected patients.
By Grade
High-grade bladder cancer generates greater treatment intensity because of the higher risk of muscle invasion, recurrence and metastatic progression. High-grade NMIBC often requires BCG induction and maintenance or newer immune-based treatments, while persistent high-grade disease can lead to cystectomy.
Low-grade disease has a lower risk of cancer-specific mortality but can recur repeatedly, generating sustained demand for TURBT, cystoscopy and intravesical treatment.
By End User
Hospitals and comprehensive cancer centers represent the largest treatment setting because MIBC and metastatic disease require multidisciplinary care involving medical oncology, urologic surgery, pathology, radiology and radiation oncology.
Specialty urology and oncology clinics have a particularly important role in NMIBC because TURBT follow-up, cystoscopy, BCG and intravesical drug administration can be delivered in outpatient settings. New intravesical products are increasing the commercial importance of community urology practices.
Bladder Cancer Treatment Market Geographical Penetration
U.S. Bladder Cancer Treatment Market Landscape
The U.S. bladder cancer treatment market is supported by a substantial patient burden and rapid adoption of newer systemic and bladder-preserving therapies. The American Cancer Society estimates 84,530 new bladder cancer cases and 17,870 deaths in 2026, highlighting continued demand for effective treatments across non-muscle invasive, muscle-invasive, and metastatic disease. Regulatory momentum has accelerated treatment expansion. In May 2026, the FDA approved durvalumab with BCG for BCG-naïve, high-risk non-muscle invasive bladder cancer. In July 2026, pembrolizumab or pembrolizumab plus berahyaluronidase alfa-pmph, each combined with enfortumab vedotin, received FDA approval for perioperative treatment of cystectomy-eligible muscle-invasive bladder cancer. These developments are expanding immunotherapy, antibody-drug conjugate, and bladder-preserving treatment options.
Japan Bladder Cancer Treatment Market Outlook
Japan represents an important bladder cancer treatment market due to its sizable disease burden and increasing use of advanced urothelial cancer therapies. The National Cancer Center Japan projected 25,900 new bladder cancer cases and 10,100 deaths in 2025, including 19,500 cases among men and 6,400 among women. Clinical development activity also remained active during 2025-2026. Japan’s national clinical trial registry lists studies evaluating enfortumab vedotin plus pembrolizumab in unresectable urothelial carcinoma, with enrollment beginning in October 2025, alongside a 2026 study investigating the combination as a bladder-preserving approach in muscle-invasive bladder cancer. Continued evaluation of antibody-drug conjugates, immunotherapies, and targeted regimens is broadening treatment choices and strengthening Japan’s uro-oncology treatment landscape.
Bladder Cancer Treatment Market Competitive Landscape
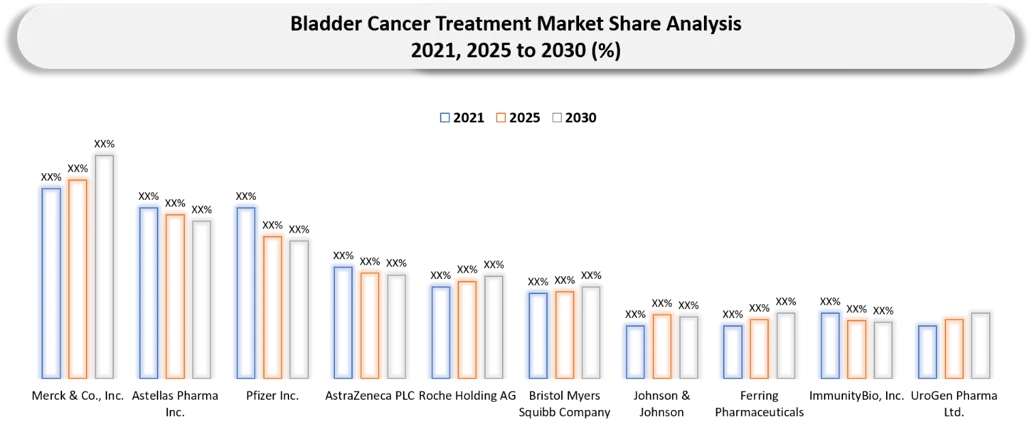
- The global bladder cancer treatment market is characterized by strong competition among established pharmaceutical companies and emerging biotechnology firms developing immunotherapies, antibody-drug conjugates, intravesical therapies, targeted treatments, and gene-based approaches. Major companies including Merck & Co., Astellas Pharma, Pfizer, AstraZeneca, Roche, Bristol Myers Squibb, Johnson & Johnson, Ferring Pharmaceuticals, ImmunityBio, and UroGen Pharma are strengthening their positions through indication expansion, clinical development, regulatory approvals, and combination-treatment strategies. In July 2026, the U.S. FDA expanded approval of Merck’s KEYTRUDA in combination with Astellas Pharma’s PADCEV as neoadjuvant and adjuvant therapy for adults with muscle-invasive bladder cancer who are candidates for cystectomy, extending the regimen across a broader MIBC population.
- Competition is also intensifying in non-muscle invasive bladder cancer, particularly around bladder-preserving therapies. UroGen Pharma received FDA approval for ZUSDURI in June 2025 for recurrent low-grade intermediate-risk NMIBC, while ImmunityBio continues to expand the clinical and geographic development of ANKTIVA plus BCG. Emerging companies are further increasing pipeline competition: CG Oncology is advancing cretostimogene grenadenorepvec through late-stage development for BCG-unresponsive NMIBC, while enGene Therapeutics is developing the non-viral gene therapy detalimogene voraplasmid and is progressing toward regulatory submission. Overall, competitive differentiation is increasingly centered on durable response, bladder preservation, expansion into earlier treatment settings, convenient intravesical delivery, combination regimens, and therapies for patients who are unresponsive or ineligible for conventional treatments.
Key Companies of Bladder Cancer Treatment Market
- Merck & Co., Inc. (United States)
- Astellas Pharma Inc. (Japan)
- Pfizer Inc. (United States)
- AstraZeneca PLC (United Kingdom)
- Roche Holding AG (Switzerland)
- Bristol Myers Squibb Company (United States)
- Johnson & Johnson (United States)
- Ferring Pharmaceuticals (Switzerland)
- ImmunityBio, Inc. (United States)
- UroGen Pharma Ltd. (Israel)
- CG Oncology, Inc. (United States)
- enGene Holdings Inc. (Canada)
- Protara Therapeutics, Inc. (United States)
- Bicycle Therapeutics plc (United Kingdom)
- RemeGen Co., Ltd. (China)
- BeOne Medicines Ltd. (Switzerland)
- Exelixis, Inc. (United States)
- Daiichi Sankyo Company, Limited (Japan)
- Aura Biosciences, Inc. (United States)
- Prokarium Holdings Ltd. (United Kingdom)
Bladder Cancer Treatment Market Recent Developments
- September 2026: Tyra Biosciences reported initial Phase 2 SURF302 results for dabogratinib, an oral FGFR3 inhibitor being developed for low-grade intermediate-risk non-muscle invasive bladder cancer. At the 60 mg once-daily dose, the study reported a 79% overall response rate and a 64% best overall complete response rate among evaluable patients, supporting the company’s planned Phase 3 development strategy.
- August 2026: UroGen Pharma submitted a New Drug Application to the U.S. FDA for UGN-103, an investigational next-generation mitomycin intravesical solution for adults with recurrent low-grade intermediate-risk non-muscle invasive bladder cancer.
- July 2026: The U.S. FDA approved Merck’s KEYTRUDA and KEYTRUDA QLEX, each in combination with Astellas Pharma’s PADCEV, as neoadjuvant treatment followed by adjuvant treatment after cystectomy for adults with muscle-invasive bladder cancer, expanding the regimen to patients regardless of cisplatin eligibility.
What DATAM Uniquely Provides
- In-depth segmentation of the Bladder Cancer Treatment Market by cancer type, grade, treatment type, end-user and region, with additional assessment of non-muscle invasive bladder cancer, muscle invasive bladder cancer, metastatic bladder cancer and major urothelial cancer treatment pathways.
- Competitive analysis of leading bladder cancer treatment companies covering marketed product portfolios, mechanism of action, clinical efficacy, dosing approach, safety profile, treatment setting, regulatory status, pipeline maturity, commercialization strategy and geographic expansion.
- Comprehensive assessment of diagnosed and treatable bladder cancer patient populations, including analysis by disease stage, recurrence status, BCG responsiveness, biomarker status and eligibility for surgery, chemotherapy, immunotherapy, targeted therapy and bladder-preserving approaches.
- Detailed evaluation of the evolving NMIBC treatment landscape, including BCG-based treatment, intravesical chemotherapy, immunotherapy, gene therapy, oncolytic therapies and emerging bladder-preserving treatment alternatives for BCG-unresponsive and recurrent patients.
- Assessment of the muscle-invasive and metastatic bladder cancer treatment pathway, covering perioperative therapy, platinum-based chemotherapy, immune checkpoint inhibitors, antibody-drug conjugates, FGFR-targeted therapies and emerging combination regimens across treatment lines.
- Pipeline and innovation tracking covering late-stage clinical candidates, upcoming regulatory submissions, recent approvals, indication expansions, novel intravesical delivery platforms, targeted therapies and next-generation combination strategies.
- Strategic opportunity assessment covering unmet clinical needs, treatment gaps, patient switching potential, biomarker-driven treatment adoption, competitive white spaces, regulatory developments, physician adoption factors and commercialization opportunities across major global markets.



























































