


Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market Size
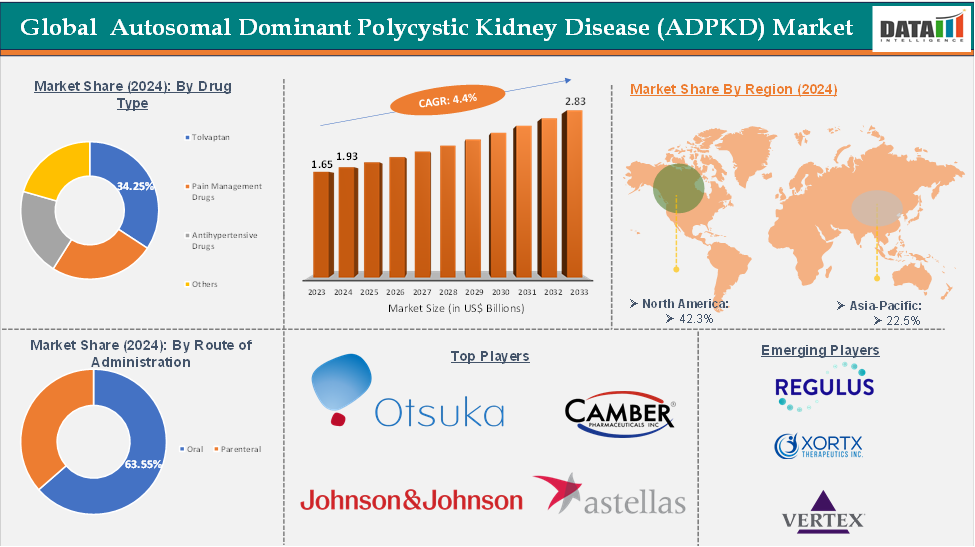
The Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market size was at USD 2.01 billion in 2025 and is expected to reach USD 2.84 billion by 2033, growing at a CAGR of 4.4% during the forecast period 2026-2033.
The global autosomal dominant polycystic kidney disease (ADPKD) market is experiencing significant transformation due to increasing disease prevalence, medical research advancements, and a growing focus on rare and genetic disorders. ADPKD is the most common inherited kidney disorder, affecting millions worldwide and often leading to end-stage renal disease, necessitating dialysis or kidney transplantation. Advancements in diagnostic tools and understanding of the disease's genetic and molecular basis have contributed to early diagnosis and personalized treatment approaches.
The market has seen promising developments with the approval of disease-modifying drugs like Tolvaptan, which have demonstrated efficacy in slowing cyst growth and preserving kidney function. Pharmaceutical companies are increasingly investing in this space, encouraged by orphan drug incentives and regulatory support across key regions like North America and Europe.
North America remains the leading region in terms of market share, supported by a well-established healthcare infrastructure, favorable reimbursement policies, and strong awareness levels among healthcare providers and patients. Asia-Pacific is expected to witness the fastest growth due to rising healthcare expenditure, improved access to specialized treatments, and a growing patient pool.
Global Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market: Executive Summary
Global Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market Dynamics: Drivers & Restraints
Driver: Rising prevalence of genetic kidney disorders
The rise in the prevalence of genetic kidney disorders, particularly autosomal dominant polycystic kidney disease (ADPKD), is driving market growth. ADPKD, a leading cause of end-stage renal disease, affects millions globally. As awareness and diagnostic tools improve, more cases are identified earlier, leading to higher prevalence rates. This, combined with increased screening through family history and genetic testing, creates a demand for targeted therapies and long-term disease management strategies. This growing patient pool prompts governments and healthcare providers to prioritize ADPKD in broader kidney health initiatives.
For instance, over 200 genetic kidney diseases account for 70% of children and 10% of adults with stage 5 Chronic Kidney Disease (CKD5), necessitating renal replacement therapy like dialysis and transplantation, with an overall prevalence of 60-80% per 100,000.
Driver: Advancements in therapeutic options
The global autosomal dominant polycystic kidney disease market is experiencing significant changes due to advancements in therapeutic options. The first disease-modifying therapy, Tolvaptan, has been approved, targeting ADPKD by inhibiting vasopressin, reducing cyst growth, and preserving kidney function. This innovation has improved patient outcomes and opened the door for further research into targeted treatments.
Clinical trials are also exploring gene therapies, anti-inflammatory agents, and cyst-reducing compounds, paving the way for more effective and personalized treatment strategies. These developments are driving interest from pharmaceutical companies, encouraging investment, and creating a dynamic market environment.
Restraint: High cost of treatment and monitoring
The global autosomal dominant polycystic kidney disease (ADPKD) market faces significant challenges due to high treatment costs and ongoing monitoring. Disease-modifying therapies like Tolvaptan are expensive, particularly in low- and middle-income countries. Continuous monitoring through advanced imaging and specialist consultations contributes to long-term healthcare expenses.
As the disease progresses, many patients require dialysis or kidney transplantation, further increasing costs. Limited reimbursement policies and out-of-pocket expenses hinder patient access to necessary treatments, even in developed regions. This economic barrier affects treatment adherence and slows the adoption of novel therapies, impacting market growth.
Opportunity: Development of gene-based and targeted therapies
The global autosomal dominant polycystic kidney disease (ADPKD) market is poised for a transformative opportunity in gene-based and targeted therapies. ADPKD, a monogenic disorder caused by mutations in the PKD1 or PKD2 genes, is a prime candidate for innovative treatments. Advances in gene editing technologies like CRISPR-Cas9, RNA interference, and antisense oligonucleotides are paving the way for precise, disease-modifying interventions.
Pharmaceutical companies are developing targeted molecules and biologics to inhibit the molecular pathways driving cyst growth, fibrosis, and inflammation in ADPKD. These breakthroughs have the potential to dramatically alter disease progression and improve long-term outcomes. With increasing R&D investment, strategic partnerships, and personalized medicine interest, the development of gene-based and targeted therapies is poised to revolutionize the treatment landscape.
For more details on this report, Request for Sample
Global Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market Segmentation Analysis
The global autosomal dominant polycystic kidney disease (ADPKD) market is segmented based on drug type, route of administration, distribution channel, and region.
Drug Type:
The tolvaptan segment from the drug type is expected to hold 34.25% of the autosomal dominant polycystic kidney disease (ADPKD) market
Tolvaptan is the first FDA-approved disease-modifying therapy for Autosomal Dominant Polycystic Kidney Disease (ADPKD), aimed at slowing its progression. It inhibits vasopressin V2 receptors, reducing fluid accumulation in kidney cysts and slowing cyst growth, preserving kidney function over time. Clinical trials like TEMPO 3:4 and REPRISE have shown their efficacy in delaying kidney function decline in patients at risk of rapid disease progression.
Tolvaptan's approval marked a major therapeutic breakthrough, driving increased physician awareness, stimulating further research, and expanding the commercial potential of the ADPKD market. However, its high cost and risk of liver toxicity necessitate careful patient selection and regular monitoring, making its use most impactful in specialized care settings.
Global Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market - Geographical Analysis
North America dominated the global autosomal dominant polycystic kidney disease (ADPKD) market with the highest share of 42.3% in 2024
North America is driving the growth of the global autosomal dominant polycystic kidney disease (ADPKD) market due to its advanced healthcare infrastructure, high prevalence of diagnosed cases, and early adoption of novel treatment options. The region benefits from strong R&D activity, favorable regulatory frameworks from the U.S. FDA, and high public awareness. Advanced imaging technologies and comprehensive insurance coverage support disease management in early and late stages, making North America a mature and innovation-driven market for ADPKD.
For instance, in May 2025, Lupin Limited, a global pharma company, announced the launch of Tolvaptan Tablets in the US, with the company holding the exclusive first-to-file status and 180-day generic drug exclusivity, following approval from the US FDA.
Asia-Pacific is the global autosomal dominant polycystic kidney disease (ADPKD) market with a market share of 22.5% in 2024
The Asia Pacific region is gaining momentum in the global ADPKD market due to increased disease awareness, healthcare expenditure, and diagnostic access. Countries like China, Japan, South Korea, and India are improving kidney disease screening programs and integrating genetic testing for earlier diagnosis. Government initiatives and public-private partnerships are promoting the development of ADPKD treatments. The growing middle class and large patient population create commercial opportunities for pharmaceutical companies to introduce novel therapies, positioning the region as a high-potential area for future ADPKD market expansion.
For instance, in February 2024, Rege Nephro Co., Ltd., a Kyoto University start-up, developed tamibarotene, a retinoic acid receptor agonist, as a clinical treatment for autosomal dominant polycystic kidney disease (ADPKD). The company-sponsored clinical trial, which will begin in mid-April 2024 or later in Japan, will recruit subjects in phases to ensure patient safety. The trial will begin in Japan once safety and tolerability are assured.
Global Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market - Key Players
The major global players in the Autosomal Dominant Polycystic Kidney Disease (ADPKD) market include Otsuka Pharmaceutical Co., Ltd, Camber Pharma, Astellas Pharma, and Johnson & Johnson, among others.
Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market – Key Developments
August 2026: Mironid raised $46 million in Series B financing to advance clinical development of its ADPKD treatment program, supporting progression of its small-molecule therapeutic toward clinical development.
- July 2026: Arnatar Therapeutics received China NMPA clearance for ART5, a first-in-class up-regulating antisense oligonucleotide designed to restore polycystin-1 production by targeting PKD1, with first-in-human testing planned for Q3 2026.
- June 2026: SCYNEXIS initiated a Phase 1 study of SCY-770, an oral direct AMPK activator acquired from Poxel, advancing a differentiated approach intended to reduce cyst growth and ADPKD disease progression.
- May 2026: Mezzion Pharma reported positive FDA pre-IND feedback for udenafil in ADPKD, supporting its nonclinical package and prior clinical safety experience as a foundation for potential Phase 2 development.
- March 2026: SCYNEXIS completed its acquisition of PXL-770 (now SCY-770), adding a clinical-stage, highly selective direct AMPK activator to its pipeline and planning a Phase 2 proof-of-concept ADPKD study for Q4 2026.
Global Autosomal Dominant Polycystic Kidney Disease (ADPKD) Market Scope
Metrics | Details | |
CAGR | 4.4% | |
Market Size Available for Years | 2023-2033 | |
Estimation Forecast Period | 2026-2033 | |
Revenue Units | Value (US$ Bn) | |
Segments Covered | Type | Tolvaptan, Pain Management Drugs, Antihypertensive Drugs, Others |
Route of Administration | Oral, Parenteral | |
| Distribution Channel | Hospital Pharmacies, Retail Pharmacies, Online Pharmacies |
Regions Covered | North America, Europe, Asia-Pacific, South America, and the Middle East & Africa | |
DMI Insights:
The global autosomal dominant polycystic kidney disease (ADPKD) market is expected to grow from US$ 1.93 billion in 2024 to US$ 2.83 billion by 2033, at a CAGR of 4.4%. This growth is driven by the increasing prevalence of genetic kidney disorders and the need for long-term management strategies. The market is dominated by North America, with robust R&D ecosystems, reimbursement frameworks, and high diagnostic capabilities. The Asia-Pacific region presents an emerging growth frontier due to healthcare investments, specialized diagnostics, and patient awareness. However, the high cost of novel treatments and monitoring remains a challenge, especially in developing regions. The future of ADPKD is promising, with gene-based and precision therapies opening new doors for disease intervention.
The global autosomal dominant polycystic kidney disease market report delivers a detailed analysis with 67+ key tables, more than 55+ visually impactful figures, and 185 pages of expert insights, providing a complete view of the market landscape.
Why Choose DataM?
- Technological Innovations: Explores advancements in ADPKD diagnosis, prognosis, monitoring, and treatment, including genetic testing, kidney imaging and volumetric assessment, risk-stratification approaches such as the Mayo Imaging Classification (MIC) and PROPKD score, and emerging data-driven and machine-learning approaches for predicting disease progression. These technologies support earlier diagnosis, identification of rapid progressors, personalized treatment decisions, and improved long-term disease management.
- Product Performance & Market Positioning: Evaluates ADPKD therapies and diagnostic approaches based on clinically relevant parameters such as their ability to slow kidney-function decline, suitability for patients at risk of rapid progression, safety and tolerability, monitoring requirements, diagnostic accuracy, and applicability across different stages of disease. Particular emphasis is placed on tolvaptan, the established disease-modifying treatment for eligible patients, alongside emerging therapeutic approaches under clinical investigation. The 2025 KDIGO guideline recommends offering tolvaptan to adults with ADPKD who have an eGFR ≥25 mL/min/1.73 m² and are at risk for rapid progression, following individualized and shared decision-making.
- Real-World Evidence: Highlights real-world management of ADPKD across nephrology practices, specialized PKD centers, diagnostic laboratories, and healthcare systems, including disease monitoring, kidney-function assessment, imaging-based risk stratification, management of hypertension and other complications, and use of disease-modifying therapy. Real-world cohorts and registry data are increasingly important for understanding treatment effectiveness, long-term tolerability, patient characteristics, and outcomes across diverse populations.
- Market Updates & Industry Changes: Tracks important developments in ADPKD research and clinical management, including publication and implementation of the KDIGO 2025 ADPKD guideline, advances in risk prediction, expansion of clinical-trial activity, development of biomarkers, and investigation of novel therapeutic strategies. Current research programs include work spanning molecular mechanisms, translational therapeutics, clinical studies, epidemiology, machine-learning-based risk prediction, and biomarker development.
- Competitive Strategies: Analyzes how pharmaceutical and biotechnology companies, diagnostic providers, research institutions, and specialized healthcare organizations compete through novel drug development, clinical-trial programs, biomarker research, precision-risk stratification, diagnostic innovation, strategic research collaborations, and expansion of specialized ADPKD care. The competitive landscape is evolving as researchers seek therapies that can complement or provide alternatives to existing disease-management approaches.
- Pricing & Market Access: Examines variations in ADPKD treatment and diagnostic costs according to therapy type, treatment duration, monitoring requirements, diagnostic modality, genetic testing, imaging procedures, healthcare setting, and geographic market. It also evaluates access considerations associated with specialist nephrology care, diagnostic laboratories, pharmaceutical distribution channels, reimbursement environments, and availability of specialized PKD services.
- Market Entry & Expansion: Identifies opportunities arising from the need for earlier diagnosis, improved identification of patients at risk of rapid progression, increasing adoption of standardized clinical-management approaches, development of new therapies, and expansion of specialized PKD research and care. Opportunities also exist in genetic and imaging-based diagnostics, biomarkers, digital and machine-learning-enabled risk prediction, clinical-trial infrastructure, and patient registries. The PKD Foundation's research programs specifically support basic, translational, clinical, epidemiological, and data-analysis research, including innovative machine-learning approaches.
Target Audience
- Pharmaceutical & Biotechnology Companies
- ADPKD Drug Developers & Clinical-Stage Biotech Companies
- Diagnostic Companies & Genetic Testing Providers
- Nephrology & Kidney Disease Specialists
- Hospitals & Specialized PKD Centers
- Clinical Research Organizations (CROs)
- Clinical Trial & Research Institutions





























































