


Artificial Blood Market Size and Overview
The global artificial blood market remains pre-commercial through 2027, with measurable revenue beginning from 2028 at USD 312.43 Thousands and expanding to USD 14,132.36 Thousands by 2035, reflecting transition from clinical development toward selective commercialization, growing with a CAGR of 74.8% during the forecast period 2030-2035. Persistent gaps in blood availability and geographic access fundamentally drive the artificial blood opportunity. WHO reports 120.4 million blood donations globally, while 36% are collected in high-income countries representing only 15% of the global population, highlighting a significant imbalance in transfusion-resource availability.
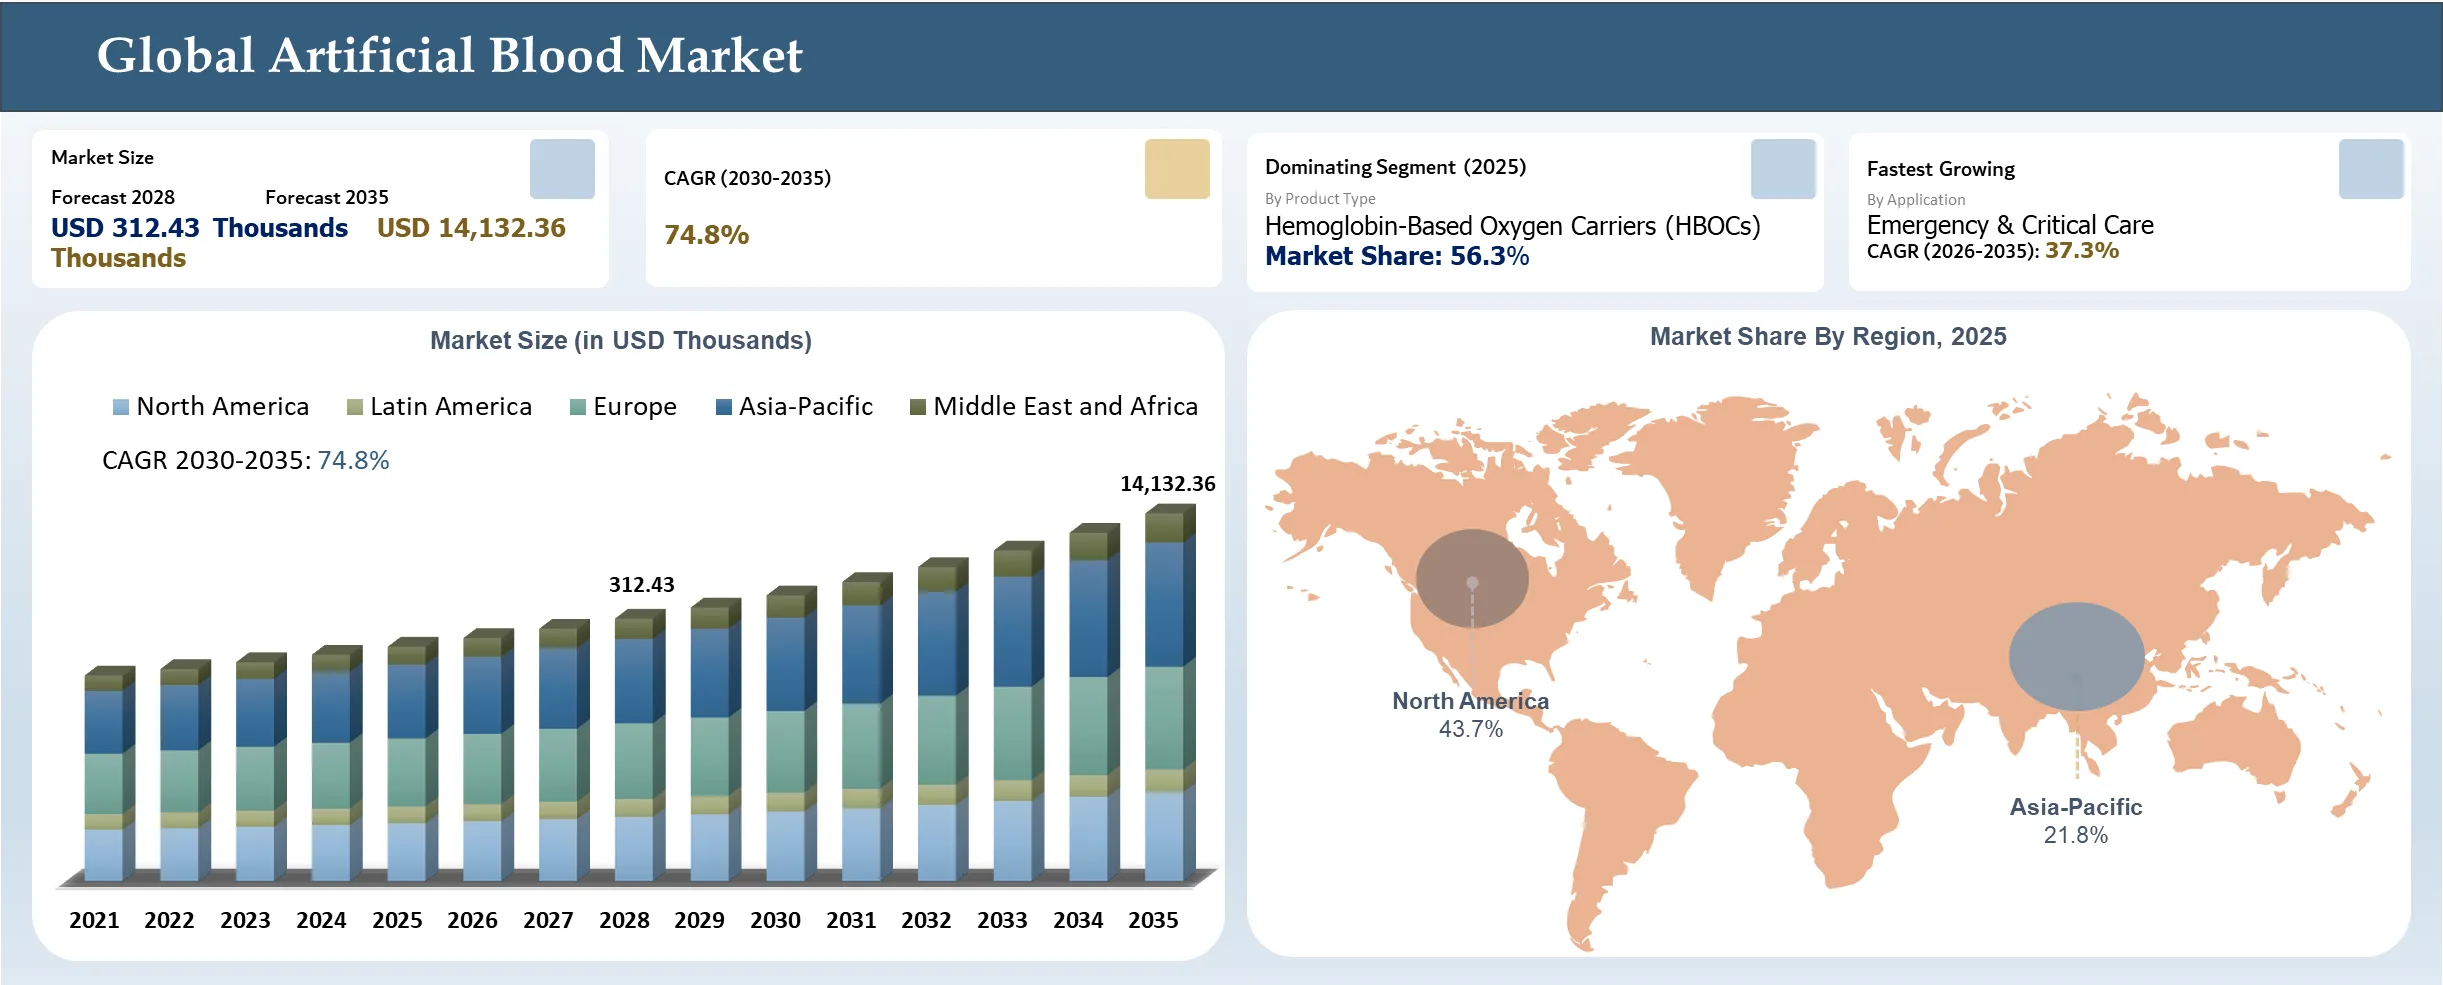
Contemporary advances have been focusing on shelf-stable and scalable blood substitutes that could help in bypassing the drawbacks of storage and logistics associated with conventional blood products. In May 2026, the Defense Advanced Research Projects Agency (DARPA) announced its RAPIID program for developing biosynthetic alternatives to oxygen carriers, plasma, and platelets through technologies at TRL/MRL 3-4 stage. The RAPIID program has been divided into two phases, which span over a period of 36 months in total. The first phase of the project takes one year and involves feasibility studies of preclinical and manufacturing, whereas Phase 2 lasts for two years and involves clinical trials, regulatory process, manufacturing scale-up, and commercialization.
White-Space Opportunities for Artificial Blood Market: Artificial RBCs and Universal Oxygen-Carrying Blood Substitutes
The artificial blood market is creating significant investment opportunities across artificial red blood cells, oxygen carriers, synthetic platelets, and shelf-stable blood surrogates, with the strongest investment concentration currently emerging around oxygen-carrying blood substitutes and whole-blood replacement platforms. A key opportunity is the U.S. DARPA USD 1.799993 million Phase II SBIR award to KaloCyte Inc. for production of GLP ErythroMer for IND-enabling animal studies.
ErythroMer is a universal artificial red blood cell substitute designed to reproduce the oxygen-carrying function of natural RBCs, and the funding is being used to scale manufacturing and produce a pilot GLP batch for toxicity studies, creating opportunities in artificial RBC manufacturing, hemoglobin encapsulation, scalable nanoparticle production, quality control, and regulatory preparation.
KaloCyte also reported USD 2.6 million raised as the first half of a USD 5 million seed equity round and the USD 1.8 million DARPA SBIR award in 2025, alongside a USD 250,000 BLUE KNIGHT QuickFire award and renewal of its DARPA FSHARP subcontract, making artificial RBC scale-up and shelf-stable oxygen transport one of the major identifiable investment areas.
The broader opportunity extends into universal oxygen carriers, where Bioxytran Inc. and the Heme Foundation are developing a UOC platform through a USD 10 million joint venture, with Bioxytran securing a GMP-quality source of camel hemoglobin to support oxygen-transport development.
Artificial Blood Market Key Takeaways
- North America represents the largest regional market, controlling a 43.7% market share in 2025. Asia-Pacific follows as the fastest-growing market, holding a 21.8% share of global artificial blood substitutes in 2025.
- Hemoglobin-Based Oxygen Carriers (HBOCs) lead the artificial blood market, holding a 56.3% share in 2025. Their dominance is driven by their capability to replicate oxygen transport without relying on donor blood availability.
- DARPA launched the RAPIID program in May 2026 to advance oxygen carriers, plasma, and platelets at TRL/MRL stages 3 to 4. The initiative is structured over a 36-month timeline, splitting into a 1-year feasibility phase and a 2-year clinical and commercialisation phase.
- KaloCyte received a USD 1.799993 million Phase II SBIR award from DARPA to manufacture GLP ErythroMer for IND studies. The company also raised USD 2.6 million in seed equity alongside securing a USD 250,000 BLUE KNIGHT QuickFire award.
Artificial Blood Market Industry Trends and Strategic Insight
- Shift from universal blood-replacement concepts toward indication-specific oxygen therapeutics is becoming a key development strategy, with artificial blood technologies increasingly designed for defined clinical needs such as acute resuscitation, organ preservation, and hypoxia rather than attempting to replicate every function of natural blood.
- Shelf-stable blood analogs are moving toward field-deployable trauma applications, with developers integrating oxygen carriers, platelet-like components, plasma substitutes, ruggedized packaging, and point-of-care diagnostics into broader resuscitation systems.
- Next-generation hemoglobin engineering is prioritizing safety over simple oxygen-carrying capacity, with research increasingly focused on controlling hemoglobin-related vasoconstriction, oxidative stress, inflammation, and organ toxicity.
- Regulatory strategy is being incorporated earlier into product development, with leading programs increasingly linking preclinical validation, clinical trials, FDA authorization pathways, manufacturing scale-up, and commercialization rather than treating regulatory approval as a final-stage activity.
- The market is shifting toward multifunctional blood analog platforms, combining oxygen delivery, volume replacement, hemostatic support, and other critical blood functions instead of relying exclusively on single-function oxygen carriers.
Artificial Blood Market Scope
| Metrics | Details | |
| 2028 Market Size | USD 312.43 Thousands | |
| 2035 Projected Market Size | USD 14,132.36 Thousands | |
| CAGR (2030-2035) | 74.8% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Product Type | Hemoglobin-Based Oxygen Carriers (HBOCs), Perfluorocarbon-Based Oxygen Carriers (PFCs) | |
| By Source | Human Hemoglobin, Animal Hemoglobin, Stem Cells, Synthetic Materials, Recombinant Hemoglobin, Others | |
| By Application | Anemia & Blood Loss, Surgical & Perioperative Care, Injuries & Trauma, Organ Transplantation, Emergency & Critical Care, Others | |
| By End-User | Hospitals, Military & Defense Healthcare, Organ Transplant Centers, Research Institutes, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland, Netherlands, Switzerland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia | |
| Latin America | Brazil, Argentina | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Artificial Blood Market Disruption Analysis
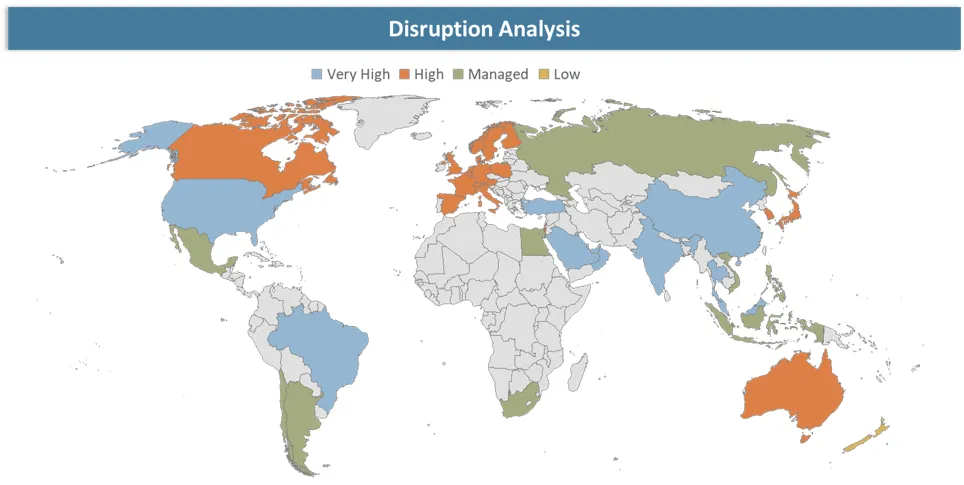
Shift Toward Shelf-Stable and Lab-Engineered Blood Substitutes Reshaping the Artificial Blood Market
The disruption in the artificial blood market is primarily associated with the rapid development of shelf-stable and engineered alternatives to donor-derived blood, particularly in situations where conventional transfusion is difficult to deliver. It leads to the creation of products that would be able to fulfil the specific roles of blood in terms of performing its functions, such as oxygen transfer, without using donor blood immediately.
Also, the development of haemoglobin vesicles (HbVs) as an artificial substitute for red blood cells indicates the evolution of purpose-driven blood substitutes toward human trials. In January 2026, according to PubMed, a study protocol published in BMJ Open, the Nara Medical University (NMU) HbV project seeks to enrol 16 healthy volunteers into four groups with IV administrations of 100 mL, 100 mL, 200 mL, and 400 mL. The study aims to evaluate safety using adverse events within 14 days and clinically important changes within 72 hours, as well as pharmacokinetics that follow NMU-HbV immediately post-infusion up to Day 4. The trial registration in Japan took place on January 27, 2025, with the first subject recruited on May 27, 2025.
Artificial Blood Market BCG Matrix: Company Evaluation
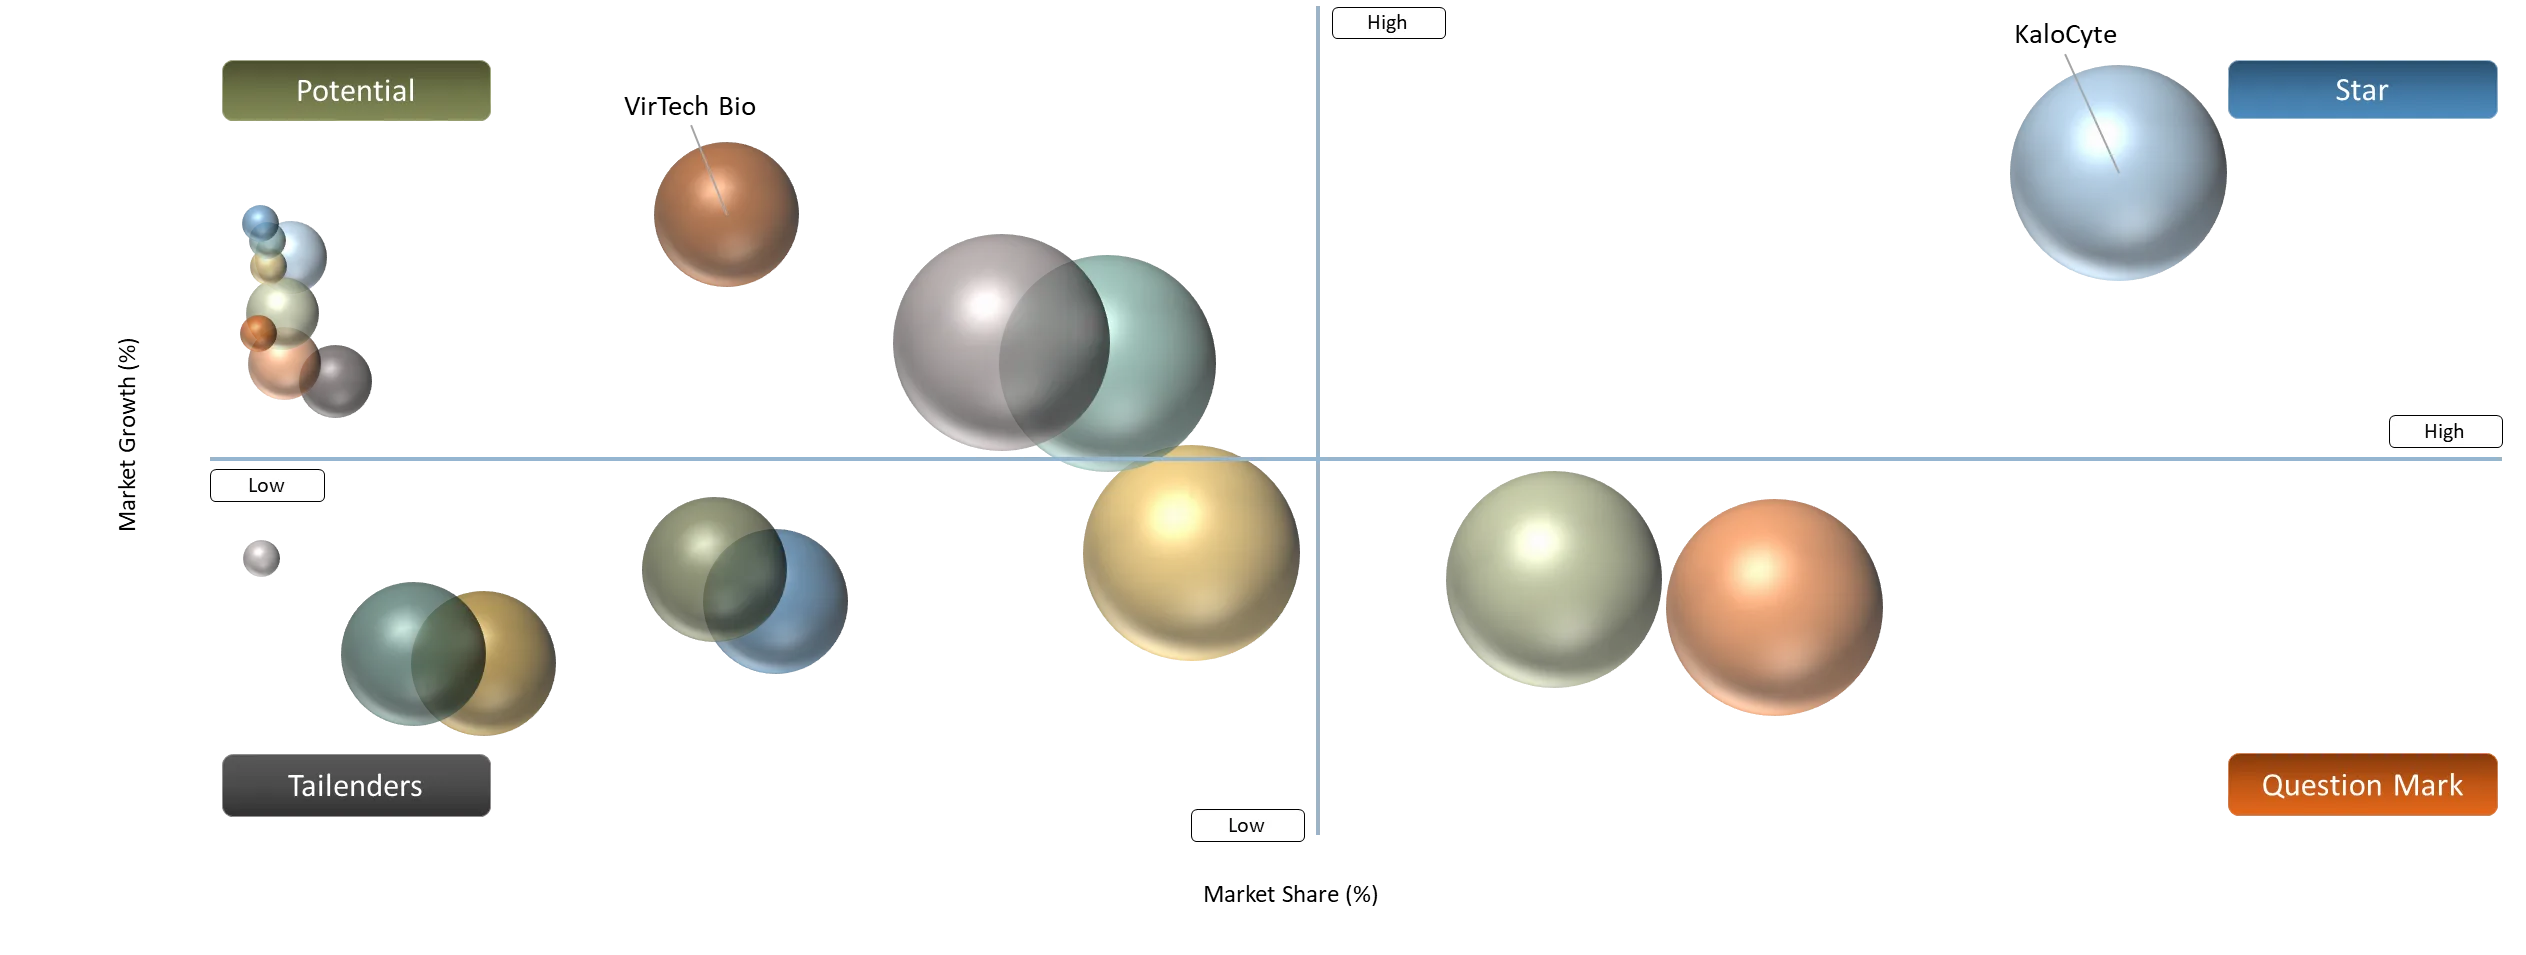
Stars include KaloCyte, which is developing ErythroMer, a bio-inspired artificial red blood cell designed to transport oxygen and potentially address urgent transfusion needs. Question Marks include HbO2 Therapeutics and Hemarina, as both companies have differentiated oxygen-carrying technologies but remain dependent on continued clinical development, regulatory progression, and broader adoption.
The Potential category includes VirTech Bio, whose artificial-blood technology could benefit from growing demand for engineered oxygen-carrying alternatives to donor blood. Tailenders include OXYVITA Inc., as its involvement in the artificial blood space is focused on a specialised haemoglobin-based oxygen-therapeutics approach and remains comparatively limited in market penetration.
Artificial Blood Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Rising Advancements in Hemoglobin Engineering and Artificial Red Blood Cell Research. | 24% | North America, Europe, Japan | Artificial RBCs, oxygen carriers, transfusion alternatives | Improves oxygen-carrying performance and safety, accelerating the transition from experimental blood substitutes toward clinically viable products. |
Growing Donor Blood Shortages and Persistent Gaps in Emergency Transfusion Availability. | 22% | North America, Europe, Asia-Pacific | Emergency transfusion, trauma care, disaster response | Strengthens the need for donor-independent blood substitutes and creates demand for products that can provide rapid blood availability when conventional supplies are constrained. |
Increasing Demand for Shelf-Stable Oxygen Carriers in Trauma and Military Medicine. | 21% | North America, Europe, military and remote-care settings | Battlefield medicine, hemorrhagic shock, emergency trauma care | Shifts product development toward portable and longer-storage blood substitutes that can be deployed without conventional blood-bank infrastructure. |
Growing investment in biotechnology and regenerative medicine is accelerating engineered blood substitutes. | 18% | North America, Europe, Japan, South Korea | Lab-grown RBCs, engineered blood components, regenerative medicine | Expands the innovation pipeline and supports development of scalable, engineered blood platforms, while increasing competition around clinical validation and manufacturing readiness. |
Rising Advancements in Hemoglobin Engineering and Artificial Red Blood Cell Research
Artificial blood development is progressing from first-generation cell-free hemoglobin toward precision-engineered oxygen carriers designed to reduce heme loss, oxidation, nitric oxide scavenging and circulation instability. In 2025, Khan et al. reported recombinant β-F41K hemoglobin with approximately 3-4-fold lower heme dissociation than wild-type rHb0.1, while maintaining oxygen affinity suitable for physiological gas transport. Building on these molecular-level improvements, research is increasingly shifting toward encapsulated and biomimetic artificial red blood cells that isolate hemoglobin from direct vascular exposure.
In 2026, Sakai et al. described the NMU-HbV Phase Ib program in Japan involving 16 healthy volunteers across four cohorts, with planned dose escalation from 100 mL to 400 mL, advancing hemoglobin-vesicle technology toward clinically relevant transfusion volumes. Collectively, these developments indicate a clear shift from simply reproducing oxygen carriage toward engineering safer hemoglobin molecules, protecting them within biomimetic structures and developing shelf-stable, scalable products.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Safety Concerns Around Vasoconstriction, Oxidative Toxicity and OrganLevel Adverse Effects. | 27% | Clinical safety and patient outcomes | Oxygen delivery, trauma care, emergency transfusion | Increases clinical-development risk and requires improved molecular engineering, toxicity testing, and long-term safety validation before broader adoption. |
Stringent Clinical and Regulatory Requirements for Demonstrating Survival and Safety Benefits. | 24% | Regulatory approval and commercialization | Clinical transfusion alternatives, trauma and hemorrhagic shock | Extends development timelines and increases R&D costs, making regulatory strategy and robust clinical evidence critical for market entry. |
Limited clinical validation and regulatory approvals are slowing the commercialization and widespread adoption of artificial blood products. | 22% | Commercial adoption and market access | Hospitals, emergency medicine, surgical transfusion | Limits physician confidence and institutional procurement while keeping many technologies in development-stage markets rather than routine clinical use. |
Shortcomings in oxygen-carrying performance and circulation stability remain technical challenges for several artificial blood technologies. | 19% | Product performance and technological scalability | Artificial RBCs, hemoglobin-based oxygen carriers, oxygen therapeutics | Drives investment toward engineered hemoglobin, encapsulated oxygen carriers, and improved circulation stability to achieve performance closer to natural RBCs. |
Safety Concerns Around Vasoconstriction, Oxidative Toxicity and Organ-Level Adverse Effects
Safety remains the central constraint on hemoglobin-based oxygen carriers (HBOCs) commercialisation because cell-free hemoglobin can scavenge nitric oxide, promote vasoconstriction, form methemoglobin and release free heme, creating interconnected cardiovascular, renal and inflammatory risks. In 2025, Jahr et al. reinforced these mechanisms as critical determinants of clinical tolerability. Building on this mechanistic concern, Estep in 2025 evaluated five later-stage HBOCs and found myocardial-infarction incidence positively associated with dose, molecular size, intravascular half-life, systemic exposure and oxidation kinetics, showing that prolonged circulation can amplify risk when redox stability is inadequate.
The findings are directly shaping product design. Developers are increasingly moving toward encapsulated and engineered hemoglobin systems, with 2025 research highlighting 100 to 200 nm hemoglobin vesicles as a way to reduce renal filtration and direct vascular exposure while preserving oxygen delivery. Even with these design improvements, clinical translation remains safety-gated. Japan’s 2026 NMU-HbV Phase Ib program plans 16 healthy volunteers, escalating doses from 100 to 400 mL with 14-day adverse-event monitoring, underscoring that organ-level tolerability remains a decisive commercialisation hurdle.
Artificial Blood Market Segment Analysis
The global artificial blood market is segmented based on product type, source, application, end-user, and region.
Hemoglobin-Based Oxygen Carriers (HBOCs) Leading the Artificial Blood Market Through Established Oxygen-Delivery Capabilities
The hemoglobin-based oxygen carriers (HBOCs) segment dominates the artificial blood market, with a market share of 56.3% in 2025, due to their capacity to mimic the fundamental process of oxygen transport by red blood cells, along with overcoming certain disadvantages of traditional blood donated by donors such as blood group compatibility, blood storage, and scarcity of supply. The effectiveness in situations such as trauma, surgery-related blood loss, and emergency transfusions keeps the development of hemoglobin substitutes active.
The current scientific literature shows increased efforts aimed at the improvement of the biochemical and biophysical properties of HBOCs in order to address safety concerns related to previous generations. In January 2025, according to Wiley, a transfusion study analysing the properties of clinically tested HBOCs showed significant differences in terms of molecular weight and oxygen affinity, where Hemopure demonstrated a molecular weight of 130-500 kDa and p50 of 34.28 ± 0.77 mmHg, while Sanguinate possessed a molecular weight of 120 kDa and p50 of 9.56 ± 0.28 mmHg. In addition, the study revealed nitric oxide scavenging, oxidative stress, methemoglobinemia, and heme loss to be among the primary mechanisms involved in HBOC toxicity. Hence, new methods such as PEGylation, polymerization, encapsulation, and genetic modification of hemoglobin are under development to address stability of circulation, oxygen transport, and safety.
Artificial Blood Market Geographical Penetration
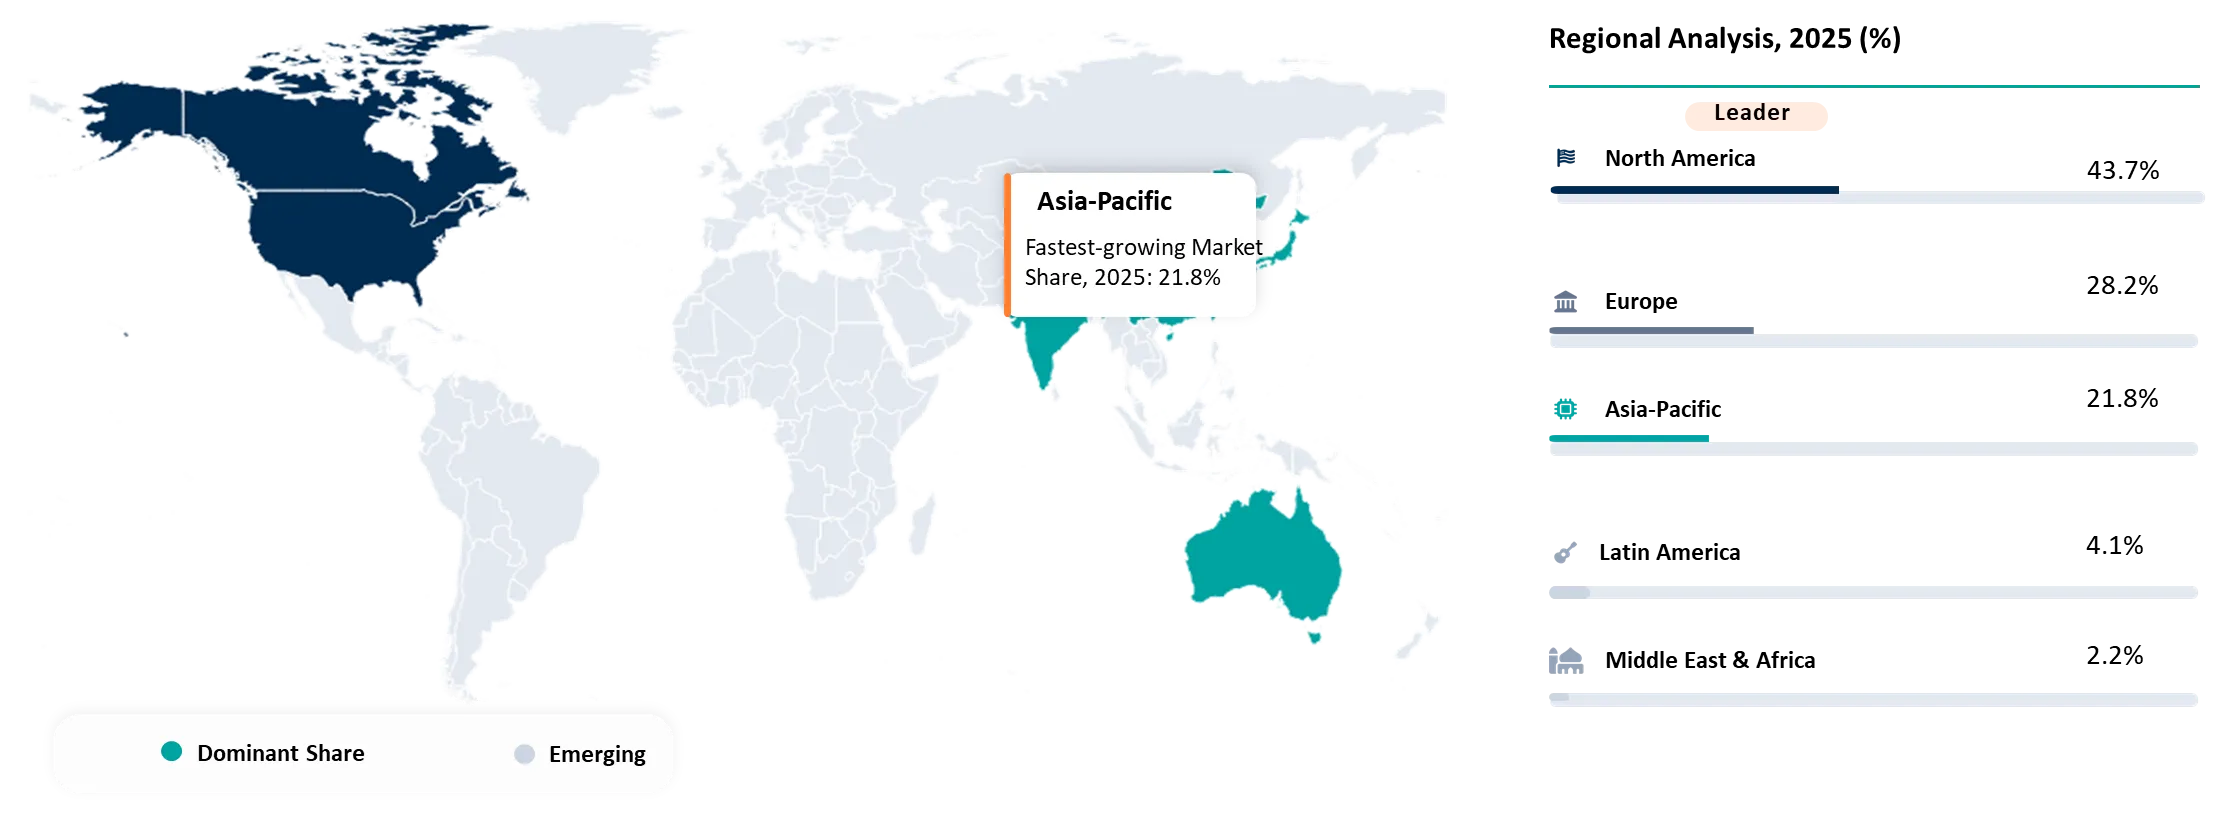
North America Leading the Artificial Blood Market Through Defense-Funded Innovation and Clinical-Stage Development
North America continues to dominate the artificial blood market, with a market share of 43.7% in 2025, because of its well-developed biotech environment, sophisticated systems of trauma care, medically oriented defence research, and the presence of many developers of artificial hemoglobin and other oxygen therapeutic products. North America is the leading regional market. In particular, the needs of the U.S. Army in blood substitutes and research capacities, together with a developed biotech environment, have helped the region become a leader.
Persistent U.S. Blood Supply Shortages Creating Demand for Artificial Blood Alternatives. In January 2026, the American Red Cross reported that it supplies about 40% of U.S. blood and requires more than 13,000 blood and 3,000 platelet donations daily. Blood inventory had also declined by approximately 35% over the preceding month, reinforcing demand for alternative oxygen-carrying products during supply shortages.
U.S. Artificial Blood Market Trends
The U.S. holds a dominant position in the artificial blood market, due to the presence of a very efficient biotech sector, a well-established trauma care system, and robust governmental backing for research on blood substitutes. It was a consolidated pipeline of artificial red blood cells and oxygen-carrying agents available in the nation, backed by entities like DARPA, NIH, and the U.S. Department of Defence that are promoting the development of shelf-stable and deployable substitutes for traditional donor blood.
Military and trauma systems are redefining transfusion requirements around prolonged field care rather than hospital-based blood access. In 2026, U.S. Army analysis estimated that 15 to 20% of wounded personnel may require resuscitation, meaning high-casualty operations could rapidly outstrip refrigerated whole-blood inventories. The operational constraint is shifting requirements toward oxygen-carrying products that can be prepositioned, transported without conventional cold-chain dependence and administered near the point of injury. In April 2026, U.S. military analysis identified lyophilised blood products as critical bridge therapies when whole blood is unavailable.
Canada Artificial Blood Market Outlook
Canada is one of the major countries in the artificial blood market, due to its unique biotechnology capabilities, scientific research system in life sciences, and research in cell-free oxygen carriers. Research organisations and biotechnology firms in Canada have been working on the development of oxygen carriers that can help deal with some shortcomings of donor blood, especially when it comes to universal oxygen carrying and tissue preservation. Having organisations such as HEMARINA Canada, CRCHUM, Mitacs, and CQDM has made Canada an important player in research on marine hemoglobin technology.
Canada is emerging as a development hub for cell-free oxygen-carrier technologies, supported by collaborative research and funding initiatives in advanced blood-substitute applications. In April 2024, CQDM, HEMARINA Canada, Mitacs, and CRCHUM launched a USD 874,478 collaborative project to evaluate HEMARINA’s marine-derived M101 oxygen carrier. M101 can carry approximately 40 times more oxygen than human haemoglobin and is being evaluated for tumour oxygenation and tissue preservation. The project supports the development of universal, cell-free oxygen-carrier technologies relevant to future blood-substitute applications.
Asia-Pacific Expanding Artificial Blood Development Through Clinical Research and Advanced Oxygen-Carrier Technologies
The Asia-Pacific is the fastest-growing region in the artificial blood market due to increasing biotechnology research, expanding clinical-development capabilities, and growing efforts to develop blood substitutes for emergency transfusion and trauma care. Asia-Pacific accounted for 21.8% of the global artificial blood substitutes market in 2025, supported by research activity across Japan, China, South Korea, and other Asian markets.
South Korea is strengthening its position in artificial blood development through advances in cultured red blood cell technologies and strategic manufacturing collaborations.
In April 2025, ArtBlood Inc., a South Korean-based biotechnology company specialising in in vitro blood production, signed an MOU with Expression Manufacturing LLC, the U.S.-based cGMP manufacturing subsidiary of Expression Therapeutics Inc., to advance clinical development and large-scale production of ArtBlood’s BioBlood cultured red blood cells. The collaboration combines ArtBlood’s expertise in RBC proliferation, differentiation, purification, and quality control with Expression Manufacturing’s cGMP cell-therapy manufacturing capabilities, supporting scalable production and commercialisation of artificial blood.
Japan Artificial Blood Market Trends
Japan is emerging as a leading country in the artificial blood market owing to its established biomedical research capabilities, specialised expertise in blood-transfusion medicine, and continued development of hemoglobin vesicles (HbVs) as red blood cell substitutes. The country’s research ecosystem, led by institutions such as Nara Medical University and Hokkaido University, is advancing artificial blood technologies designed to provide oxygen transport during emergency transfusion situations.
Japan is advancing next-generation blood-substitute technologies through the clinical development of iPSC-derived platelet products. In August 2026, Megakaryon Corporation, a Japan-based regenerative medicine biotechnology company, reported the world's first clinical evidence of iPSC-derived platelet circulation in humans using its MEG-002 product. In an exploratory clinical trial involving one patient with aplastic anaemia, MEG-002 was administered without reported adverse events, and the iPSC-derived platelets were detected circulating in the bloodstream 2-6 hours after infusion, with the corrected count increment exceeding the transfusion-efficacy threshold.
Artificial Blood Market Competitive Landscape
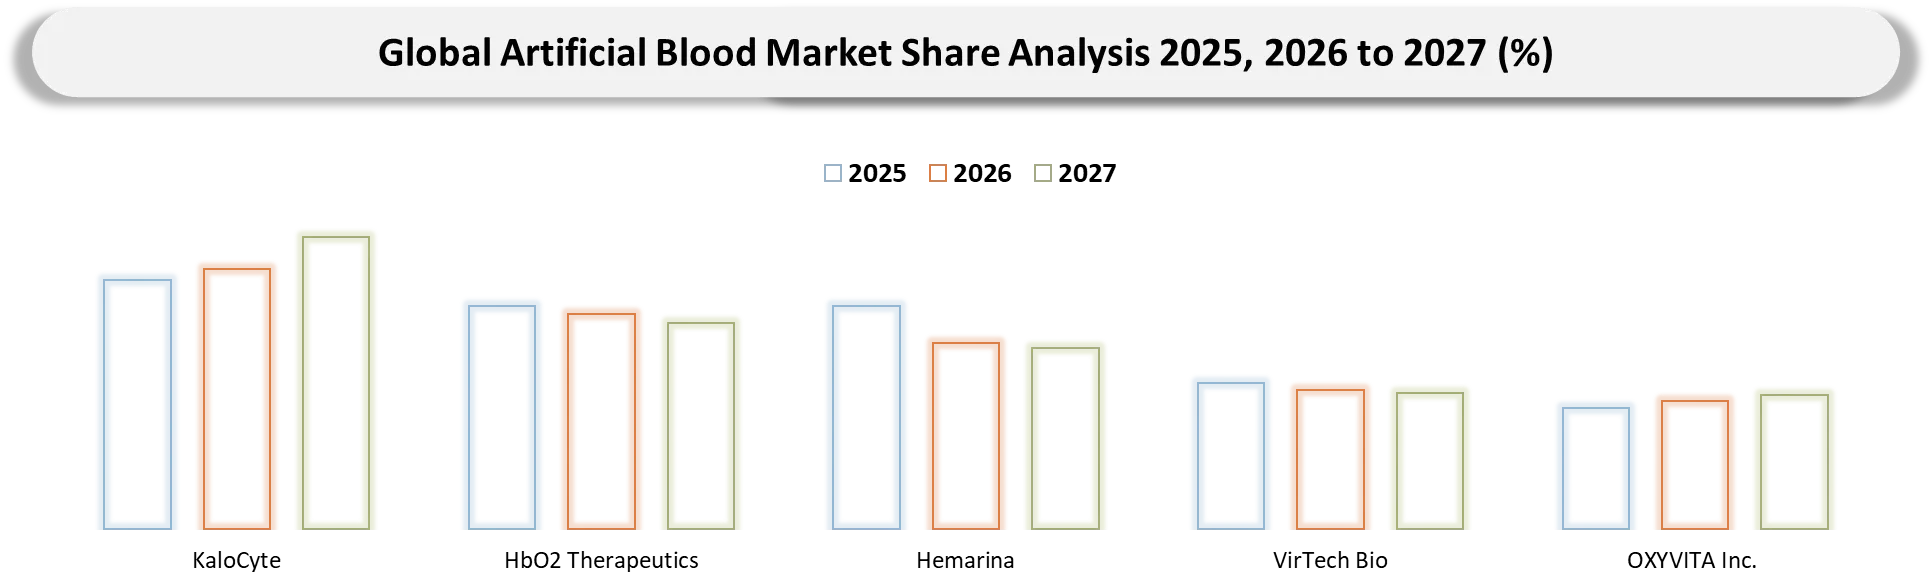
- The artificial blood market is characterised by a specialised group of biotechnology companies pursuing different approaches to oxygen transport and blood-substitute development. KaloCyte focuses on ErythroMer, an artificial red blood cell designed to provide oxygen transport in a shelf-stable format; HbO2 Therapeutics develops Hemopure, a hemoglobin-based oxygen carrier; Hemarina specialises in M101, a marine-derived extracellular hemoglobin; VirTech Bio is developing OxyBridge, a human-derived hemoglobin-based oxygen carrier; while OXYVITA Inc. focuses on polymerized hemoglobin technologies. It is creating a technology-driven landscape where oxygen-delivery performance, safety, circulation stability, shelf life, clinical validation, and regulatory progress define competitiveness.
- Key players include KaloCyte (United States), HbO2 Therapeutics (United States), Hemarina (France), VirTech Bio (United States), and OXYVITA Inc. (United States).
Key Developments
- August 2026: ArtBlood Inc., a South Korean biotechnology company specialising in cultured/artificial blood, partnered with Sartorius AG, a Germany-based life-science and bioprocessing technology company, to jointly develop a specialised artificial blood culture medium for producing cultured red blood cells.
- October 2025: Inha University, a South Korean research university, signed a KRW 830 million (USD 0.57 million) contract to accelerate the development of next-generation artificial blood aimed at overcoming transfusion limitations in war and emergencies.
- August 2025: DewCell Biotherapeutics, a South Korean-based biotechnology company specialising in artificial platelet development, successfully produced artificial platelets using a 50-litre bioreactor, reported as the world’s first production at this scale.
- August 2026: Renerval Therapeutics (Shanghai) Co., Ltd., a China-based biotechnology and cell-therapy company, secured RMB 150 million (USD 21 million) in Pre-A financing from Yifeng Capital, Minjin Investment, and other industry institutions, with existing investor Shunwei Capital also participating.
Key Procurement Priorities and Buyer Evaluation Criteria
- Organisations investing in the artificial blood market are increasingly selecting suppliers based on their ability to provide safe, clinically validated oxygen-carrying solutions that can deliver reliable oxygen transport, maintain physiological compatibility, and support emergency transfusion requirements. Safety, efficacy, biocompatibility, and consistency of oxygen delivery are particularly important because artificial blood technologies must address the limitations that have affected earlier oxygen-carrier products.
- The decision-making process for procurement is increasingly being influenced by the need for shelf-stable and readily deployable blood substitutes, particularly for trauma care, military medicine, emergency response, remote healthcare, and situations where conventional donor blood is difficult to store or transport. Buyers therefore prioritise products that reduce dependence on cold-chain logistics and donor availability while maintaining clinically relevant performance.
- Buyers consider factors such as oxygen-carrying and oxygen-release performance, safety profile, circulation stability, immunological compatibility, toxicity risk, shelf life, storage requirements, sterility, and clinical evidence when evaluating artificial blood suppliers. Regulatory status and the quality of preclinical and clinical validation are also critical because the market remains highly dependent on demonstrating safety and efficacy before wider clinical adoption.
Why Choose DataM?
- Technological Innovations: Explores advancements in artificial blood technologies including hemoglobin-based oxygen carriers (HBOCs), perfluorocarbon-based oxygen carriers, hemoglobin vesicles, artificial red blood cells, and engineered oxygen carriers, highlighting innovations aimed at improving oxygen delivery, safety, circulation stability, and shelf life.
- Product Performance & Market Positioning: Evaluates how different players develop artificial blood solutions based on oxygen-carrying capacity, oxygen-release characteristics, biocompatibility, toxicity profile, storage stability, and clinical performance, highlighting how leading companies differentiate through safer and more deployable blood-substitute technologies.
- Real-World Evidence: Highlights the development and clinical evaluation of artificial blood technologies for trauma care, hemorrhagic shock, emergency transfusion, surgery, military medicine, organ preservation, and other applications where rapid access to conventional donor blood may be limited.
- Market Updates & Industry Changes: Tracks key developments such as clinical trials, regulatory progress, research collaborations, government-funded programs, technology launches, manufacturing initiatives, and advances in artificial red blood cells and shelf-stable oxygen carriers across North America, Europe, and Asia-Pacific.
- Competitive Strategies: Analyses how leading companies strengthen their positions through technology development, clinical validation, strategic partnerships, government-funded research, intellectual-property development, and manufacturing scale-up to advance artificial blood solutions toward broader clinical adoption.
- Pricing & Market Access: Examines cost considerations associated with research, clinical development, manufacturing, storage, and deployment of artificial blood products, while assessing market-access factors such as regulatory approval, clinical evidence, healthcare procurement requirements, and distribution capabilities.
- Market Entry & Expansion: Identifies growth opportunities driven by blood shortages, trauma and emergency medicine, military applications, remote healthcare, and demand for shelf-stable transfusion alternatives, while outlining strategies such as clinical partnerships, regulatory advancement, manufacturing expansion, and collaboration with healthcare and defence organisations.
Target Audience 2026
- Artificial Blood Technology Developers
- Biotechnology & Life Sciences Companies
- Pharmaceutical & Medical Technology Companies
- Hospitals & Healthcare Providers
- Military & Defence Healthcare Organisations
- Blood Banks & Transfusion Organizations
- Research Institutes & Academic Organizations




























































