


Aluminium Market Size
The global aluminum market size reached US$ 204.56 billion in 2025 and is expected to reach US$ 299.46 billion by 2033, growing with a CAGR of 4.51% during the forecast period 2026–2033.
Aluminum is a metal of strategic significance to nearly all sectors of critical importance in modern life. Key industry segments like transportation, aerospace, aviation, defense, and building & construction, among others, are already using aluminum as a crucial raw material.
High strength-to-weight ratio, supreme formability, corrosion resistance, high ductility and conductivity, stylish finish and infinite recyclability are some USPs that have made aluminum a metal of choice for various applications.
Aluminum use in the auto sector has been accelerating because it offers the safest, fastest, most environment-friendly and cost-effective way to improve performance, boost fuel economy, and lower emissions while maintaining or improving safety and durability.
By region, Asia-Pacific is expected to dominate the global aluminum market as China continues to be the largest Aluminum producer. China's government setting its eyes on higher Aluminum targets in terms of fiscal, economic and all-round growth will boost the market growth.
Aluminum Market Trends
A trend in the aluminum market is the increasing emphasis on recycling, which has become a crucial aspect of the industry. Recycling aluminum requires only about 5% of the energy needed to produce primary aluminum, making it both economically and environmentally advantageous. This shift towards recycling is driven by the metal's infinite recyclability without loss of properties, aligning with global sustainability goals and reducing the industry's carbon footprint.
Aluminium Market Scope
| Metrics | Details |
| By Product | Pure Aluminum, Alloy Aluminum |
| By Form | Powder, Extrusions, Castings, Forgings and Others |
| By Application | Pigments, Foils, Wires, Sheets and Plates, Rod and Bars and Others |
| By End-User | Packaging, Automotive & Transportation, Building & Construction, Electrical & Electronics, Consumer Durables and Others |
| By Region | North America, South America, Europe, Asia-Pacific and Middle East and Africa |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth |
Explore the Future of the Aluminum Market
Get a comprehensive sample report covering Aluminum Market trends, production and consumption dynamics, technological advancements, competitive landscape, application insights, and growth opportunities. Request your sample today to understand the key factors shaping the future of the global aluminum industry across automotive, construction, packaging, aerospace, and other end-use sectors.Request Sample Report Today!
Aluminium Market Dynamics
Government-Led Infrastructure Expansion Accelerating Aluminum Consumption
Government-backed infrastructure investments are driving substantial growth in aluminum demand. In the US, the Bipartisan Infrastructure Law allocates over US$ 1.2 trillion toward transportation, energy, and broadband projects, many of which require large volumes of aluminum for construction and electrical applications. Similarly, India’s National Infrastructure Pipeline involves an estimated investment of US$ 1.4 trillion through 2025, promoting aluminum use in sectors like railways, power transmission, and smart cities. These large-scale initiatives underscore aluminum's critical role in modern infrastructure development.
Energy-Intensive Smelting Process Contributing to High Production Costs and Emissions
The aluminum smelting process is highly energy-intensive, with energy costs comprising approximately one-third of total production expenses. This substantial energy consumption contributes to elevated production costs and significant greenhouse gas emissions. Notably, the industry accounts for about 2% of global greenhouse gas emissions, equating to roughly US$ 1.1 billion tons of CO₂ annually.
Aluminium Market Segmentation Analysis
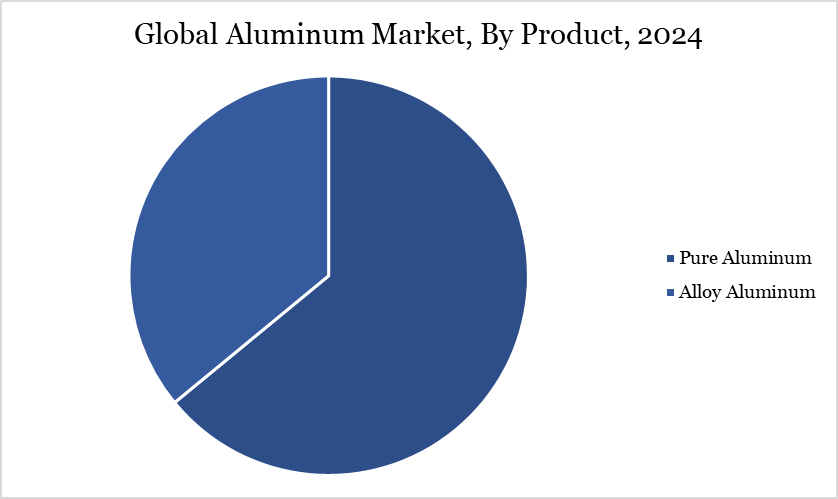
The global aluminum market is segmented based on product, form, application, end-user, and region.
Aluminum Alloys Fueling Growth in Automotive and Construction Sectors
Aluminum alloys are playing an increasingly critical role in the automotive industry, particularly in India. According to the Indian Ministry of Mines, the country produced over 4.1 million tons of primary aluminum in 2023, representing around 6% of the global output. A significant portion of this aluminum is used in the production of alloy wheels and lightweight vehicle components, aligned with the government's push for electric mobility and fuel efficiency standards under FAME II and BS-VI regulations.
In the construction sector, aluminum alloys are being widely adopted due to their high strength-to-weight ratio and corrosion resistance. The US Geological Survey reported that domestic primary aluminum production in the US was approximately 880,000 metric tons in 2023, with major use in building facades, window frames, and other structural components. This demand is supported by public infrastructure projects and energy-efficient building mandates at the federal and state levels.
Aluminium Market Geographical Share
Rising Infrastructure and Industrialization Driving Aluminum Demand in Asia-Pacific
The Asia-Pacific region, particularly China, plays a pivotal role in the global aluminum market. In 2023, China's primary aluminum production reached a record 41.59 million metric tons, marking a 3.7% increase from the previous year. This growth, however, represents the third consecutive year of deceleration, influenced by factors such as power shortages in southwestern regions like Yunnan. These shortages were due to insufficient hydropower supply, leading to production constraints.
In India, government initiatives have significantly impacted aluminum demand, especially in the construction sector. The 2024-25 budget allocated US$ 32 billion for rural development, aiming to enhance infrastructure and housing in rural areas. This substantial investment is expected to boost demand for construction materials, including aluminum, as the country focuses on improving rural infrastructure.
Impact of US Tariffs
The imposition of US tariffs on aluminum imports has significantly influenced the global aluminum market, affecting trade flows, pricing, and production dynamics. In response to the 25% tariff imposed by the US on aluminum imports, key suppliers have redirected their exports to alternative markets. Canada, which accounted for approximately 85% of US aluminum imports in 2024, began channeling more aluminum to Europe to mitigate the impact of US tariffs.
The shift has led to increased aluminum supply in European markets, exerting downward pressure on prices there. Specifically, the Rotterdam P1020A duty-paid premium declined from US$ 370 per ton in early January to US$ 320–330 per ton, reflecting this increased supply. Domestically, the tariffs have contributed to a rise in US aluminum prices.
The Platts US Midwest Transaction premium, a benchmark for aluminum pricing, increased from 18.8 cents per pound at the end of 2024 to 23.8 cents per pound by mid-January 2025. This escalation reflects the market's anticipation of constrained supply due to the tariffs.
Aluminium Market Major Global Players
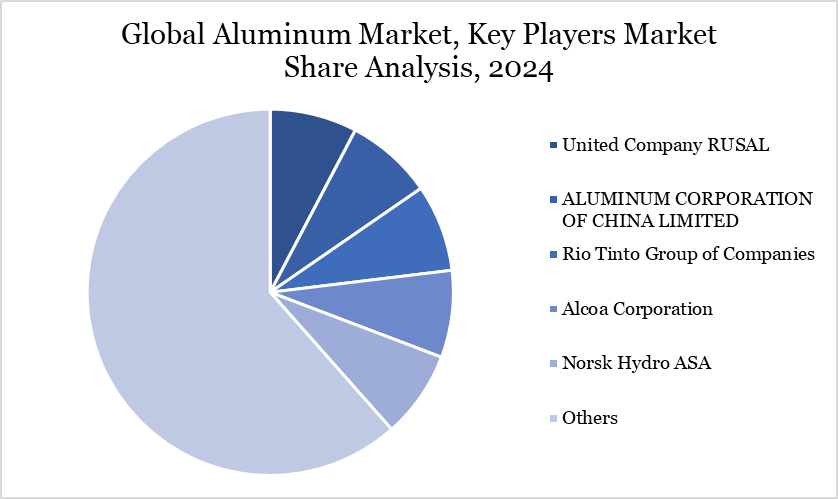
The major global players in the market include United Company RUSAL, Aluminum Corporation of China Limited, Rio Tinto Group of Companies, Alcoa Corporation, Norsk Hydro ASA, Emirates Global Aluminium PJSC, Vedanta Limited, China Hongqiao Group Limited, Century Aluminum Company, and Kaiser Aluminum Corporation, National Aluminum Company Limited, Aluminum Bahrain and Kaiser Aluminum Corporation"
Aluminium Market Recent Developments
- August 2026 – Rio Tinto secures long-term renewable power for Tomago Aluminium
Rio Tinto supported a new agreement securing the long-term future of Australia’s Tomago Aluminium smelter through 2038. The agreement includes a 10-year power purchase agreement, with electricity sourced entirely from renewable sources from 2033, alongside A$1.1 billion of planned investment, including A$100 million for decarbonization initiatives. - July 2026 – Vedanta Aluminium achieves record production
Vedanta Aluminium reported record quarterly aluminium production of 632 KT in Q1 FY27, supported by higher capacity utilization and operational efficiency. Value-added aluminium products also reached a record 389 KT, highlighting growing demand for higher-value aluminium applications. - July 2026 – Norsk Hydro advances European aluminium capacity and recycling
Hydro announced plans to restart 75,000 tonnes of aluminium capacity at the Slovalco smelter in Slovakia during the second half of 2026. The company also reported stronger recycling performance and continued investments in low-carbon aluminium, reflecting the industry's shift toward circular and lower-emission production. - July 2026 – Alcoa strengthens global aluminium portfolio
Alcoa entered an agreement to acquire South32’s interests in bauxite, alumina and aluminium assets across Australia, Brazil and South Africa for approximately $4.1 billion upfront. The transaction is intended to strengthen Alcoa’s upstream aluminium portfolio and improve global competitiveness. - July 2026 – Alcoa advances gallium production from aluminium operations
Alcoa and partners from Australia, Japan and the U.S. reached a final investment decision for a gallium production plant at the Wagerup refinery in Australia. The development highlights increasing efforts to recover critical minerals from aluminium-related processing streams. - May 2026 – Hindalco records strong aluminium business performance
Hindalco reported record FY26 results, with aluminium upstream EBITDA reaching ₹18,884 crore, up 16%, while downstream EBITDA increased 55%. The company also continued progress on its Bay Minette project, with cold-mill commissioning underway and completion expected in the second half of 2026. - April 2026 – Alcoa increases aluminium production through smelter restarts
Alcoa’s aluminium production increased 5% sequentially in Q2 2026 to 636,000 metric tons, supported by the restart of the San Ciprián smelter in Spain and continued restarts at Alumar in Brazil, Lista in Norway and Portland in Australia. - March 2026 – Hydro manages Middle East supply disruptions
Hydro announced controlled production curtailments at Qatalum in Qatar following reduced gas availability, with the smelter operating at around 60% capacity. The disruption highlighted the aluminium industry's exposure to energy and geopolitical risks across major producing regions. - February 2026 – NALCO launches IA91 aluminium alloy ingot
NALCO introduced its IA91-grade aluminium alloy ingot, expanding its portfolio of specialized aluminium products for downstream industrial applications. The development reflects India's increasing focus on domestic production of higher-value aluminium alloys. - July 2026 – Aluminium supply chains increasingly focus on critical-mineral recovery
Enervoxa announced plans for a potential $250–350 million rare-earth processing project in India using red mud, a by-product of aluminium production. The initiative could create an additional value stream from aluminium waste while supporting domestic critical-mineral processing capabilities.
Why Choose DataM?
- Data-Driven Insights: Dive into detailed analyses with granular insights such as pricing, market shares and value chain evaluations, enriched by interviews with industry leaders and disruptors.
- Post-Purchase Support and Expert Analyst Consultations: As a valued client, gain direct access to our expert analysts for personalized advice and strategic guidance, tailored to your specific needs and challenges.
- White Papers and Case Studies: Benefit quarterly from our in-depth studies related to your purchased titles, tailored to refine your operational and marketing strategies for maximum impact.
- Annual Updates on Purchased Reports: As an existing customer, enjoy the privilege of annual updates to your reports, ensuring you stay abreast of the latest market insights and technological advancements. Terms and conditions apply.
- Specialized Focus on Emerging Markets: DataM differentiates itself by delivering in-depth, specialized insights specifically for emerging markets, rather than offering generalized geographic overviews. This approach equips our clients with a nuanced understanding and actionable intelligence that are essential for navigating and succeeding in high-growth regions.
- Value of DataM Reports: Our reports offer specialized insights tailored to the latest trends and specific business inquiries. This personalized approach provides a deeper, strategic perspective, ensuring you receive the precise information necessary to make informed decisions. These insights complement and go beyond what is typically available in generic databases.
Target Audience
- Manufacturers/ Buyers
- Industry Investors/Investment Bankers
- Research Professionals
- Emerging Companies



























































