


Global Spinocerebellar Ataxia Market Size and Forecast
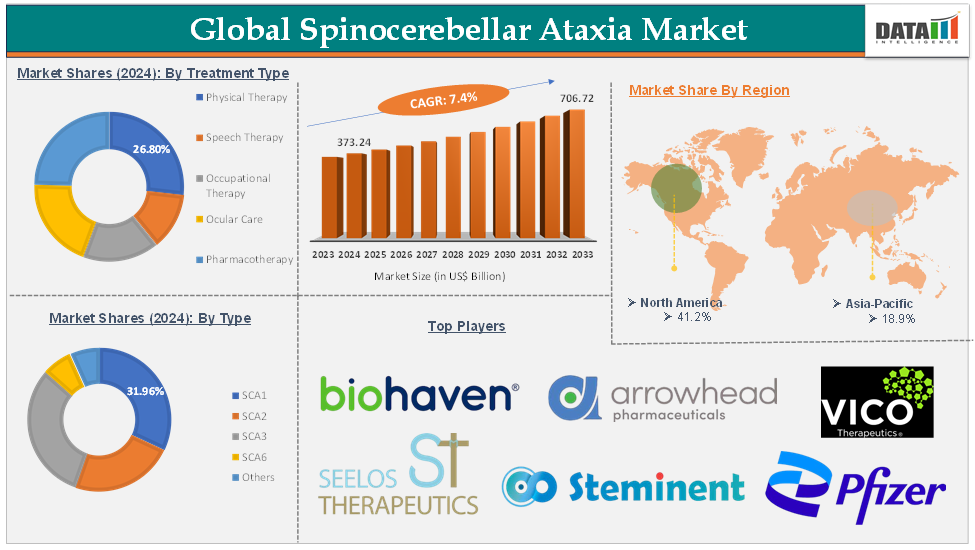
The global spinocerebellar ataxia market was valued at US$ 347.52 Million in 2023. The market size reached US$ 373.24 Million in 2024 and is expected to reach US$ 706.72 Million by 2033, growing at a CAGR of 7.4% during the forecast period 2025-2033.
Spinocerebellar ataxia (SCA), a subset of cerebellar ataxia, refers to a group of rare inherited neurodegenerative disorders, resulting in loss of voluntary muscle movements, coordination, and balance. This is caused by progressive damage mainly to the cerebellum and spinal cord. There are nearly 40 types of SCA, classified based on the type of genes involved. The most common types include SCA1, SCA2, SCA3, and SCA6.
SCA2 is one of the conditions in which the gene involved is ATXN2, which expresses the protein Ataxin 2. The clinical manifestations include slow saccadic eye movements, hypotonia, hyporeflexia, dysarthria, and nystagmus. The prevalence of SCA2 is 1 to 2 in 100,000 people, and it is twice as common as SCA1.
The global spinocerebellar ataxia (SCA) market is witnessing significant growth, driven by increasing research activities, better diagnostic tools, and a rising focus on rare neurological diseases. As more cases are identified and awareness spreads among healthcare professionals and the public, the demand for effective treatments and management strategies continues to rise.
One of the primary drivers of this market is the advancement in targeted therapies, particularly those that address the genetic causes of SCA. Early diagnosis and the adoption of advanced genetic testing are also fueling market expansion. Rising disease awareness among both healthcare providers and patients is another crucial driver.
Opportunities in the market are expanding with the potential approval of first-in-class, disease-modifying drugs. The introduction of such therapies would not only transform the treatment landscape but also encourage further innovation and investment in SCA research. Emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East, offer significant growth potential. As healthcare infrastructure improves and awareness increases in these regions, more patients will have access to diagnosis and treatment.
Global Spinocerebellar Ataxia Market Executive Summary
Global Spinocerebellar Ataxia Market Key Takeaways
- The SCA market is transitioning from primarily symptomatic management toward disease-modifying therapies.
- Genetic testing is becoming increasingly important for identifying SCA subtypes.
- SCA3, SCA2, SCA1, and SCA6 represent important therapeutic research areas.
- Physical therapy remains a major component of current patient management.
- ASO, RNAi, gene-editing, and regenerative approaches are expanding the therapeutic pipeline.
- North America currently represents the leading regional market.
- Asia-Pacific provides significant future growth opportunities.
- Precision medicine can enable subtype-specific treatment strategies.
- Biomarkers can improve patient selection and clinical-trial development.
- Small patient populations and genetic heterogeneity remain major development challenges.
- Orphan-drug and accelerated regulatory pathways can support innovative therapy development.
- Strategic partnerships can accelerate commercialization and expand access to specialized therapies.
Global Spinocerebellar Ataxia Market Dynamics: Drivers
Rising prevalence of spinocerebellar ataxia
Spinocerebellar ataxia is a degenerative condition that greatly affects the patient's quality of life. At present, the treatment is focused on alleviating the symptoms, improving the mobility among patients, and improving the overall quality of life. There are no approved therapies till now, which is raising the number of patients with unmet needs.
However, several emerging companies are actively involved in the development of novel therapies that address the unmet needs of SCA patients. There are several innovative therapies in late late-stage clinical pipeline for SCA, and are expected to make market entry in the forecast period, driving the overall market growth.
For instance, in May 2025, Biohaven Ltd., one of the key innovators in the spinocerebellar ataxia treatment landscape, announced that the U.S. FDA decision for marketing authorization of troriluzole is expected by the 4Q of 2025. With this anticipated approval, troriluzole becomes the first drug for SCA, and is expected to be available commercially from the beginning of 2026. This anticipated approval is expected to address patients with high unmet needs and propel the overall market growth.
Emerging therapies and market approvals
Emerging therapies and market approvals represent a critical driver for the global spinocerebellar ataxia (SCA) market by introducing the first potential disease-modifying treatments for this rare, progressive neurodegenerative disorder.
A prime example is Biohaven’s troriluzole, a glutamate modulator whose New Drug Application (NDA) was accepted by the FDA and granted Priority Review, with a decision expected by late 2025. If approved, troriluzole would become the first FDA-approved treatment for SCA, demonstrating a 50% to 70% slowing of disease progression across multiple SCA genotypes in a pivotal real-world evidence study.
The FDA’s granting of Priority Review, Fast Track, and Orphan Drug Designation to troriluzole underscores the unmet medical need and the potential impact of emerging therapies in this space. These regulatory designations accelerate the review process and facilitate earlier patient access to innovative treatments, which is especially important given the lack of currently approved therapies for SCA.
Beyond troriluzole, other investigational therapies are advancing in the pipeline, including antisense oligonucleotide treatments like Cure Rare Disease’s CRD-002 targeting SCA3, which has also received FDA Orphan Drug Designation. This highlights a broader trend toward precision medicine approaches that target specific genetic mutations underlying different SCA subtypes, expanding therapeutic options and market potential.
Global Spinocerebellar Ataxia Market - Scope
| Metrics | Details | |
| CAGR | 7.4% | |
| Market Size Available for Years | 2022-2033 | |
| Estimation Forecast Period | 2025-2033 | |
| Revenue Units | Value (US$ Mn) | |
| Segments Covered | Type | SCA1, SCA2, SCA3, SCA6, Others |
| Treatment Type | Physical Therapy, Speech Therapy, Occupational Therapy, Ocular Care, Pharmacotherapy | |
| Regions Covered | North America, Europe, Asia-Pacific, South America, and the Middle East & Africa | |
Global Spinocerebellar Ataxia Market Dynamics: Restraints
Genetic heterogeneity and diversified patient population
Spinocerebellar ataxia is a condition with a variety of genes involved in its pathophysiology. Up until now, over 40 different types of SCA, each with unique genetic mutations. This wide genetic variability leads to a broad spectrum of clinical presentations, varying in age of onset, symptom severity, rate of progression, and neurological features, even among patients diagnosed with the same subtype. As a result, developing universal diagnostic tools and treatment regimens becomes extremely challenging.
Development treatments in a one-size-fits-all approach can become very complex. This genetic variability complicates the development of effective therapies, as they may need to be tailored for specific genetic profiles. This variability can slow down the investments, clinical trials, and hinder the development of novel therapies, thereby limiting the market expansion.
Global Spinocerebellar Ataxia Market Dynamics: Opportunities
Development of disease-modifying and regenerative medicine
The development of disease-modifying and regenerative medicine therapies is a major opportunity for the global spinocerebellar ataxia (SCA) market, fundamentally shifting the treatment landscape from symptomatic management to interventions that target the underlying causes of the disease.
Disease-modifying therapies under development include gene editing technologies, RNA interference (RNAi), antisense oligonucleotides (ASOs), and targeted pharmacological agents. These approaches are designed to silence or reduce the expression of mutant genes or proteins responsible for SCA, offering the potential to slow, stop, or even reverse disease progression.
Regenerative medicine, particularly stem cell-based therapies, is also emerging as a promising approach for SCA. Stemchymal, an allogeneic mesenchymal stem cell (MSC) therapy, has demonstrated the ability to clear toxic mutant proteins, reduce inflammation, and potentially repair neural tissue in preclinical and clinical studies. Phase 2 trials in Taiwan and Japan have shown that Stemchymal can stabilize or improve motor function in SCA3 and SCA6 patients, providing the first evidence of a disease-modifying effect in this population. These results suggest that regenerative medicine could offer not only symptomatic relief but also true modification of disease progression.
Global Spinocerebellar Ataxia Market - Segment Analysis
The global spinocerebellar ataxia market is segmented based on type, treatment type, and region.
Treatment Type:
The physical therapy treatment type segment is expected to hold 26.8% of the global spinocerebellar ataxia market in 2024
Physical therapy is the most commonly used treatment for spinocerebellar ataxia (SCA), as it focuses on improving the major symptoms such as impaired motor function, coordination, and balance. These symptoms are central to many forms of SCA, making physical therapy essential in managing the disease. Physical therapists design individualized programs for SCA patients, and they include strength exercises to target muscle weakness, which is common in SCA patients.
These exercises help maintain muscle strength and prevent joint deformities. Additionally, gait training with assistive devices, like walkers or canes, allows patients to walk more safely. In the patient’s journey, physical therapy has a major share in out-of-pocket costs, due to the need for long-term care, limited insurance coverage for chronic conditions, the requirement of specialized care and frequent sessions, along with the potential need for assistive devices, which further increase these costs.
Although pharmacotherapy is gaining momentum in the SCA treatment landscape, patient needs physical therapy along with the medication to retain their physical strength and motor skills. This signifies the need for physical therapy in SCA management, and its dominance among other treatment types.
Global Spinocerebellar Ataxia Market – Geographical Analysis
North America is expected to hold 41.2% of the global spinocerebellar ataxia market in 2024
The North America region dominates the spinocerebellar ataxia market due to its advanced healthcare infrastructure, availability of resources to manage patients with chronic degenerative conditions like spinocerebellar ataxia, etc. Moreover, with the heavy investments in the healthcare industry by the public and private sectors, the diagnosis and treatment rates of various diseases are high in the region.
As per various epidemiological studies, the total prevalent cases of spinocerebellar ataxia in the U.S. are approximately 15,000. These patients have access to care centers to cater to various needs. The region has the highest number of caregivers, physical therapists, who provide services at the patient's convenience. Moreover, the region’s well-framed reimbursement policies enable more patients to opt for these services and manage their condition.
Additionally, several pharmaceutical companies are actively making investments in developing novel therapies for SCA. One such key investment is by Biohaven, Ltd., which is developing Troriluzole as the first in-therapy drug for SCA. The company has developed this drug with huge investments, and is planning to launch it in the U.S. market. If approved, the U.S. patient population will gain first access to this first-in-therapy drug. Hence, all these factors reflect the dominance of North America in the global spinocerebellar ataxia market.
Asia Pacific is expected to hold 18.9% of the global spinocerebellar ataxia market in 2024
The Asia-Pacific region is experiencing a growing number of diagnosed spinocerebellar ataxia (SCA) cases, driven by increased awareness of hereditary neurodegenerative disorders and improved access to genetic testing. As more families and clinicians recognize the hereditary patterns and symptoms of SCA, earlier and more accurate diagnoses are becoming possible, supporting market growth.
The adoption of advanced neuroimaging (MRI, PET scans) and genetic sequencing technologies is enabling earlier detection and more precise characterization of SCA subtypes. These tools are becoming more widely available in countries such as Japan, China, South Korea, and India, facilitating better patient management and opening new opportunities for targeted therapies.
There is a growing emphasis on multidisciplinary care including physical, speech, and occupational therapy—across Asia-Pacific healthcare systems. These supportive treatments, along with adaptive devices, are improving quality of life for patients and driving demand for comprehensive care solutions.
The use of both symptomatic pharmacological treatments and participation in clinical trials for emerging therapies is increasing in the region. As new drugs, such as troriluzole and other late-stage pipeline therapies, progress toward approval, Asia-Pacific markets are expected to see greater access to innovative treatments.
Global Spinocerebellar Ataxia Market - Competitive Landscape
The major global players in the spinocerebellar ataxia market include Biohaven, Ltd., Arrowhead Pharmaceuticals, Vico Therapeutics, Seelos Therapeutics, Inc., Steminent Corp, Pfizer Inc., Amneal Pharmaceuticals LLC., Teva Pharmaceutical Industries Ltd., and AbbVie Inc., among others.
Key Developments in the Global Spinocerebellar Ataxia Market
- August 2026: Biohaven Ltd. continued advancing its spinocerebellar ataxia pipeline, with clinical development focused on targeted therapies designed to address the underlying mechanisms of disease.
- July 2026: Vico Therapeutics continued progressing its VO659 program for genetically defined neurological diseases, including spinocerebellar ataxia type 3 (SCA3), with continued focus on RNA-targeting therapeutic approaches.
- July 2026: Arrowhead Pharmaceuticals continued advancing its RNAi-based neurological disease pipeline, supporting broader development of gene-silencing approaches for inherited neurological disorders.
- June 2026: Seelos Therapeutics, Inc. continued exploring therapeutic approaches for neurodegenerative diseases, maintaining its focus on developing treatments addressing significant unmet neurological needs.
- June 2026: Steminent Corp. continued research into regenerative medicine approaches for neurodegenerative disorders, including potential cell-based strategies relevant to hereditary neurological diseases.
- May 2026: Pfizer Inc. continued evaluating opportunities across rare diseases and neurological disorders, supporting research and development activities relevant to inherited neurodegenerative conditions.
- May 2026: Amneal Pharmaceuticals LLC. continued strengthening its specialty-pharmaceutical portfolio and rare-disease capabilities, supporting opportunities in neurological and other underserved therapeutic areas.
- April 2026: Teva Pharmaceutical Industries Ltd. continued advancing its specialty-neurology portfolio and research activities, with neurological disorders remaining an important area of its pharmaceutical business.
- April 2026: AbbVie Inc. continued investing in neuroscience research and development, focusing on innovative treatments for neurological and neurodegenerative conditions with significant unmet medical needs.
The global spinocerebellar ataxia market report delivers a detailed analysis with 51 key tables, more than 45 visually impactful figures, and 173 pages of expert insights, providing a complete view of the market landscape.
Why Choose DataM?
Clinical & Therapeutic Developments: Covers advancements in SCA treatment, including physical rehabilitation, pharmacotherapy, ASOs, RNAi, gene therapies, gene editing, regenerative medicine, and emerging disease-modifying approaches.
Pipeline & Competitive Positioning: Evaluates leading companies based on clinical-stage assets, target SCA subtype, mechanism of action, clinical development stage, regulatory status, differentiation strategy, and commercialization potential.
Diagnostic & Genetic Testing Landscape: Examines genetic testing, sequencing, neuroimaging, biomarker development, and emerging diagnostic technologies supporting earlier and more precise SCA diagnosis.
Market Trends and Industry Changes: Tracks clinical-trial activity, regulatory designations, therapy development, genetic-testing adoption, research investments, partnerships, grants, and emerging treatment approaches.
Competitive Strategies: Analyzes strategies including precision-medicine development, orphan-disease positioning, strategic partnerships, pipeline expansion, biomarker development, licensing, and geographic expansion.
Pricing & Market Access: Evaluates treatment costs, rehabilitation expenses, genetic-testing costs, reimbursement considerations, patient-support programs, and potential pricing challenges associated with innovative rare-disease therapies.
Market Entry & Expansion: Identifies opportunities across disease-modifying treatments, genetic diagnostics, rehabilitation, specialty care centers, biomarkers, and emerging therapies, with emphasis on high-potential markets in North America, Europe, and Asia-Pacific.
Target Audience
- Pharmaceutical & Biotechnology Companies
- Rare-Disease Drug Developers
- Genetic Testing Companies
- Clinical Research Organizations
- Investors & Financial Institutions
- Neurology & Specialty Care Providers
- Research Institutions
- Regulatory Authorities
- Healthcare Payers
- Specialty Clinics & Hospitals
- Patient Support Organizations
- Market Researchers & Consultants



























































