


Phenylketonuria Treatment Market Size and Overview
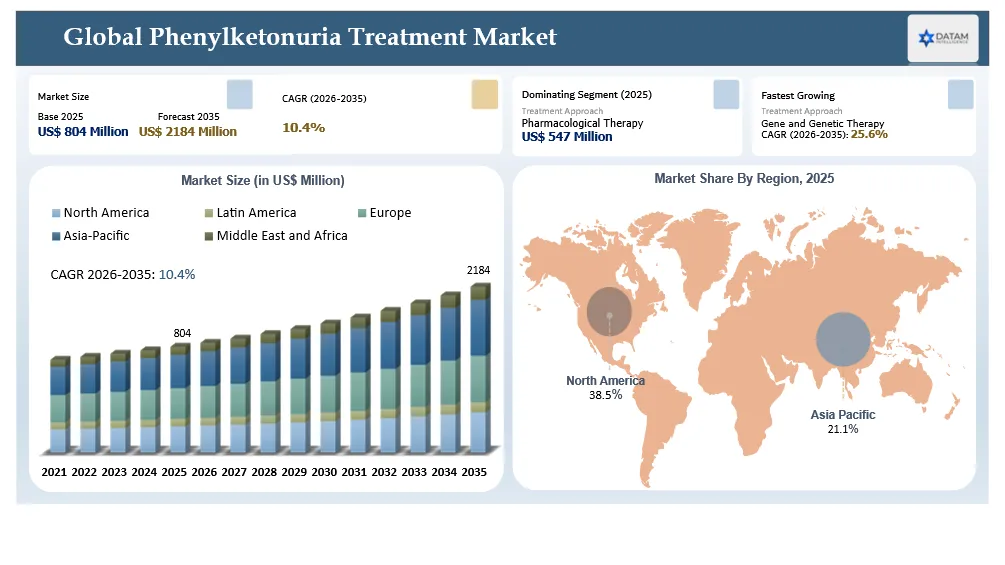
The global phenylketonuria treatment market reached US$ 804 million in 2025 and is expected to reach US$ 2184 million by 2035, growing with a CAGR of 10.4% during the forecast period 2026-2035.
Growth reflects a structural transition from lifelong dependence on phenylalanine-restricted diets and medical nutrition toward response-guided pharmacotherapies and potentially disease-modifying interventions. Expanded newborn screening, improved lifelong patient identification and increasing demand for dietary liberalization are enlarging the commercially addressable population. KUVAN and PALYNZIQ remain established pharmacological options, while specialized amino-acid formulas and low-protein foods continue to anchor care across pediatric, adult and maternal PKU populations. However, heterogeneous PAH responsiveness, high treatment costs, fragmented medical-food reimbursement and persistent dietary burden continue to create significant unmet need.
Recent approvals have materially reshaped the market’s regulatory and competitive profile. The FDA approved SEPHIENCE in July 2025 for sepiapterin-responsive patients aged one month and older, while PALYNZIQ’s February 2026 U.S. label expansion extended eligibility to patients aged 12 years and above. Pharmacological therapies retain market leadership, but gene replacement, base editing, PAH stabilization and genotype-independent oral platforms are expected to generate the strongest long-term growth. Future competitive advantage will depend on durable phenylalanine reduction, dietary flexibility, neurocognitive protection, convenient administration, long-term safety and evidence demonstrating lower lifetime management burden.
Phenylketonuria Treatment Market Key Takeaways
- Sustained Market Expansion Through 2035: The global phenylketonuria treatment market was valued at US$804 million in 2025 and is projected to reach US$2,184 million by 2035, registering a CAGR of 10.4% during 2026-2035.
- Pharmacological Therapies Maintain Market Leadership: Pharmacological therapy accounted for an estimated 68% market share, equivalent to approximately US$547 million in 2025, supported by established KUVAN and PALYNZIQ use and the commercial introduction of SEPHIENCE.
- Genetic Therapies Become the Primary Growth Engine: Gene and genetic therapy is projected to register an estimated CAGR of 25.6% during 2026-2035, driven by advancing gene-replacement, base-editing and liver-targeted platforms seeking durable phenylalanine control.
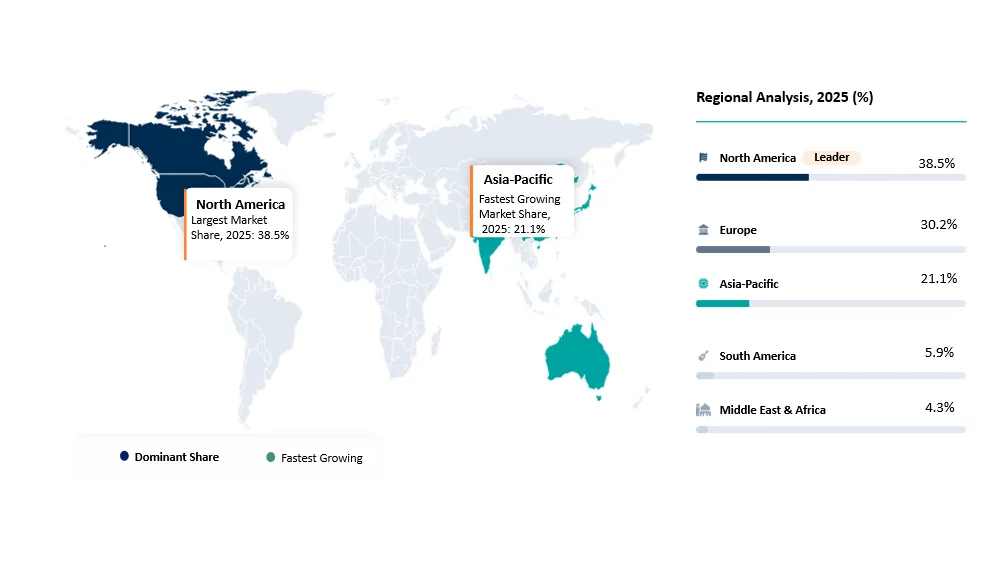
- North America Maintains Regional Dominance: North America accounted for approximately 38.5% of the global market in 2025, equivalent to around US$310 million, supported by comprehensive newborn screening, established metabolic-care networks and strong adoption of premium PKU therapies.
- Treatment Differentiation Reshapes Competitive Strategy: Future market leadership will depend on durable phenylalanine reduction, dietary liberalization, neurocognitive protection, safety, administration convenience and responsiveness across different PAH genotypes rather than biochemical improvement alone.
Phenylketonuria Treatment Market Industry Trends and Strategic Insights
- The market is transitioning from diet-dominated management toward an integrated model combining medical nutrition, response-guided pharmacotherapy and emerging disease-modifying treatments. This evolution expands treatment value beyond phenylalanine control to dietary liberalization, neurocognitive protection and improved quality of life.
- KUVAN and PALYNZIQ continue to anchor pharmacological treatment, while SEPHIENCE is intensifying competition through oral administration, broad age eligibility and activity across sepiapterin-responsive patients. Competitive differentiation will increasingly depend on response depth, treatment persistence, dietary flexibility, safety and reimbursement execution.
- PALYNZIQ’s 2026 U.S. adolescent indication expansion strengthens the commercial opportunity for earlier treatment escalation among patients with inadequately controlled phenylalanine. Metabolic specialists will increasingly segment patients by age, disease severity, PAH responsiveness, baseline phenylalanine concentration and treatment burden.
- Genotype-independent oral therapies, PAH stabilizers, enzyme substitution, gene replacement and base-editing platforms could reshape the long-term treatment pathway. Their commercial impact will depend on durable metabolic control, neurocognitive outcomes, administration convenience, manufacturing scalability and evidence supporting reduced lifelong dietary dependence.
- Sustainable competitive advantage will require integrated medicine, nutrition and patient-support capabilities. Companies demonstrating reliable phenylalanine control, meaningful diet liberalization, convenient administration and lower lifetime management burden will be better positioned to secure specialist adoption, formulary access and premium reimbursement.
Phenylketonuria Treatment Market Scope
| Metrics | Details | |
| 2025 Market Size | US$ 804 Million | |
| 2035 Projected Market Size | US$ 2184 Million | |
| CAGR (2026-2035) | 10.4% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Treatment Approach | Medical Nutrition, Pharmacological Therapy, Gene and Genetic Therapy, Combination Therapy | |
| By Route of Administration | Oral, Subcutaneous, Intravenous, Others | |
| By Patient Age | Infants, Children, Adolescents, Adults | |
| By Disease Severity | Mild Hyperphenylalaninemia, Mild-to-Moderate PKU, Severe PKU | |
| By Drug Type | Branded Drugs, Generic Drugs | |
| By Treatment Intent | Phenylalanine Control, Dietary Liberalization, Neurocognitive-Risk Reduction, Maternal PKU Management, Long-Term Disease Modification | |
| By Treatment Setting | Home-Based Management, Metabolic and Genetic Clinics, Hospitals, Specialty Treatment Centers | |
| By PAH Responsiveness | PAH-Responsive PKU, Partially PAH-Responsive PKU, PAH-Nonresponsive PKU, Others | |
| By Distribution Channel | Specialty Pharmacies, Hospital Pharmacies, Retail Pharmacies, Medical-Nutrition Distributors, Direct-to-Patient Channels, E-Commerce Channels | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Why does this report matter in 2026?
The PKU treatment market reached a strategic inflection point following the 2025 approval and rapid commercialization of SEPHIENCE, alongside PALYNZIQ’s February 2026 US label expansion to patients aged 12 years and older. These developments are widening treatment eligibility, intensifying competition with KUVAN and shifting clinical expectations toward sustained phenylalanine reduction, broader responsiveness and greater dietary freedom. Stakeholders require an updated view of patient segmentation, treatment sequencing, pricing, reimbursement and adoption across heterogeneous healthcare systems.
Competitive disruption is accelerating as Otsuka advances repinatrabit through Phase III, Maze progresses MZE782, Agios evaluates AG-181 and Beam develops the gene-editing candidate BEAM-304. Simultaneously, medical-nutrition suppliers are improving palatability, convenience and age-specific formulations to defend their position within lifelong disease management. This report enables pharmaceutical companies, nutrition manufacturers, investors and market-access teams to evaluate commercial readiness, benchmark asset differentiation and identify partnership opportunities. It also clarifies how genotype coverage, administration burden, safety, durability, payer evidence and potential diet liberalization will determine future market positioning and value creation.
Phenylketonuria Treatment Market White Space & Investment Opportunities
- Earlier Identification of Poorly Controlled Patients: Invest in home-based phenylalanine monitoring, predictive analytics and clinical decision-support tools that identify patients with persistently elevated or fluctuating phenylalanine levels before neurocognitive and psychological complications intensify.
- Genotype-Independent Oral Therapies: Develop convenient treatments capable of delivering clinically meaningful phenylalanine reduction across disease severities and PAH genotypes, particularly for patients who respond inadequately to existing cofactor-based therapies.
- Durable Genetic and Enzyme-Based Treatments: Advance gene editing, gene replacement, messenger RNA and next-generation enzyme substitution platforms offering sustained metabolic control, reduced treatment burden and potential freedom from restrictive dietary management.
- Diet Liberalization and Treatment-Sequencing Evidence: Generate comparative evidence defining how SEPHIENCE, KUVAN, PALYNZIQ, emerging oral therapies and medical nutrition should be sequenced or combined across age groups, biochemical profiles and treatment-response categories.
- Next-Generation Medical Nutrition: Invest in palatable, low-volume, age-specific and prolonged-release protein substitutes, glycomacropeptide formulations and convenient low-protein foods that improve lifelong adherence without compromising nutritional adequacy.
- Geographic Access and Outcome-Based Reimbursement: Expand newborn screening, metabolic-care infrastructure and reimbursement across underserved markets while building longitudinal evidence connecting phenylalanine control and dietary freedom with neurocognitive outcomes, quality of life and reduced lifetime healthcare burden.
Phenylketonuria Treatment Market Future Transformation
The PKU treatment market will transition from diet-dominated management toward precision-based, multimodal care combining pharmacotherapy, medical nutrition and potentially durable genetic intervention. SEPHIENCE is expanding the cofactor-responsive population, while PALYNZIQ remains important for patients requiring substantial phenylalanine reduction. Emerging oral SLC6A19 inhibitors, including repinatrabit and MZE782, could broaden genotype-independent treatment and reduce dependence on restrictive diets. PAH stabilizers and improved enzyme-substitution approaches may further support individualized treatment sequencing across biochemical severity and age groups.
Longer-term transformation will be shaped by gene editing, gene replacement and messenger RNA platforms seeking sustained metabolic correction rather than continuous phenylalanine management. Commercial differentiation will increasingly depend on durable control, dietary liberalization, neurocognitive outcomes, safety and treatment convenience instead of phenylalanine reduction alone. Digital monitoring, home-based testing and longitudinal patient registries will support earlier intervention and outcome-based reimbursement. Medical-nutrition companies will respond with more palatable, low-volume and prolonged-release formulations. Companies integrating therapeutic innovation, biomarker-led segmentation, payer evidence and scalable delivery will be positioned to capture future market value.
Phenylketonuria Treatment Market Buyer Decision-Making Criteria
- Magnitude and Durability of Phenylalanine Reduction
- Responsiveness Across PKU Genotypes and Disease Severities
- Potential for Dietary Liberalization
- Neurocognitive and Patient-Reported Outcomes
- Safety, Tolerability and Long-Term Evidence
- Age Eligibility and Pediatric Clinical Evidence
- Route, Dosing Convenience and Treatment Burden
- Compatibility with Medical Nutrition and Existing Therapies
- Pricing, Reimbursement and Lifetime Budget Impact
- Guideline Positioning, Physician Experience and Patient Support
In the phenylketonuria treatment market, prescribing, purchasing and formulary decisions are primarily driven by a therapy’s ability to achieve sustained blood phenylalanine control while reducing the burden of lifelong dietary restriction. Metabolic specialists, treatment centers and payers evaluate response magnitude, consistency across PAH genotypes, baseline phenylalanine levels, age eligibility and the proportion of patients achieving guideline-recommended targets. The ability to increase natural-protein tolerance and improve neurocognitive functioning, psychological health and quality of life strengthens clinical differentiation.
Safety and treatment burden remain central considerations because PKU requires lifelong management. Buyers assess administration route, dosing frequency, injection-related reactions, monitoring requirements and compatibility with protein substitutes or existing pharmacotherapy. Payers additionally examine acquisition costs, eligible-patient numbers, medical-nutrition savings and potential avoidance of long-term neurological and productivity-related burdens. Therapies supported by comparative evidence, durable outcomes, guideline inclusion, reliable supply and comprehensive adherence services will be best positioned to secure reimbursement and sustained adoption.
Phenylketonuria Treatment Market Economic & Investment Analysis
The PKU market is becoming an increasingly attractive rare-disease investment segment, supported by lifelong treatment demand, premium-priced therapies and expanding eligibility. SEPHIENCE’s rapid launch provides early commercial validation, generating approximately US$124.6 million in first-quarter 2026 revenue and US$151.3 million in the second quarter. BioMarin’s established KUVAN and PALYNZIQ franchises provide further evidence of durable revenue potential, although growing therapeutic choice is increasing competitive pressure around response breadth, administration burden, safety and dietary liberalization.
Investment is shifting toward genotype-independent oral agents and potentially durable genetic interventions. Otsuka’s Phase III repinatrabit program, Maze’s MZE782, Agios’ AG-181 and Beam’s BEAM-304 illustrate increasing capital allocation across transporter inhibition, PAH stabilization and gene editing. Value creation will depend on clinical differentiation, scalable manufacturing, regulatory execution and evidence supporting reduced medical-nutrition dependence. However, small patient populations, heterogeneous reimbursement and long development timelines elevate execution risk. Assets combining broad eligibility, durable phenylalanine control, convenient delivery and credible payer evidence should command stronger licensing, partnership and acquisition interest.
Phenylketonuria Treatment Market Investment Trends
- Capital allocation is increasing toward geographic launches, specialist engagement, reimbursement and patient-support infrastructure for SEPHIENCE and the expanded adolescent indication for PALYNZIQ.
- Repinatrabit and MZE782 are attracting investment because SLC6A19 inhibition could deliver broad phenylalanine reduction independent of PAH genotype, disease severity or cofactor responsiveness.
- Investment is accelerating across gene editing, gene replacement and messenger RNA platforms seeking durable metabolic correction and reduced dependence on lifelong pharmacotherapy and dietary restriction.
- Investors increasingly prioritize assets capable of expanding natural-protein tolerance, reducing medical-food dependence and delivering measurable improvements in treatment burden, adherence and quality of life.
- Medical-nutrition investment is targeting palatable glycomacropeptide products, prolonged-release amino-acid formulations, low-volume protein substitutes and age-specific solutions designed to support lifelong nutritional management.
- Companies are allocating greater resources to registries, real-world evidence and health-economic studies linking sustained phenylalanine control with neurocognitive preservation, productivity gains and lower lifetime healthcare expenditure.
Strategic Indicators for Phenylketonuria Treatment Market
High Regulation Impact
The phenylketonuria treatment market faces high regulatory scrutiny because therapies may be initiated during infancy and continued throughout life. Regulators require evidence of sustained blood phenylalanine reduction, acceptable safety, age-appropriate dosing and nutritional adequacy across heterogeneous PAH genotypes and disease severities. The approval of SEPHIENCE and PALYNZIQ’s adolescent label expansion demonstrates pathways for broader treatment eligibility, while genetic medicines must address additional concerns regarding off-target effects, immunogenicity and durability. Developers require pediatric studies, long-term extensions, post-marketing surveillance and patient-reported outcomes connecting biochemical control with neurocognitive and functional benefit. These requirements increase development complexity, evidence-generation costs and timelines.
High Investment Activity
Investment activity is increasing as PKU develops beyond diet-based management into a differentiated rare-disease market encompassing oral pharmacotherapy, enzyme substitution, medical nutrition and genetic medicine. SEPHIENCE’s rapid commercial uptake has validated demand for therapies offering meaningful phenylalanine reduction and dietary liberalization. Capital is increasingly directed toward SLC6A19 inhibitors, PAH stabilizers, gene editing, gene replacement, messenger RNA delivery and next-generation protein substitutes. Otsuka, Maze, Agios and Beam illustrate the growing diversity of investment across development stages. Investors favor assets with broad genotype coverage, convenient administration, scalable manufacturing and measurable potential to reduce lifelong treatment and dietary burden.
Pricing Volatility
Pricing volatility is expected to remain moderate because the market combines generic sapropterin, premium branded pharmacotherapies and recurring medical-nutrition expenditure. Net prices vary according to treatment response, age eligibility, administration route, monitoring requirements, payer rebates and country-specific reimbursement systems. Competition among KUVAN, SEPHIENCE and future oral agents may increase formulary negotiation and rebate pressure, while PALYNZIQ and potentially durable genetic therapies require different value frameworks. International reference pricing and inconsistent medical-food coverage create further geographic variation. Manufacturers demonstrating durable phenylalanine control, dietary liberalization, improved quality of life and reduced lifetime management costs will be better positioned to protect premium pricing.
High Market-Access Pressure
Market-access pressure remains high because payers may restrict premium therapies to patients meeting defined biochemical, response or prior-treatment criteria. Coverage decisions can consider baseline phenylalanine concentration, PAH genotype, cofactor responsiveness, dietary adherence, age, previous treatment and specialist documentation. Competing therapies will face comparative evaluation despite limited head-to-head evidence, increasing reliance on indirect comparisons and real-world outcomes. Payers will assess whether treatment achieves guideline-recommended phenylalanine levels, expands natural-protein tolerance and reduces dependence on medical foods. Strong health-economic models, response-testing protocols, patient-support services and evidence linking biochemical control with neurocognitive preservation will be essential for sustained reimbursement.
High New Drug-Class Adoption
PKU is entering a period of accelerated treatment-class adoption as management expands beyond restrictive diets and conventional cofactor therapy. SEPHIENCE has strengthened the pharmacological-chaperone category, while PALYNZIQ established enzyme substitution for patients requiring substantial phenylalanine reduction. Emerging SLC6A19 inhibitors could introduce genotype-independent oral treatment, while PAH stabilizers and genetic medicines offer additional differentiation. Adoption will depend on response breadth, safety, administration burden, monitoring requirements and the degree of dietary liberalization achieved. Metabolic specialists will position therapies according to age, genotype, baseline phenylalanine and prior response rather than treating emerging classes as interchangeable.
Regional Expansion Opportunity
Regional expansion potential is significant because PKU is detected worldwide, but newborn screening, metabolic-specialist capacity, medical-food availability and reimbursement remain uneven. The United States offers strong commercial potential through established screening, specialist centers, specialty pharmacies and orphan-drug reimbursement. Europe provides a sizeable diagnosed population but requires country-specific health-technology assessment and nutrition-coverage strategies. Japan is attractive due to structured rare-disease care, while China, Latin America, the Middle East and parts of Asia-Pacific offer longer-term opportunities as screening coverage improves. Successful expansion requires local epidemiology, regulatory planning, payer engagement, metabolic-center partnerships and reliable distribution of both medicines and specialized nutrition.
Government Policy Support
Government support is delivered through universal or targeted newborn screening, orphan-drug incentives, expedited regulatory pathways, rare-disease programs and public reimbursement. These mechanisms improve early diagnosis and reduce development risk for therapies addressing lifelong phenylalanine control. Public health systems also shape the market through treatment guidelines, specialist referral pathways, medical-food coverage and laboratory-monitoring infrastructure. Support remains uneven, particularly where specialized nutrition is excluded from insurance or advanced therapies compete with constrained rare-disease budgets. Companies should align evidence generation with regulator and payer expectations, support patient registries and screening expansion, and demonstrate value beyond orphan designation to secure sustainable access.
Value-Based Pricing Intelligence
Value-based pricing in PKU will increasingly depend on clinical and lifetime economic outcomes rather than mechanism novelty alone. Therapies must connect sustained phenylalanine reduction with dietary liberalization, improved executive functioning, psychological well-being, educational participation and treatment adherence. Potentially durable genetic medicines will require evidence that long-term benefits justify substantial upfront costs and reduce recurring pharmaceutical and medical-nutrition expenditure. Pricing potential will vary across age groups, genotype-responsive populations, poorly controlled patients and individuals with significant dietary burden. Manufacturers combining broad eligibility, convenient administration, limited monitoring and real-world neurocognitive evidence will be better positioned to negotiate favorable formulary access and outcome-based agreements.
Pipeline Analysis
As of July 2026, the therapeutic pipeline for Phenylketonuria (PKU) is robust, encompassing various modalities aimed at slowing disease progression and preserving vision. Here's an overview of key investigational therapies across different classes:
| Company | Asset | Current Stage | Mechanism | Route | Modality |
Otsuka Pharmaceutical / Jnana Therapeutics | Repinatrabit (JNT-517) | Phase III | Selective SLC6A19 inhibitor that reduces renal phenylalanine reabsorption and increases urinary phenylalanine elimination | Oral | Small molecule |
Maze Therapeutics | MZE782 | Phase II | SLC6A19 inhibitor designed to reduce intestinal phenylalanine absorption and renal reabsorption | Oral | Small molecule |
| Sanofi | SAR444836 | Phase I/II | AAV-mediated transfer of a functional human PAH gene to restore hepatic phenylalanine metabolism | Intravenous, single dose | Gene therapy |
BioMarin Pharmaceutical | BMN 307 | Phase I/II | AAV5-mediated delivery of a functional PAH gene into hepatocytes | Intravenous, single dose | Gene therapy |
Agios Pharmaceuticals | AG-181 | Phase I | Phenylalanine hydroxylase stabilizer designed to increase functional PAH activity and phenylalanine clearance | Oral | Small molecule |
Gritgen Therapeutics | GS1168 | Early Phase I | Liver-directed gene therapy designed to restore PAH activity through a dual-mechanism approach | Intravenous injection | Gene therapy |
Chongqing Peg-Bio Biopharm | PL54 | Phase I | Investigational phenylalanine-lowering mechanism; molecular target not disclosed in the ClinicalTrials.gov record | Subcutaneous injection | Biological therapy |
AI Impact Analysis of Phenylketonuria Treatment Market
Artificial intelligence is strengthening PKU drug development by improving genotype-phenotype interpretation, molecular design, responder prediction and clinical-trial selection. Machine-learning models can integrate PAH variants, baseline phenylalanine levels, dietary intake and historical treatment response to identify patients most likely to benefit from cofactor therapies, enzyme substitution or emerging oral agents. AI-enabled analysis may also support mutation selection for gene-editing programs and optimize delivery-system design. Within clinical development, synthetic control arms, automated biomarker analysis and predictive recruitment tools could reduce trial timelines and improve evidence generation in geographically dispersed rare-disease populations.
In clinical practice, AI can improve lifelong management by combining home phenylalanine measurements, dietary records, medication adherence and patient-reported outcomes. Digital platforms may provide personalized protein-intake recommendations, flag deteriorating metabolic control and support earlier specialist intervention. Image recognition can simplify food tracking, while predictive analytics can identify patients at risk of disengagement or neurocognitive complications. Commercially, manufacturers can use AI to refine patient finding, forecast treatment eligibility and target support services. Adoption will depend on clinical validation, data interoperability, privacy protection, algorithm transparency and maintaining specialist oversight in treatment decisions.
Disruption Analysis of Phenylketonuria Treatment Market
The PKU treatment market is being disrupted by the transition from diet-led management toward differentiated therapies capable of delivering deeper phenylalanine reduction and greater dietary freedom. SEPHIENCE has intensified competition by expanding cofactor-based treatment across broader responsive populations, while PALYNZIQ’s adolescent label expansion extends enzyme substitution into an earlier age group. Emerging SLC6A19 inhibitors, including repinatrabit and MZE782, could further reshape treatment sequencing by offering convenient, genotype-independent oral control. These developments challenge the established dependence on KUVAN, injectable therapy and restrictive medical nutrition.
The next disruption wave will come from genetic medicines seeking durable correction of the underlying PAH deficiency. Beam’s BEAM-304 base-editing program, alongside gene replacement and messenger RNA approaches, could shift value from recurring treatment toward potentially one-time intervention. This transition will pressure existing commercial models, reimbursement frameworks and medical-food demand. However, long-term safety, durability, manufacturing scalability and mutation coverage will determine adoption. Digital phenylalanine monitoring, home testing and real-world evidence will also redefine patient management. Companies combining broad eligibility, sustained biochemical control, dietary liberalization and compelling lifetime economic value will be positioned to lead the market’s transformation.
Phenylketonuria Treatment Market BCG Matrix: Company Evaluation
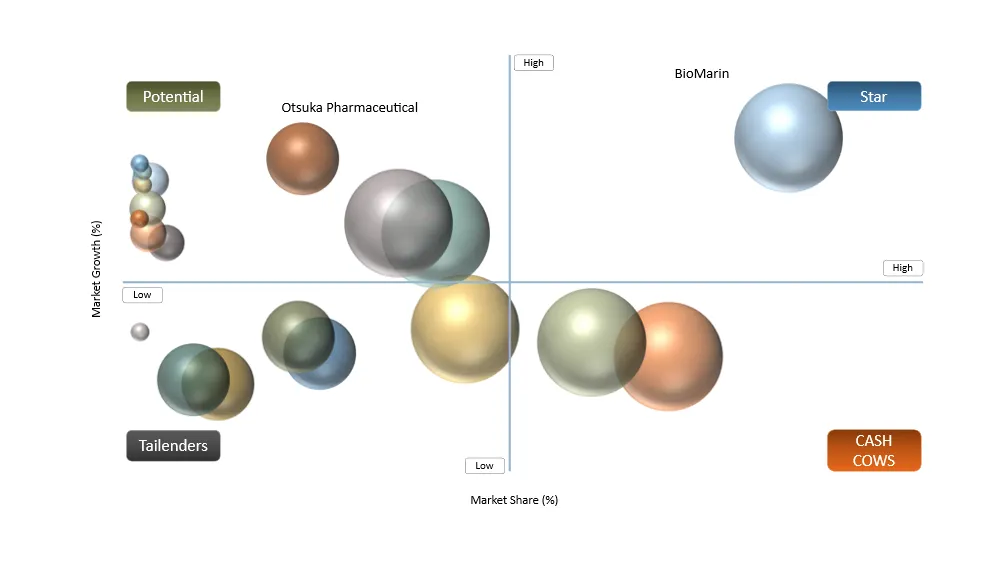
STAR
BioMarin Pharmaceutical and PTC Therapeutics are positioned in the Star category based on their approved PKU portfolios, commercial infrastructure and influence on the evolving treatment pathway. BioMarin maintains a leading position through KUVAN and PALYNZIQ, addressing both PAH-responsive patients and individuals requiring an enzyme-substitution approach independent of residual PAH activity. PALYNZIQ’s February 2026 FDA label expansion to patients aged 12 years and older further increased its addressable population.
PTC Therapeutics has strengthened its competitive position through SEPHIENCE, approved by the FDA in July 2025 for sepiapterin-responsive PKU patients aged one month and older. The therapy combines broad age eligibility, oral administration and potential dietary liberalization. Its subsequent approvals in Japan and Brazil demonstrate expanding geographic momentum. Future leadership will depend on payer access, treatment persistence, responsiveness testing and real-world evidence demonstrating durable phenylalanine control, dietary flexibility and improved patient outcomes.
POTENTIAL
Otsuka Pharmaceutical, Maze Therapeutics, Agios Pharmaceuticals, Beam Therapeutics, Gritgen Therapeutics, Chongqing Peg-Bio Biopharm and Relief Therapeutics are positioned in the Potential category because of their involvement in emerging pharmacological, enzyme-based and genetic treatment platforms.
Their pipelines span SLC6A19 inhibition, PAH stabilization, base editing, gene replacement, long-acting enzyme substitution and adjunctive metabolic management. Otsuka’s repinatrabit and Maze’s MZE782 could establish a genotype-independent oral treatment class, while Agios’ AG-181 is designed to stabilize PAH and enhance residual enzyme activity. Beam’s BEAM-304 and Gritgen’s GS1168 represent potentially disease-modifying genetic approaches. Progression toward the Star category will depend on clinically meaningful phenylalanine reduction, neurocognitive benefit, safety, treatment durability, manufacturing scalability and differentiation from established pharmacotherapies and lifelong medical-nutrition management.
Phenylketonuria Treatment Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Commercial Expansion of Broader-Eligibility Pharmacotherapies | 14.2% | High in North America, Europe and Japan | SEPHIENCE for responsive patients aged ≥1 month; PALYNZIQ expanded from adults in 2018 to adolescents aged 12-17 years in 2026 | Expands the pharmacologically treatable population, accelerates therapy switching and increases competition around phenylalanine reduction, dietary liberalization and treatment convenience. |
Expansion of Newborn Screening and Lifelong Patient Identification | 11.8% | High in developed markets; increasing across Asia-Pacific, Latin America and the Middle East | Earlier diagnosis, prompt dietary intervention and continuous treatment across pediatric-to-adult care | Enlarges the diagnosed and continuously managed population while supporting predictable, recurring demand for medicines, metabolic formulas, monitoring and specialist services. |
Advancement of Genotype-Independent and Genetic Therapies | 10.6% | Concentrated in the United States and Europe, with global clinical-development potential | Repinatrabit, MZE782, AG-181, BEAM-304 and other durable metabolic-correction approaches | Creates new treatment pathways for poorly controlled or nonresponsive patients and could shift market value toward oral and potentially one-time therapies. |
Innovation in Medical Nutrition and Adherence-Oriented Management | 8.9% | Global demand, with stronger reimbursement in North America and Western Europe | Glycomacropeptide formulas, prolonged-release amino acids, low-volume protein substitutes and low-protein foods | Improves lifelong adherence and nutritional adequacy while sustaining medical-nutrition demand alongside pharmacotherapy and supporting more individualized treatment plans. |
Driver: Commercial Expansion of Broader-Eligibility Pharmacotherapies
The PKU market is expanding as recently approved therapies extend pharmacological treatment beyond historically narrow responder and age-based populations. SEPHIENCE received FDA approval in July 2025 for sepiapterin-responsive patients aged one month and older, creating an oral treatment opportunity across pediatric and adult care. Rapid uptake confirms meaningful demand: SEPHIENCE generated US$151.3 million in second-quarter 2026 net sales, demonstrating strong early adoption across the United States and international markets.
PALYNZIQ’s FDA label expansion on February 27, 2026, from adults to adolescents aged 12-17 years, further enlarged the addressable enzyme-substitution population. The expansion enables earlier intervention for patients with inadequate phenylalanine control despite dietary management and strengthens BioMarin’s lifecycle position. Together, broader labels increase eligible-patient identification, specialist prescribing and competition across oral and injectable therapies. Future growth will depend on response-testing infrastructure, payer authorization, treatment adherence and evidence that biochemical improvement supports dietary liberalization, neurocognitive protection and better long-term quality of life.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
High Treatment Cost and Fragmented Reimbursement | 12.6% | Pricing, formulary access and patient affordability | Premium pharmacotherapies, specialized medical nutrition and lifelong monitoring | Restricts adoption outside well-funded rare-disease systems and creates substantial differences in treatment access across countries, insurers and patient age groups. |
Heterogeneous Treatment Response and Limited Eligibility | 10.9% | Patient selection, prescribing confidence and addressable population | Sapropterin, SEPHIENCE and other therapies dependent on residual PAH activity or demonstrated biochemical response | Limits universal treatment adoption because responsiveness cannot always be predicted through genotype alone and must often be established through therapeutic evaluation. |
Persistent Dietary and Treatment-Adherence Burden | 9.7% | Long-term metabolic control, persistence and quality of life | Phenylalanine-restricted diets, medical formulas, daily oral therapies and injectable treatment | Reduces real-world effectiveness as patients may struggle with dietary restriction, formula palatability, frequent monitoring and complex lifelong treatment routines. |
Safety, Administration and Monitoring Requirements | 8.4% | Physician adoption, treatment initiation and patient retention | PALYNZIQ injections, dose titration, hypersensitivity management and emerging genetic therapies | Slows treatment initiation and broader utilization by increasing specialist oversight, monitoring intensity, patient training and healthcare-system resource requirements. |
Restraint: High Treatment Cost and Fragmented Reimbursement
High treatment costs remain a major barrier to broad PKU therapy adoption, particularly where reimbursement for orphan drugs and medical nutrition is incomplete. Following its 2025 US approval, SEPHIENCE was launched at an estimated wholesale acquisition cost of approximately US$41,000 per month for an average 45-kg patient. Such pricing increases prior-authorization requirements and may restrict access to patients who demonstrate biochemical responsiveness, specialist supervision and compliance with phenylalanine-restricted dietary management.
Reimbursement remains fragmented across commercial insurance, government programs and national health systems, while coverage for medical formulas and low-protein foods varies substantially. SEPHIENCE generated US$151.3 million in second-quarter 2026 sales, demonstrating strong demand where access pathways are established, but not necessarily broad global affordability. Manufacturers must invest in prior-authorization assistance, bridge supply, co-pay support and payer evidence. Without consistent reimbursement, premium pricing could slow adoption in emerging markets, widen treatment disparities and limit uptake among patients requiring lifelong therapy, monitoring and specialized nutrition.
Phenylketonuria Treatment Market Segmentation Analysis
The global phenylketonuria treatment market is segmented based on the treatment approach, route of administration, patient age, disease severity, drug type, treatment intent, treatment setting, PAH responsiveness, distribution channel and region.
Pharmacological Therapies Anchor Current Revenues, While Genetic Platforms Define the Next Growth Cycle
Pharmacological therapy dominated the market in 2025, generating an estimated US$547 million, equivalent to approximately 68% of the global market. Leadership reflects established use of KUVAN and PALYNZIQ, complemented by the commercial launch of SEPHIENCE following its 2025 approvals. Oral therapies are gaining strategic importance because they support earlier intervention, broader age eligibility and potential dietary liberalization. Medical nutrition remains essential across all age groups, although its revenue growth is moderated by reimbursement fragmentation, product commoditization and increasing pharmacotherapy adoption.
Gene and genetic therapy is forecast to be the fastest-growing treatment approach, with an estimated 25.6% CAGR during 2026-2035, albeit from a limited commercial base. Gene replacement, base editing and liver-targeted platforms could deliver durable phenylalanine control and reduce dependence on lifelong dietary management. Among patient segments, children represent a structurally important population because newborn screening enables early treatment, while adolescents and adults offer expanding opportunities for treatment escalation. Future segment leadership will depend on clinical durability, neurocognitive outcomes, administration convenience, manufacturing scalability and payer acceptance of premium disease-modifying therapies.
Phenylketonuria Treatment Market Geographical Penetration
U.S. Phenylketonuria Treatment Market Landscape
The United States represents the commercial center of the global PKU treatment market, supported by universal newborn screening, established metabolic clinics, specialty-pharmacy infrastructure and comparatively strong reimbursement for orphan therapies. Treatment is evolving beyond lifelong phenylalanine restriction and medical nutrition toward response-guided pharmacotherapy. The FDA’s July 2025 approval of SEPHIENCE for sepiapterin-responsive patients aged one month and older materially broadened oral-treatment eligibility across pediatric and adult populations.
Commercial uptake confirms substantial demand for improved phenylalanine control and dietary flexibility. SEPHIENCE generated US$81 million of its US$92 million global revenue in the United States during Q4 2025, while PTC received 1,134 U.S. patient-start forms by year-end. The market should expand through broader PAH-responsiveness testing and earlier pharmacological intervention. However, premium pricing, prior authorization, variable medical-food coverage and limited access to metabolic specialists may constrain equitable adoption and long-term treatment persistence.
Canada Phenylketonuria Treatment Market Outlook
Canada represents an established but comparatively concentrated PKU market, supported by universal newborn screening, provincial metabolic clinics and sustained demand for medical formulas and low-protein foods. PKU incidence is estimated at approximately 1 in 15,000 births nationally, while Ontario reports around 1 in 12,000 newborns, creating a predictable population requiring lifelong management.
The treatment landscape is broadening beyond dietary control, sapropterin and PALYNZIQ. In December 2025, Health Canada listed SEPHIENCE for sepiapterin-responsive patients aged one month and older, establishing a new oral option with broad age eligibility. Commercial uptake will depend on provincial formulary decisions, PAH-responsiveness assessment and demonstrated dietary liberalization. Market growth should remain steady; however, fragmented reimbursement, uneven medical-food coverage and limited specialist capacity outside major urban centers may delay nationally consistent access to premium therapies.
Japan Phenylketonuria Treatment Market Outlook
Japan represents a small but strategically important PKU market, characterized by nationwide newborn screening, centralized metabolic-disease expertise and relatively low disease incidence. Management remains anchored in phenylalanine-restricted diets, specialized medical nutrition and sapropterin, while PALYNZIQ provides an enzyme-substitution option for patients aged 15 years and older with uncontrolled blood phenylalanine above 600 µmol/L.
The market’s competitive profile changed materially in December 2025, when Japan’s Ministry of Health, Labour and Welfare approved SEPHIENCE for children and adults across all ages and disease-severity categories. This broad label should expand response-guided oral treatment and increase demand for PAH-responsiveness assessment. Commercial growth will depend on National Health Insurance pricing, physician confidence, measurable dietary liberalization and long-term phenylalanine control. Japan’s limited patient pool restricts absolute revenue potential, but structured specialist care and centralized reimbursement can support rapid, disciplined adoption of clinically differentiated therapies.
Germany Phenylketonuria Treatment Market Trends
Germany is one of Europe’s most commercially relevant PKU markets, supported by established newborn screening, specialist metabolic centers and statutory health-insurance coverage. A 2026 claims-based analysis estimated PKU prevalence at approximately 6-8 patients per 100,000 insured individuals, equivalent to around 4,500-6,000 patients within the statutory insurance population.
Competition is shifting from dietary management and sapropterin toward therapies offering deeper phenylalanine reduction and meaningful dietary liberalization. Following European Commission authorization on 19 June 2025, Germany became the initial European launch market for SEPHIENCE, reflecting its strong reimbursement infrastructure and concentration of treatment-ready patients. Adoption will depend on PAH responsiveness, comparative benefit versus sapropterin, pricing negotiations and real-world dietary outcomes. Germany should remain an important evidence-generation market for response-guided oral therapy, PALYNZIQ use and emerging genotype-independent treatments.
Phenylketonuria Treatment Market Competitive Landscape
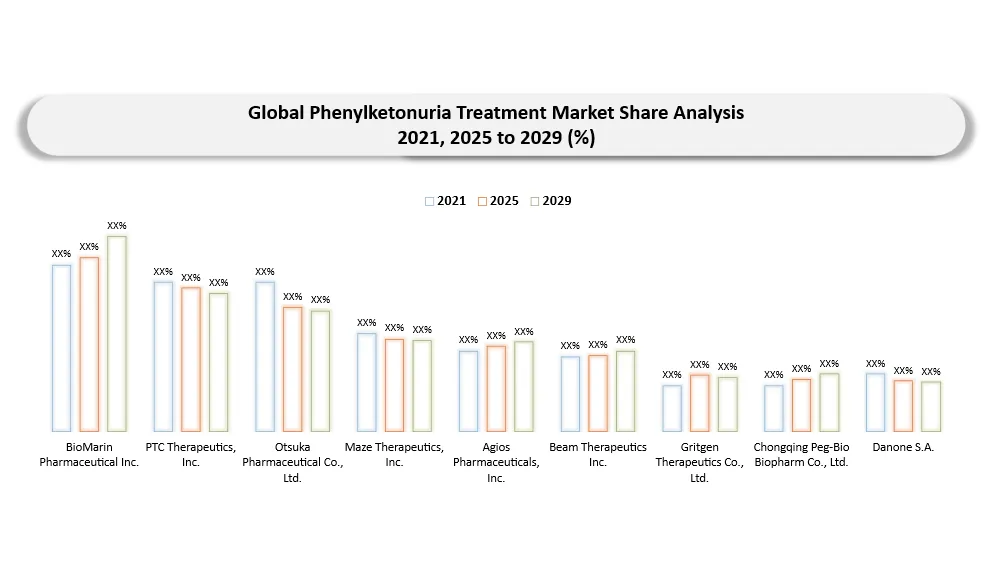
- The global PKU treatment market is concentrated around BioMarin Pharmaceutical and PTC Therapeutics, supported by differentiated commercial portfolios and established relationships with metabolic-treatment centers. BioMarin maintains a strong position through KUVAN and PALYNZIQ, covering cofactor-responsive patients and individuals requiring enzyme substitution. PTC has intensified competition through SEPHIENCE, whose broad age eligibility, oral administration and rapid commercial uptake strengthen its potential to reshape first-line pharmacological treatment. Competition increasingly centers on response breadth, phenylalanine reduction, dietary liberalization, safety, administration burden and payer access rather than product availability alone.
- Pipeline competition is broadening through Otsuka’s Phase III repinatrabit, Maze’s MZE782, Agios’ AG-181 and Beam’s BEAM-304 gene-editing program. These assets introduce transporter inhibition, PAH stabilization and potentially durable genetic correction, challenging established chronic-treatment models. Medical nutrition remains strategically important, with Danone, Nestlé, Ajinomoto and Abbott competing through amino-acid formulas, glycomacropeptide products and adherence-oriented formats. Future leadership will depend on broad genotype coverage, pediatric evidence, durable metabolic control, scalable manufacturing and real-world neurocognitive outcomes. Companies combining therapeutic innovation with diagnostic support, specialist engagement and reimbursement capabilities will capture disproportionate market value.
Key Companies of the Phenylketonuria Treatment Market
- BioMarin Pharmaceutical Inc. (United States)
- PTC Therapeutics, Inc. (United States)
- Otsuka Pharmaceutical Co., Ltd. (Japan)
- Maze Therapeutics, Inc. (United States)
- Agios Pharmaceuticals, Inc. (United States)
- Beam Therapeutics Inc. (United States)
- Gritgen Therapeutics Co., Ltd. (China)
- Chongqing Peg-Bio Biopharm Co., Ltd. (China)
- Danone S.A. (France)
- Nestlé S.A. (Switzerland)
- Abbott Laboratories (United States)
- Reckitt Benckiser Group plc (United Kingdom)
- Ajinomoto Co., Inc. (Japan)
- Relief Therapeutics Holding SA (Switzerland)
- Galen Limited (United Kingdom)
- metaX Institut für Diätetik GmbH (Germany)
- Dr. Schär AG (Italy)
- Lactalis Group (France)
- Firstplay Dietary Foods Limited (United Kingdom)
- Pristine Organics Pvt. Ltd. (India)
Phenylketonuria Treatment Market Major Pain Points
- Uneven Diagnosis and Patient Follow-Up: Newborn screening enables early PKU identification in developed healthcare systems, but coverage remains inconsistent across several emerging markets. Diagnosed patients may also become disconnected from metabolic care during adolescence or adulthood, resulting in undertreatment and poor phenylalanine control.
- Incomplete Lifelong Phenylalanine Control: Many patients struggle to maintain guideline-recommended blood phenylalanine concentrations despite dietary restriction, medical nutrition and pharmacotherapy. Persistent or fluctuating elevation increases the risk of executive-function impairment, psychological complications and reduced daily functioning.
- Heterogeneous Treatment Responsiveness: Differences in PAH genotype, residual enzyme activity, disease severity, age and baseline phenylalanine complicate response prediction. Sapropterin and sepiapterin require therapeutic evaluation, while PALYNZIQ eligibility and tolerability restrict its suitability for some patients.
- High Dietary and Adherence Burden: Lifelong protein restriction, medical formulas, food measurement and frequent monitoring create substantial practical and psychological burdens. Poor palatability, treatment fatigue and social limitations can weaken adherence, particularly among adolescents and adults.
- Limited Long-Term Patient-Relevant Evidence: Phenylalanine reduction is the principal regulatory endpoint, but comparative evidence demonstrating sustained neurocognitive, educational, psychological and quality-of-life benefits remains limited. This complicates treatment sequencing, payer assessment and differentiation among emerging therapies.
- Complex Pricing, Reimbursement and Access Requirements: Premium pharmacotherapies, specialized medical foods and lifelong monitoring create significant economic burden. Differences in insurance coverage, medical-nutrition reimbursement, specialist availability and prior-authorization criteria restrict equitable access across countries and patient populations.
Phenylketonuria Treatment Market Recent Developments
- August 2026: Maze Therapeutics initiated the Phase II CIPheR proof-of-concept trial of MZE782 in PKU, advancing the oral SLC6A19 inhibitor into patient-based evaluation of plasma phenylalanine reduction.
- July 2026: Agios Pharmaceuticals dosed the first patient in a Phase Ib trial of AG-181 in adults with PKU, marking the clinical advancement of a differentiated PAH-stabilization strategy.
- June 2026: The US FDA cleared Beam Therapeutics’ Investigational New Drug application for BEAM-304, enabling clinical development of a liver-targeted base-editing therapy designed to correct disease-causing PAH mutations.
- March 2026: Otsuka Pharmaceutical presented repinatrabit open-label extension data demonstrating clinically meaningful phenylalanine reductions in adolescents, strengthening the asset’s positioning within the global Phase III development program.
- February 2026: The US FDA approved PALYNZIQ for adolescents aged 12-17 years, expanding BioMarin’s original adult indication and increasing the addressable US treatment population.
- February 2026: PTC Therapeutics secured Brazilian approval for SEPHIENCE, extending its commercial footprint beyond the United States, Europe and Japan and strengthening its presence in Latin America.
- December 2025: Japan approved SEPHIENCE for children and adults across all ages and disease severities, establishing PTC Therapeutics’ first approved product in the Japanese market.
- December 2025: Gritgen Therapeutics received US FDA Orphan Drug Designation for GS1168, providing regulatory incentives for the development of its investigational AAV-based PKU gene therapy.
- October 2025: The US FDA accepted BioMarin’s supplemental Biologics License Application for PALYNZIQ under Priority Review, establishing the regulatory pathway for its subsequent adolescent indication expansion.
- July 2025: The US FDA approved SEPHIENCE for sepiapterin-responsive PKU patients aged one month and older, introducing a differentiated oral therapy across pediatric and adult populations.
Analyst View / Opinion on Phenylketonuria Treatment Market
- The market is shifting from lifelong dietary restriction toward differentiated pharmacotherapies that improve phenylalanine control, expand dietary flexibility and reduce the day-to-day burden of PKU management.
- SEPHIENCE expands the treatable population across age groups, while PALYNZIQ’s 2026 adolescent indication strengthens the commercial importance of earlier pharmacological intervention beyond adult-only treatment pathways.
- Treatment selection will increasingly depend on PAH responsiveness, baseline phenylalanine levels, age, disease severity, safety requirements and the degree of dietary liberalization achievable for each patient.
- Genotype-independent oral therapies, PAH stabilizers, gene editing and gene-replacement platforms could disrupt current care; however, durability, safety, manufacturing scalability and reimbursement will determine their commercial impact.
- Sustainable market leadership will require more than biochemical efficacy. Companies must demonstrate neurocognitive protection, improved quality of life, convenient administration, reliable medical-nutrition support and compelling long-term value for payers.
Phenylketonuria Treatment Market Target Audience
| INDUSTRY | WHO SHOULD BUY THIS REPORT? | REASON TO BUY THIS REPORT |
| Pharmaceutical and Biotechnology | PKU drug developers, commercial pharmaceutical companies and rare-disease biotechnology firms | Assess market potential, treatment gaps, competitive positioning and commercialization opportunities across approved and investigational PKU therapies. |
| Medical-Nutrition Companies | Manufacturers of low-protein foods, phenylalanine-free formulas, amino-acid mixtures and glycomacropeptide products | Evaluate medical-nutrition demand, patient preferences, product innovation, distribution channels and opportunities to reduce dietary burden. |
| Gene and Genetic-Therapy Developers | Gene-editing, gene-replacement, mRNA and liver-targeted platform companies | Benchmark emerging disease-modifying approaches, clinical-development requirements, durability expectations and competitive entry opportunities. |
| Diagnostics and Newborn-Screening Companies | Newborn-screening laboratories, molecular-diagnostic developers and clinical decision-support providers | Identify opportunities in early diagnosis, genotype characterization, PAH-responsiveness assessment, treatment selection and longitudinal monitoring. |
| Healthcare Providers | Metabolic specialists, geneticists, pediatricians, hospitals, metabolic clinics and specialty treatment centers | Understand treatment evolution, patient segmentation, therapy sequencing, dietary management and emerging standards of PKU care. |
| Payers and Market-Access Organizations | Health insurers, pharmacy-benefit managers, health-technology assessment bodies and reimbursement consultants | Evaluate treatment eligibility, reimbursement requirements, budget impact, outcomes evidence and access considerations for premium PKU therapies. |
| Patient Advocacy and Support Organizations | PKU associations, rare-disease foundations, caregiver groups and patient-support networks | Assess unmet needs relating to dietary burden, neurocognitive outcomes, treatment adherence, quality of life and equitable therapy access. |
| Government and Industry Bodies | Regulatory agencies, public-health authorities, newborn-screening programs and rare-disease organizations | Support screening policies, treatment-access frameworks, clinical guidelines, disease surveillance and national PKU-care strategies. |
| Investors and Financial Services | Private-equity firms, venture-capital investors, institutional investors and investment banks | Evaluate market attractiveness, pipeline value, clinical and regulatory risks, licensing opportunities and acquisition prospects across the PKU ecosystem. |
| Market Research and Consulting | Strategy consultancies, competitive-intelligence teams and market-research firms | Support market-entry planning, portfolio strategy, competitive benchmarking, opportunity assessment and commercial due diligence. |
| Research Organizations | Clinical research organizations, academic institutions, universities and translational research centers | Analyze clinical-trial activity, recruitment potential, biomarker development, PAH biology and remaining research gaps. |
| Distributors and Specialty Pharmacies | Specialty pharmacies, hospital pharmacies, medical-nutrition distributors and home-delivery providers | Assess distribution models, supply requirements, patient-support services and channel opportunities for medicines and medical foods. |
Why Choose DATAM?
- Data-Driven Insights: Access granular PKU intelligence covering market size, treatment-class shares, pricing, diagnosed and treated populations, medical-nutrition demand, clinical pipelines, competitive positioning and regional access dynamics, supported by primary interviews with industry experts.
- Post-Purchase Support and Expert Analyst Consultations: Engage directly with our healthcare analysts for customized guidance on patient segmentation, therapy responsiveness, treatment sequencing, portfolio positioning, market entry, competitor assessment and commercialization strategies.
- White Papers and Case Studies: Receive periodic insights on PKU treatment innovation, regulatory developments, product launches, dietary liberalization, medical-nutrition advancements, market-access strategies and evolving metabolic-specialist adoption patterns.
- Annual Updates on Purchased Reports: Stay informed through annual updates covering regulatory approvals, clinical readouts, pipeline changes, label expansions, licensing agreements, pricing developments and competitive shifts. Terms and conditions apply.
- Specialized Focus on Emerging Markets: Gain country-specific intelligence on newborn screening, diagnosed PKU populations, phenylalanine-control practices, treatment availability, medical-food reimbursement, metabolic-care infrastructure and commercial opportunities across high-growth emerging markets.
- Value of DataM Reports: Obtain tailored intelligence addressing specific business questions related to cofactor responsiveness, poorly controlled patients, therapy differentiation, dietary burden, treatment switching, pipeline disruption, market access and investment priorities beyond the information available through generic databases.
What DATAM Uniquely Provides
- In-depth segmentation of the phenylketonuria treatment market by treatment approach, route of administration, patient age, disease severity, drug type, treatment intent, treatment setting, PAH responsiveness, distribution channel and region.
- Competitive analysis of leading PKU companies covering phenylalanine reduction, treatment responsiveness, dietary liberalization, safety, mechanism of action, dosing convenience, pipeline maturity, medical-nutrition positioning and commercialization strategy.
- Comprehensive assessment of diagnosed and treatment-eligible populations, cofactor-responsive and nonresponsive patients, poorly controlled patients, age-based treatment eligibility, dietary burden, neurocognitive risk, unmet clinical needs and regional treatment-access dynamics.
- Actionable intelligence on pharmaceutical and medical-nutrition pricing, reimbursement, regulatory pathways, response assessment, treatment sequencing, patient-support programs, market-access barriers, licensing activity and investment opportunities.
- Analyst forecasts highlighting high-growth treatment approaches, commercially attractive patient populations, regional expansion opportunities and emerging competitive threats across oral therapies, enzyme substitution, specialized medical nutrition, transporter inhibitors, PAH stabilizers and genetic medicines.



























































