


Global Non Small-Cell Lung Cancer Market Overview
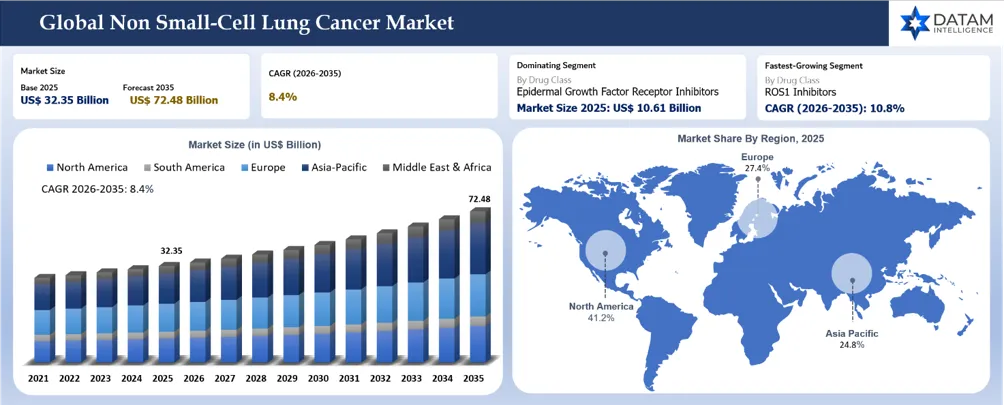
The global non small-cell lung cancer market reached US$32.35 billion in 2025 and is expected to reach US$72.48 billion by 2035, growing with a CAGR of 8.4% during the forecast period 2026-2035.
Growth is being shaped by the expanding diagnosed patient population, increasing treatment intensity, longer multi-line treatment pathways and wider access to molecular profiling. Demand is shifting from conventional chemotherapy toward biomarker-directed medicines and immune-checkpoint inhibitors across resectable, locally advanced and metastatic disease. EGFR inhibitors remain the leading drug class, supported by routine mutation testing and continued expansion into earlier treatment settings. However, late-stage diagnosis, incomplete biomarker testing, cumulative toxicity and acquired treatment resistance continue to restrict treatment eligibility, duration and clinical outcomes.
Precision oncology represents the market’s principal growth vector. Broader testing for EGFR, ALK, ROS1, BRAF, KRAS, MET, RET, NTRK and HER2 alterations is enabling smaller but higher-value addressable patient populations. Competitive advantage increasingly depends on mutation coverage, central nervous system activity, response durability, resistance management, combination potential and earlier-line positioning. The ability to translate clinical evidence into guideline inclusion, companion-diagnostic availability, reimbursement and broad treatment access will remain critical for commercial success.
The next value-creation cycle will centre on next-generation tyrosine kinase inhibitors, antibody-drug conjugates, bispecific antibodies and rational immunotherapy combinations. Sustainable leadership will require meaningful overall-survival improvements, manageable toxicity and scalable biomarker identification. Companies integrating drug development with companion diagnostics, real-world evidence, treatment-sequencing strategies and disciplined market-access programs will be best positioned to capture premium value and reshape the global NSCLC treatment landscape.
Global Non Small-Cell Lung Cancer Market Key Takeaways
- Sustained Market Expansion Through 2035: The global non-small cell lung cancer market was valued at USD 32.35 billion in 2025 and is projected to reach USD 72.48 billion by 2035, registering a CAGR of 8.4% during 2026-2035.
- EGFR Inhibitors Maintain Drug-Class Leadership: Epidermal growth factor receptor inhibitors accounted for an estimated 32.8% of the global market in 2025, equivalent to approximately USD 10.61 billion, supported by widespread EGFR testing and expanding treatment across early-stage and metastatic disease.
- ROS1 Inhibitors Represent the Fastest-Growing Drug Class: ROS1 inhibitors are projected to register a CAGR of approximately 10.8% through 2035, driven by broader genomic profiling, improved identification of ROS1-positive patients and adoption of next-generation therapies with central nervous system activity.
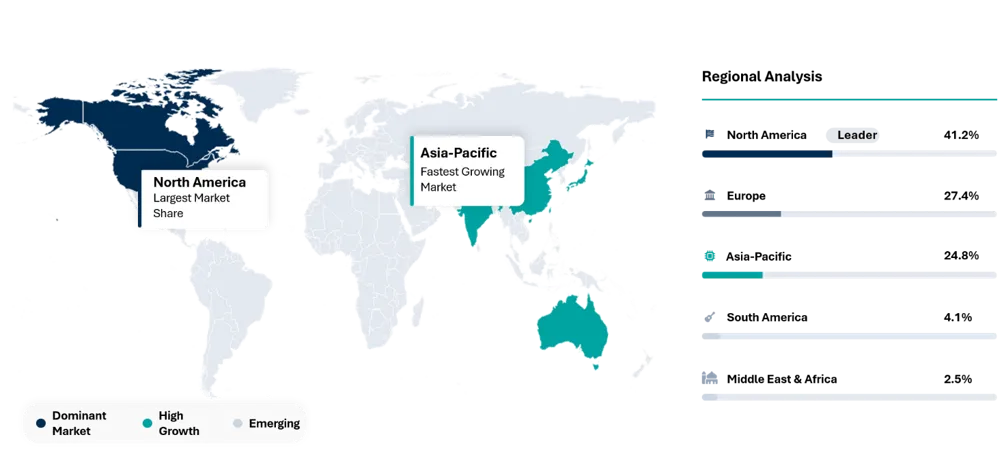
- North America Maintains Regional Dominance: North America accounted for an estimated 41.2% of the global market in 2025, equivalent to approximately USD 13.33 billion, supported by high treatment expenditure, comprehensive biomarker testing and rapid uptake of innovative therapies.
- Precision Oncology Reshapes Competitive Strategy: Market leadership will increasingly depend on biomarker-guided patient selection, earlier-stage treatment expansion and therapies addressing acquired resistance. Companies demonstrating durable survival benefits, manageable toxicity, companion-diagnostic integration and broad reimbursement access will be best positioned to capture market share.
Global Non Small-Cell Lung Cancer Market Scope
| Metrics | Details | |
| 2025 Market Size | US$32.35 Billion | |
| 2035 Projected Market Size | US$72.48 Billion | |
| CAGR (2026-2035) | 8.4% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Drug Class | Epidermal Growth Factor Receptor Inhibitors, Anaplastic Lymphoma Kinase Inhibitors, ROS1 Inhibitors, BRAF Inhibitors, Others | |
| By Type | Squamous Cell Carcinoma, Large Cell Carcinoma, Adenocarcinoma, Others | |
| By Treatment | Chemotherapy, Targeted Therapy, Immunotherapy | |
| By End-User | Hospitals, Homecare, Specialty Clinics, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Global Non Small-Cell Lung Cancer Market White Space & Investment Opportunities
- Earlier Detection and Risk-Based Patient Stratification: Invest in low-dose computed tomography, liquid biopsy, circulating tumour DNA, AI-enabled imaging and multi-omics risk models for high-risk populations. Detecting NSCLC before lymph-node involvement or distant metastasis can increase eligibility for curative surgery, stereotactic radiotherapy and perioperative systemic treatment.
- More Effective Perioperative and Recurrence-Prevention Therapies: Develop neoadjuvant, adjuvant and perioperative regimens that improve pathological response, eliminate micrometastatic disease and reduce postoperative recurrence. Opportunities remain for biomarker-guided treatment selection, shorter regimens and therapies suitable for patients unable to tolerate intensive chemotherapy.
- Next-Generation Therapies for Actionable Genomic Alterations: Advance treatments targeting EGFR, ALK, ROS1, KRAS, MET, RET, BRAF, NTRK and HER2 alterations. Significant whitespace remains in uncommon mutations, acquired resistance mechanisms, brain metastases and patients who progress following existing tyrosine kinase inhibitors. Companion diagnostics will be essential for identifying eligible populations.
- Immune-Resistance and Tumour-Microenvironment Modulation: Invest in bispecific antibodies, antibody-drug conjugates, cancer vaccines, novel checkpoint combinations and therapies targeting immune-excluded or immunologically cold tumours. These approaches could expand immunotherapy benefits beyond patients who respond adequately to established PD-1 and PD-L1 inhibitors.
- Treatment-Sequencing and Combination Evidence: Generate comparative evidence defining how chemotherapy, immunotherapy, targeted medicines, antibody-drug conjugates and emerging bispecific antibodies should be sequenced according to disease stage, histology, molecular profile, PD-L1 expression, central nervous system involvement and previous treatment.
- Geographic Testing Access and Outcome-Based Reimbursement: Expand comprehensive genomic profiling, specialist oncology access and reimbursement across underserved markets. Real-world evidence linking biomarker testing, earlier diagnosis, treatment durability, reduced hospitalization and quality-of-life improvement will be critical for supporting payer coverage and broader adoption.
Global Non Small-Cell Lung Cancer Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Overall Survival and Durability of Response
- Progression-Free Survival and Disease-Control Rate
- Objective Response and Pathological Response Rate
- Effectiveness by Disease Stage and Treatment Line
- Suitability for Squamous and Non-Squamous NSCLC
- Biomarker Eligibility, Including EGFR, ALK, ROS1, BRAF, KRAS, MET, RET, NTRK and HER2
- PD-L1 Expression Requirements and Immunotherapy Eligibility
- Activity Against Brain Metastases and Central Nervous System Progression
- Effectiveness Following Targeted-Therapy or Immunotherapy Resistance
- Safety, Tolerability and Long-Term Clinical Evidence
- Suitability for Older Patients and Patients With Comorbidities
- Route of Administration, Dosing Convenience and Treatment Burden
- Companion-Diagnostic and Comprehensive Genomic-Testing Requirements
- Hospitalization, Monitoring and Adverse-Event Management Requirements
- Improvement in Symptoms, Functional Status and Quality of Life
- Pricing, Reimbursement and Overall Treatment Cost
- Guideline Positioning, Regulatory Approval and Physician Experience
- Manufacturing Reliability, Geographic Availability and Patient-Support Services
Global Non Small-Cell Lung Cancer Market BCG Matrix: Company Evaluation
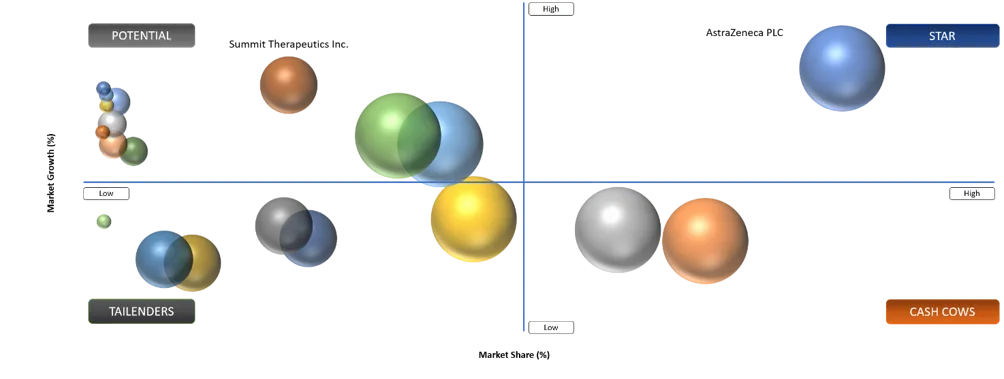
STAR
AstraZeneca PLC, Merck & Co., Inc., Bristol-Myers Squibb Company, Roche Holding Ltd and Johnson & Johnson are positioned in the Star category based on their extensive approved NSCLC portfolios, strong commercial reach and influence across treatment lines. AstraZeneca maintains leadership through TAGRISSO and IMFINZI, spanning biomarker-defined, unresectable and resectable NSCLC. Merck competes through KEYTRUDA, which is established across early-stage and metastatic disease. Bristol-Myers Squibb participates through OPDIVO-based regimens and AUGTYRO, while Roche offers ALECENSA, TECENTRIQ and other precision therapies. Johnson & Johnson has strengthened its position through RYBREVANT and LAZCLUZE for EGFR-mutated NSCLC.
Future leadership will depend on expansion into earlier disease stages, longer survival outcomes and effective management of treatment resistance. Companies combining broad immunotherapy franchises with biomarker-directed medicines, companion diagnostics and global clinical networks are positioned to retain competitive strength. Additional differentiation will come from central nervous system activity, subcutaneous formulations, simplified dosing, real-world evidence and payer-supported treatment sequencing.
POTENTIAL
Summit Therapeutics Inc., Revolution Medicines, Inc., BioNTech SE, Nuvation Bio Inc., AbbVie Inc., Daiichi Sankyo Company, Limited and Akeso, Inc. are positioned in the Potential category because of their emerging bispecific antibodies, RAS-directed medicines, antibody-drug conjugates and next-generation targeted therapies for biomarker-defined NSCLC populations.
Summit Therapeutics is advancing ivonescimab, a PD-1 and VEGF-targeting bispecific antibody, through global late-stage NSCLC development in partnership with Akeso. Revolution Medicines is evaluating daraxonrasib and zoldonrasib for RAS-driven cancers, including KRAS-mutated NSCLC. BioNTech is progressing pumitamig, a PD-L1 and VEGF-A bispecific antibody, while Nuvation Bio is commercializing IBTROZI for ROS1-positive NSCLC. AbbVie has entered biomarker-directed lung cancer treatment through EMRELIS for c-Met-overexpressing NSCLC. Daiichi Sankyo is expanding HER2-directed and antibody-drug conjugate opportunities through ENHERTU and its broader oncology pipeline. Progression toward the Star category will depend on Phase III validation, regulatory expansion, competitive survival outcomes, manageable toxicity, scalable manufacturing, biomarker-testing access and successful global commercialization.
Global Non Small-Cell Lung Cancer Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Expansion of Comprehensive Genomic Profiling and Actionable Biomarker Detection | 19.3% | High across North America, Europe, Japan and urban China; accelerating in other Asia-Pacific markets | Selection of therapies targeting EGFR, ALK, ROS1, KRAS, MET, RET, BRAF, NTRK and HER2 alterations | Expands the addressable population for precision medicines, increases companion-diagnostic utilization and supports biomarker-specific treatment sequencing |
Movement of Immunotherapy and Targeted Therapy Into Earlier-Stage NSCLC | 16.8% | Concentrated in markets with established screening, thoracic surgery and multidisciplinary oncology infrastructure | Neoadjuvant, adjuvant and perioperative treatment of resectable NSCLC and consolidation treatment of unresectable Stage III disease | Extends treatment duration, shifts commercial value beyond metastatic disease and intensifies competition for recurrence-prevention positioning |
Development of Therapies Addressing Acquired Resistance and Previously Underserved Mutations | 14.1% | Highest at specialized cancer centers and molecular tumor-board networks | Treatment following resistance to first-generation and next-generation tyrosine kinase inhibitors and immune-checkpoint inhibitors | Creates premium opportunities for next-generation inhibitors, antibody-drug conjugates and rational combination regimens |
Increasing Detection of Early-Stage and Advanced NSCLC Through Screening and Diagnostic Pathway Expansion | 11.8% | Strongest in the United States, Europe, Japan, South Korea and expanding Chinese screening networks | Identification of high-risk individuals, earlier-stage surgical candidates and patients requiring systemic treatment | Enlarges the diagnosed and treatable population while increasing demand for tissue biopsy, liquid biopsy, staging and longitudinal molecular monitoring |
Driver: Expansion of Comprehensive Genomic Profiling and Actionable Biomarker Detection
The expansion of comprehensive genomic profiling is reshaping the global non-small cell lung cancer market by converting molecular information into treatment decisions. Wider use of next-generation sequencing, liquid biopsy and multiplex testing enables clinicians to identify actionable alterations involving EGFR, ALK, ROS1, KRAS, MET, RET, BRAF, NTRK and HER2. This increases the number of patients eligible for targeted therapies, reduces dependence on trial-and-error treatment and supports more precise first-line and subsequent-line therapy selection across advanced and metastatic disease.
Commercially, biomarker detection expands addressable populations for medicines while improving development pathways for next-generation inhibitors, antibody-drug conjugates and resistance-focused combinations. Pharmaceutical companies are increasing partnerships with diagnostic laboratories, sequencing providers and networks to improve testing access and shorten turnaround times. However, market growth depends on tissue availability, reimbursement, laboratory capacity and consistent interpretation of genomic results. Companies that integrate companion diagnostics, clinician education and treatment access into launch strategies will secure adoption, patient identification and reinforce competitive positioning.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Acquired Resistance and Clonal Evolution Limiting Targeted-Therapy Durability | 16.8% | Treatment duration, progression-free survival and therapy sequencing | Patients developing resistance following EGFR, ALK, ROS1, KRAS, MET, RET or HER2-directed treatment | Shortens effective treatment duration, creates repeat-testing requirements and increases dependence on complex subsequent-line regimens |
Incomplete Biomarker Testing and Insufficient Tissue Samples Causing Treatment Misallocation | 14.5% | Patient identification, companion-diagnostic adoption and targeted-therapy utilization | Newly diagnosed advanced NSCLC patients requiring comprehensive molecular and PD-L1 testing | Leaves actionable alterations undetected, delays treatment initiation and reduces the eligible population for precision therapies |
Toxicity Burden and Comorbidity-Driven Exclusion From Intensive Treatment | 12.7% | Treatment eligibility, adherence, dose intensity and persistence | Older patients and those with poor performance status, pulmonary impairment, cardiovascular disease or autoimmune conditions | Restricts utilization of intensive immunotherapy and chemotherapy combinations while increasing discontinuation and monitoring requirements |
High Cumulative Treatment Cost and Fragmented Precision-Oncology Reimbursement | 10.9% | Market access, affordability and geographic treatment uptake | Patients requiring genomic testing, prolonged immunotherapy, targeted medicines or multidrug combinations | Generates reimbursement delays, unequal access and payer pressure for biomarker validation, treatment restrictions and outcomes-based agreements |
Restraint: Acquired Resistance and Clonal Evolution Limiting Targeted-Therapy Durability
Acquired resistance and clonal evolution represent major constraints on the durability of targeted therapies in non-small cell lung cancer. Although inhibitors directed against EGFR, ALK, ROS1, KRAS, MET, RET and HER2 can produce meaningful initial responses, tumour cells frequently develop secondary mutations, activate bypass signalling pathways or expand resistant subclones. Disease progression consequently shortens treatment duration, reduces long-term clinical benefit and forces patients into increasingly complex subsequent-line regimens with lower response probability.
This adaptability creates commercial uncertainty by limiting product longevity within treatment lines and fragmenting demand across multiple biomarker-defined resistance mechanisms. Pharmaceutical companies must invest in repeat tissue biopsies, liquid biopsy monitoring and next-generation sequencing to identify emerging alterations and guide therapy selection. It also increases development pressure for next-generation inhibitors, antibody-drug conjugates, bispecific antibodies and rational combinations capable of delaying or overcoming resistance. Market expansion will therefore depend on therapies demonstrating durable systemic and central nervous system activity, manageable toxicity and clear sequencing advantages within personalized treatment pathways.
Segment Analysis
The global non-small-cell lung cancer market is segmented based on type, treatment, end-user, and region.
The Chemotherapy Segment is Expected to Hold a Dominant Position in the Market Over the Forecast Period
The chemotherapy segment accounted for the highest market stake accounting for approximately 45.1% of the non-small-cell lung cancer market in 2022. Surgery is still the most common form of treatment for people with stage IB, stage II, and stage IIIA non-small cell lung cancer, despite the fact that there have been numerous advancements for patients with metastatic disease.
The U.S. Food and Drug Administration (FDA) approved KEYTRUDA, Merck's anti-PD-1 therapy, as a single agent in January 2023 for adjuvant Treatment following surgical resection and platinum-based chemotherapy for adult patients with stage IB (T2a 4 centimeters [cm]), II, or IIIA non-small cell lung cancer (NSCLC).
Global Non Small-Cell Lung Cancer Market Geographical Penetration
U.S. Non Small-Cell Lung Cancer Market Landscape
The United States represents the largest national market for non-small cell lung cancer therapies, supported by substantial disease burden, advanced molecular testing and rapid adoption of precision oncology. The American Cancer Society projects 229,410 new lung cancer cases in 2026, while NCI SEER estimates 124,990 lung-and-bronchus cancer deaths. Although these figures include all lung cancer types, NSCLC constitutes the dominant clinical segment, creating sustained demand for surgery, radiotherapy, immunotherapy, targeted medicines and comprehensive genomic profiling across community and academic oncology settings.
Market competition is concentrated among companies with checkpoint-inhibitor and biomarker-directed franchises, including Merck, AstraZeneca, Bristol Myers Squibb, Roche, Pfizer and Johnson & Johnson. Growth is shifting from metastatic treatment toward neoadjuvant, adjuvant and consolidation settings, expanding populations and treatment duration. Commercial performance increasingly depends on detecting EGFR, ALK, ROS1, KRAS, MET, RET and HER2 alterations, securing payer coverage and demonstrating survival advantages. However, unequal screening uptake, incomplete biomarker testing, therapy resistance and high treatment costs constrain access. Manufacturers that integrate companion diagnostics, evidence-based sequencing and patient-support programs will be best positioned to capture value across the U.S. care pathway.
Japan Non Small-Cell Lung Cancer Market Outlook
Japan represents a strategically important non-small cell lung cancer market, supported by a substantial ageing population, universal health coverage and strong adoption of molecularly guided treatment. Japan’s National Cancer Center projected 130,100 new lung cancer cases and 77,800 deaths in 2025, demonstrating the continuing clinical burden. Although these statistics cover all lung cancers, NSCLC accounts for most diagnosed cases. Demand is consequently concentrated around EGFR, ALK, ROS1, RET, MET, BRAF, KRAS and HER2 testing, alongside PD-L1 assessment, surgery, radiotherapy, targeted medicines and immune-checkpoint inhibitors.
Japan’s treatment landscape is differentiated by a high prevalence of EGFR-mutated lung adenocarcinoma, making genomic profiling and tyrosine kinase inhibitors central to commercial strategy. AstraZeneca, Roche, Takeda, Pfizer, Novartis, Merck, Bristol Myers Squibb and Johnson & Johnson compete through targeted and immuno-oncology portfolios. Growth opportunities are shifting toward perioperative therapy, resistance-focused combinations, liquid biopsy and treatments with central nervous system activity. However, price revisions, reimbursement assessment, regional disparities in genomic testing and treatment tolerability among older patients constrain value capture. Companies aligning local clinical evidence, companion diagnostics and market-access strategies will be positioned to expand adoption.
Global Non Small-Cell Lung Cancer Market Competitive Landscape
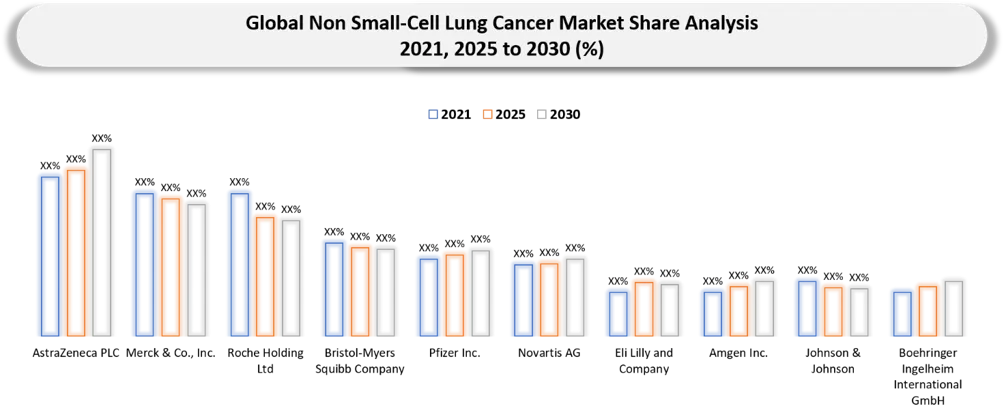
- The global non-small cell lung cancer market is highly competitive, led by multinational pharmaceutical companies with established immunotherapy and targeted-therapy franchises. AstraZeneca, Merck & Co., Roche, Bristol-Myers Squibb, Pfizer, Novartis, Eli Lilly, Amgen and Johnson & Johnson maintain strong positions through broad product portfolios, extensive clinical evidence and global commercialization capabilities. Competition increasingly centers on biomarker-defined populations, including EGFR, ALK, ROS1, KRAS, MET, RET, BRAF and HER2 alterations, alongside PD-1 and PD-L1 immunotherapies used across early-stage, locally advanced and metastatic disease. Market leadership is strengthened by label expansion, combination regimens and movement of therapies into earlier treatment settings.
- Emerging competition is being shaped by antibody-drug conjugates, bispecific antibodies, next-generation tyrosine kinase inhibitors and therapies designed to overcome acquired resistance. Daiichi Sankyo, AbbVie, Gilead Sciences, BeOne Medicines and GSK are expanding their positions through differentiated pipelines, licensing agreements and strategic collaborations. Competitive success will increasingly depend on superior survival outcomes, manageable safety profiles, central nervous system activity, convenient dosing and companion-diagnostic availability. Companies must also demonstrate value to payers as treatment sequencing becomes more complex. Partnerships between drug developers and diagnostic companies will therefore remain critical for patient identification, clinical adoption and commercial differentiation.
Key Companies of Non Small-Cell Lung Cancer Market
- AstraZeneca PLC (United Kingdom)
- Merck & Co., Inc. (United States)
- Roche Holding Ltd (Switzerland)
- Bristol-Myers Squibb Company (United States)
- Pfizer Inc. (United States)
- Novartis AG (Switzerland)
- Eli Lilly and Company (United States)
- Amgen Inc. (United States)
- Johnson & Johnson (United States)
- Boehringer Ingelheim International GmbH (Germany)
- Daiichi Sankyo Company, Limited (Japan)
- Takeda Pharmaceutical Company Limited (Japan)
- Regeneron Pharmaceuticals, Inc. (United States)
- Sanofi (France)
- Merck KGaA (Germany)
- AbbVie Inc. (United States)
- Gilead Sciences, Inc. (United States)
- BeOne Medicines Ltd. (Switzerland)
- Bayer AG (Germany)
- GSK plc (United Kingdom)
Global Non Small-Cell Lung Cancer Market Recent Developments
- September 2026: BioNTech reported that the Phase III PRESERVE-003 trial of gotistobart achieved a statistically significant overall-survival improvement compared with docetaxel in patients with previously treated squamous non-small cell lung cancer. The results strengthen the company’s oncology pipeline and could establish a differentiated chemotherapy-free treatment option in a population with limited effective therapies.
- September 2026: The U.S. FDA granted accelerated approval to Bayer’s sevabertinib for metastatic nonsquamous non-small cell lung cancer harboring HER2 tyrosine-kinase-domain activating mutations. The approval expands targeted treatment options for HER2-mutated disease and increases the commercial importance of comprehensive genomic profiling for identifying eligible patients.
- September 2026: Nuvalent presented results from the ARROS-1 study showing that zidesamtinib generated a 94% objective response rate and 100% intracranial response rate in TKI-naïve patients with advanced ROS1-positive non-small cell lung cancer. The findings support potential first-line expansion and intensify competition among next-generation, brain-penetrant ROS1 inhibitors.
- August 2026: The U.S. FDA granted Fast Track designation to BlossomHill Therapeutics’ BH-30643 for advanced EGFR C797S-positive non-small cell lung cancer following treatment with a third-generation EGFR inhibitor. The designation highlights increasing investment in therapies addressing acquired EGFR resistance and supports accelerated development of treatments offering mutant selectivity and central nervous system penetration.
- August 2026: AstraZeneca discontinued a Phase III trial evaluating volrustomig combined with chemotherapy after a planned analysis determined that the study was unlikely to meet its efficacy objectives. The setback demonstrates the clinical-development risk associated with next-generation checkpoint combinations and reinforces the need for biomarker-enriched patient-selection strategies.
- July 2026: The U.S. FDA approved Nuvalent’s JIDEYTRO (zidesamtinib) for adults with locally advanced or metastatic ROS1-positive non-small cell lung cancer previously treated with at least one ROS1 tyrosine kinase inhibitor. The approval introduces a differentiated targeted therapy designed to address resistance mutations and intracranial disease in a small but commercially valuable molecular subgroup.
- July 2026: The U.S. FDA approved the first generic version of afatinib, referencing Boehringer Ingelheim’s GILOTRIF, for eligible patients with EGFR-mutated metastatic non-small cell lung cancer. Generic entry could improve treatment accessibility and create pricing pressure within the EGFR-inhibitor segment, although adoption will be moderated by continued migration toward later-generation therapies.
- June 2026: Pfizer reported that the Phase III trial of sigvotatug vedotin did not achieve a statistically significant overall-survival improvement in previously treated nonsquamous non-small cell lung cancer. The outcome highlights the development risk facing antibody-drug conjugates in biomarker-unselected populations and increases the strategic importance of predictive biomarkers and optimized combination regimens.
What DATAM Uniquely Provides
- Granular Market Segmentation: In-depth segmentation of the global non-small cell lung cancer market by cancer type, disease stage, treatment type, drug class, mechanism of action, route of administration, treatment line, patient age group, care setting, distribution channel and region.
- Clinical and Competitive Benchmarking: Competitive assessment of leading NSCLC companies and therapies covering overall survival, progression-free survival, objective response rate, response durability, intracranial efficacy, safety, mechanism of action, biomarker positioning, dosing convenience, pipeline maturity, regulatory status and commercialization strategy.
- Patient Population and Treatment-Eligibility Analysis: Comprehensive evaluation of diagnosed and treatment-eligible populations across resectable, locally advanced and metastatic NSCLC. The analysis assesses adenocarcinoma, squamous-cell carcinoma and large-cell carcinoma populations alongside treatment-naïve, previously treated, refractory and relapsed patients.
- Precision-Oncology and Market-Access Intelligence: Actionable intelligence on EGFR, ALK, ROS1, KRAS, BRAF, MET, RET, NTRK and HER2 alterations; PD-L1 expression; companion diagnostics; comprehensive genomic profiling; therapy sequencing; pharmaceutical pricing; reimbursement; regulatory pathways; patient-support programs and regional access barriers.
- Forward-Looking Opportunity Assessment: Analyst forecasts identifying high-growth drug classes, commercially attractive molecular subgroups, regional expansion opportunities and emerging competitive threats across chemotherapy, immune-checkpoint inhibitors, targeted therapies, antibody-drug conjugates, bispecific antibodies, cancer vaccines and resistance-directed therapies.





























































