


Industrial Waste Management Market Size and Overview
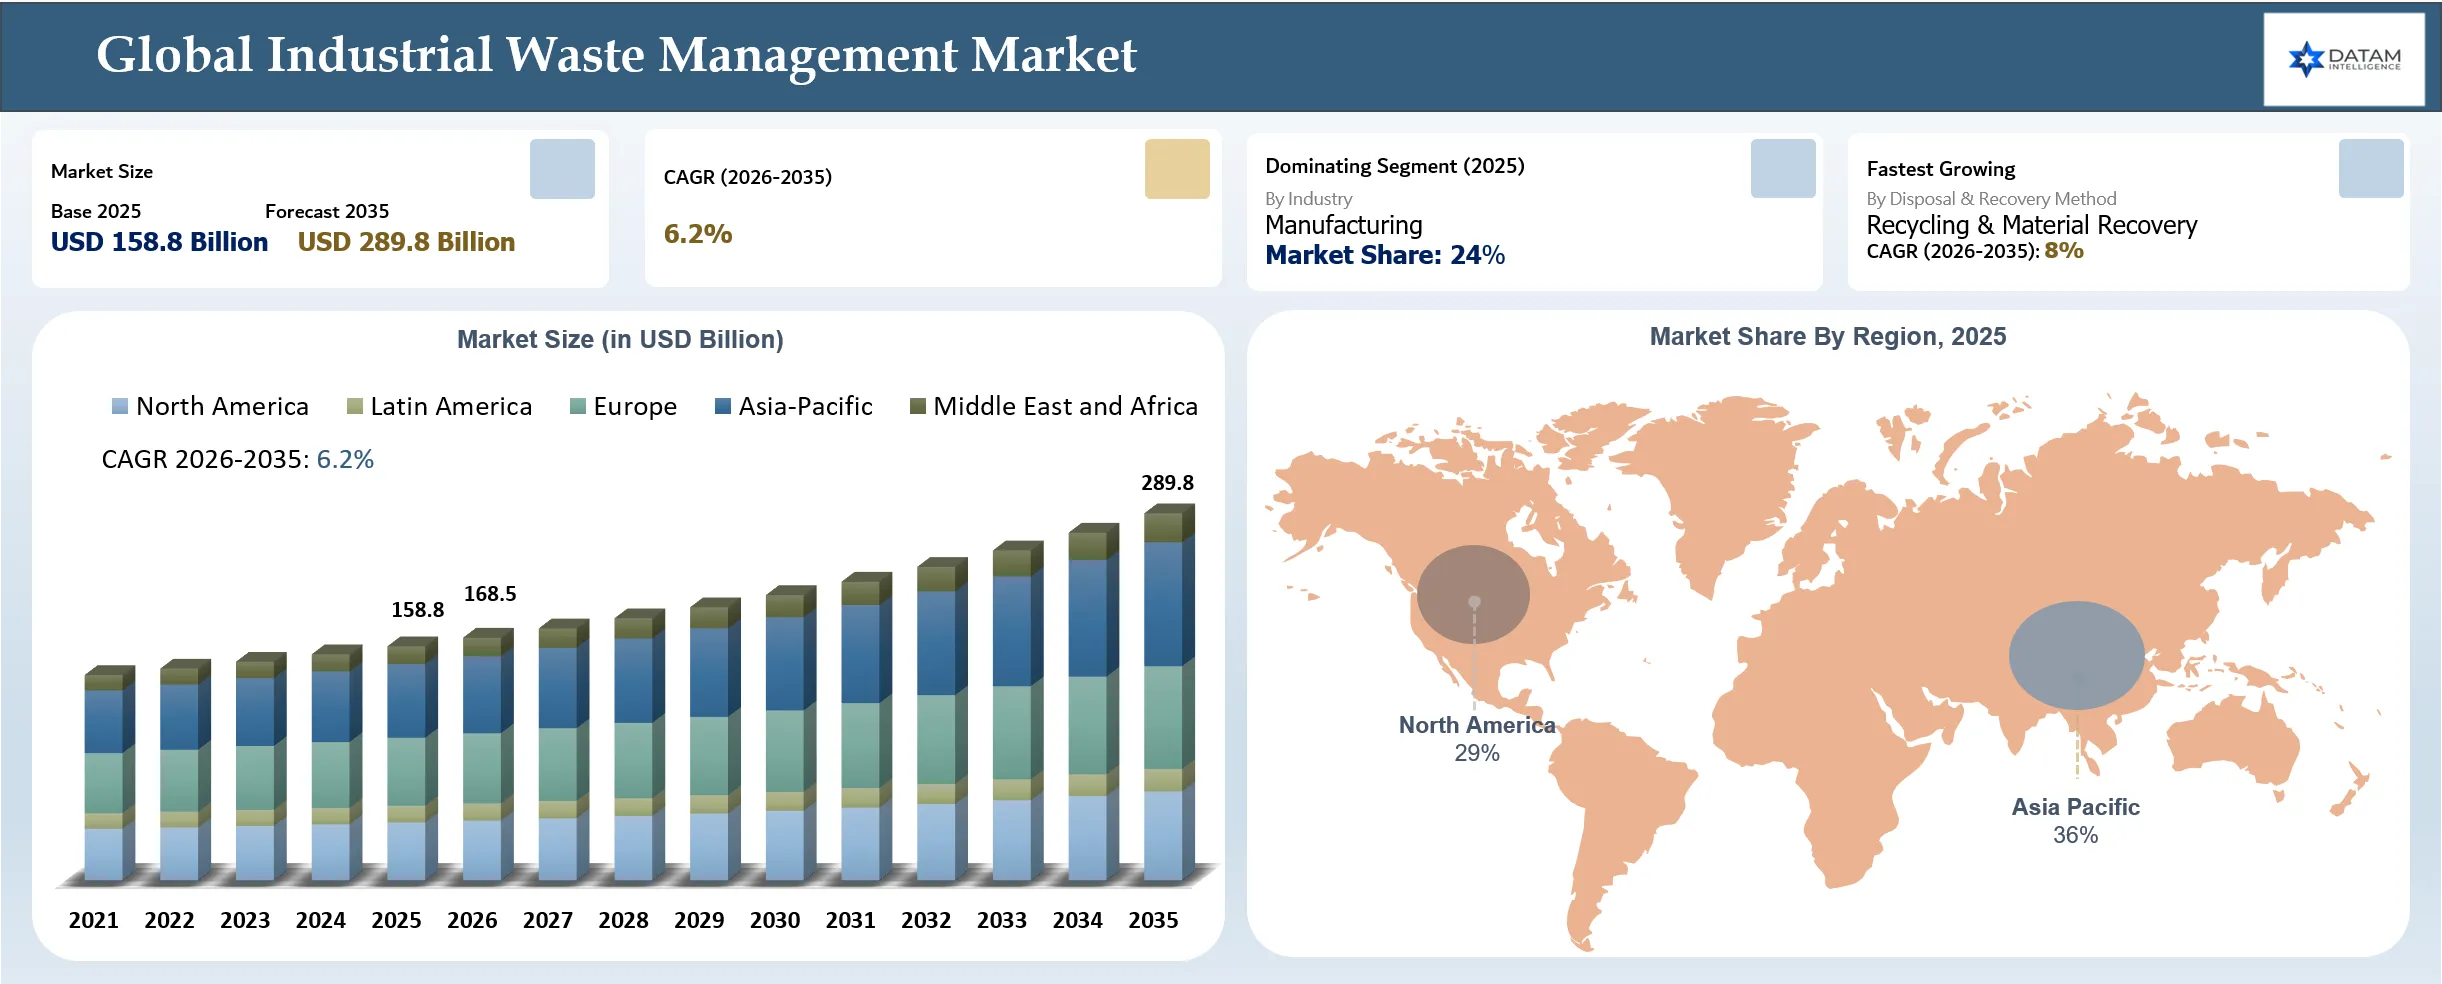
The global industrial waste management market was valued at US$158.8 billion in 2025 and is projected to reach US$289.8 billion by 2035, growing at a CAGR of 6.2% during 2026–2035. The industrial waste management market is driven by rapid growth in industrial waste generation, tightening environmental and hazardous-waste regulations, increasing adoption of recycling and resource recovery, a growing emphasis on the circular economy and waste minimization, and rising demand for specialized treatment and disposal infrastructure.
The growing volume of industrial waste is creating substantial demand for organized waste collection, treatment, recycling, and disposal services. According to World Bank 9.2 billion tonnes of industrial waste are generated worldwide each year, including more than 2 billion tonnes classified as municipal solid waste. Only 13.5% of total industrial waste produced globally is estimated to be recyclable, increasing the need for improved waste recovery and treatment solutions. Nation such as UK generates 41.1 million tonnes of industrial waste annually, further increasing demand for industrial waste management infrastructure and services.
Increasing investments in specialized waste-processing infrastructure are expanding industrial waste treatment and recovery capacity. New depackaging facilities also help waste generators improve material separation and divert recoverable materials from disposal. For instance, in September 2026, LJP Waste Solutions announced the opening of its new DePack Processing Facility in North Mankato, Minnesota. The facility expands the company’s waste-processing capacity for municipal, commercial, and industrial customers across southern Minnesota and surrounding areas.
Public-Sector and Utility Digitalization Initiatives Supporting Advanced Electricity Grid Digital Twin Applications
Stricter hazardous-waste requirements are increasing demand for specialized identification, storage, transportation, treatment, tracking, and disposal services. Under the U.S. EPA's RCRA framework, Large Quantity Generators (LQGs) are facilities generating 1,000 kg or more of hazardous waste per month and generally may accumulate hazardous waste on-site for only 90 days without a permit. LQGs must also use compliant containers, tanks, drip pads, or containment buildings, follow hazardous-waste manifest requirements, maintain emergency procedures and employee training, and submit biennial reports.
Stricter EU waste-shipment regulations are creating additional demand for compliant waste management and recycling infrastructure. The EU Waste Shipment Regulation (EU) 2024/1157, applicable from May 2026, introduces digital tracking through DIWASS, tighter controls on hazardous-waste shipments, and stronger requirements for cross-border waste movements. The regulation also restricts plastic-waste exports to non-OECD countries, increasing opportunities for domestic and intra-EU treatment, recycling, and recovery services.
Industrial Waste Management Market Strategic Takeaways
- Asia Pacific held the largest regional market share, accounting for approximately 36% of the global industrial waste management market in 2025, supported by rapid industrialization, expanding manufacturing activities, increasing waste volumes, stricter environmental regulations, and investments in waste treatment and resource recovery infrastructure.
- Manufacturing held the largest industry market share, accounting for approximately 24% of the global industrial waste management market in 2025, driven by high volumes of process waste, increasing production activities, stricter waste-management requirements, and growing adoption of recycling and resource-recovery practices.
- Recycling & material recovery is projected to be the fastest-growing disposal & recovery method, registering an estimated CAGR of 8.0% during 2026–2035, driven by increasing circular-economy initiatives, demand for recovered materials, regulatory pressure to reduce landfill disposal, and investments in resource recovery infrastructure.
- Advanced waste treatment and resource recovery are reshaping industrial waste management, enabling industries to reduce disposal volumes, recover valuable materials, and improve compliance with increasingly stringent environmental requirements.
- Industrial decarbonization and circular-economy initiatives are expanding recovery applications, as manufacturers and other industrial operators increasingly integrate recycling, material recovery, waste-to-energy, and other resource-efficient practices into waste-management strategies.
Industrial Waste Management Market Industry Trends and Strategic Insight
- Industrial waste management providers are shifting from conventional collection and disposal toward integrated waste management models that combine collection, storage, treatment, recycling, recovery, and disposal services, enabling industrial customers to manage multiple waste streams through a single service provider.
- Digitalization, IoT, and automated monitoring are increasingly being integrated into waste management operations to track waste volumes, container levels, collection routes, treatment processes, and material recovery, improving operational visibility and resource utilization.
- Growing emphasis on recycling and resource recovery is driving investment in material sorting, chemical recovery, industrial by-product reuse, waste-to-energy, and other recovery processes, reducing dependence on landfill disposal and creating additional value from industrial waste streams.
- Circular-economy initiatives and waste minimization are encouraging manufacturers to redesign waste-handling processes, increase material recovery, and develop closed-loop systems that return recovered metals, plastics, chemicals, and other materials into production processes.
- Advanced waste-processing technologies such as automated sorting, AI-based waste identification, depackaging, advanced thermal treatment, and biological treatment are expanding the ability of waste-management operators to process heterogeneous industrial waste and improve recovery rates.
- Regulatory traceability and compliance are becoming increasingly important, particularly for hazardous waste, driving demand for digital manifests, waste tracking, documentation, environmental reporting, and integrated compliance-management services.
- Waste-management companies are expanding on-site and decentralized services at industrial facilities, including waste segregation, temporary storage, treatment, dewatering, and recovery, allowing customers to reduce waste transportation requirements and improve handling efficiency.
Industrial Waste Management Market Scope
| Metrics | Details | |
| 2025 Market Size | USD 158.8 Billion | |
| 2035 Projected Market Size | USD 289.8 Billion | |
| CAGR (2026-2035) | 6.2% | |
| Largest Market | Asia-Pacific | |
| Fastest Growing Market | Asia-Pacific | |
| By Service Type | Collection & Transportation, Waste Storage, Waste Treatment, Waste Disposal, Recycling & Resource Recovery, Wastewater & Sludge Management, Consulting & Compliance Services, Others | |
| By Waste Treatment Method | Physical Treatment, Chemical Treatment, Biological Treatment, Thermal Treatment, Others | |
| By Waste Type | Hazardous Waste, Non-Hazardous Waste | |
| By Disposal & Recovery Method | Landfilling, Incineration, Recycling & Material Recovery, Composting & Biological Recovery, Waste-to-Energy, Other Disposal & Recovery Methods | |
| By Industry | Manufacturing, Chemicals & Petrochemicals, Oil & Gas, Mining & Metals, Food & Beverage, Pharmaceuticals & Healthcare, Automotive, Power Generation & Utilities, Construction, Pulp & Paper, Electronics & Semiconductors, Others | |
| By End-User | Electric Utilities, Grid Infrastructure Operators, Others | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, United Kingdom, France, Italy, Spain, Netherlands, Switzerland, Sweden, Norway, Denmark, Belgium, Poland, Austria, Ireland, Portugal, Greece, Finland, and Rest of Europe. | |
| Asia-Pacific | China, Japan, India, South Korea, Australia, New Zealand, Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines, Taiwan, and Rest of Asia Pacific. | |
| Latin America | Brazil, Argentina, Rest of Latin America | |
| Middle East and Africa | UAE, Saudi Arabia, South Africa, Israel, Türkiye, Rest of Middle East and Africa | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Industrial Waste Management Market Disruption Analysis
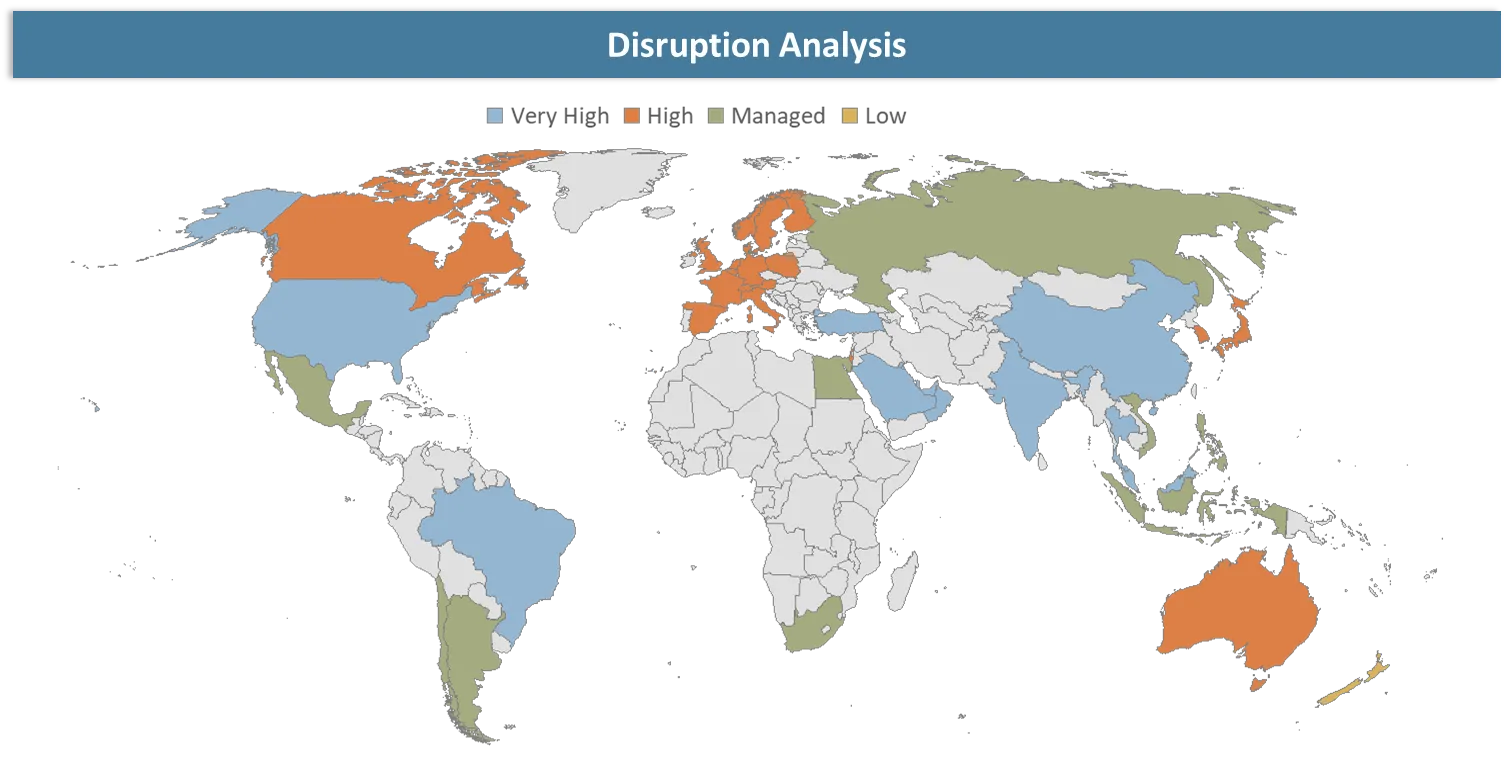
Shift from Conventional Waste Disposal Toward Integrated Resource Recovery and Digitally Managed Waste Operations
The industrial waste management market is shifting from conventional collection, transportation, and disposal models toward integrated waste management and resource recovery systems. Industrial facilities and waste-management providers are increasingly combining waste segregation, storage, treatment, recycling, material recovery, and waste-to-energy processes to reduce landfill dependence and recover value from industrial waste streams. This transition is changing demand from basic disposal services toward specialized solutions capable of handling hazardous waste, industrial sludge, chemicals, metals, plastics, and other complex waste streams.
Digital technologies are further disrupting waste-management operations through IoT-enabled monitoring, automated sorting, AI-based waste identification, digital tracking, and route optimization. These technologies enable operators to monitor waste volumes, container levels, collection schedules, treatment processes, and recovered materials, improving operational efficiency and traceability.
Industrial Waste Management Market BCG Matrix: Company Evaluation
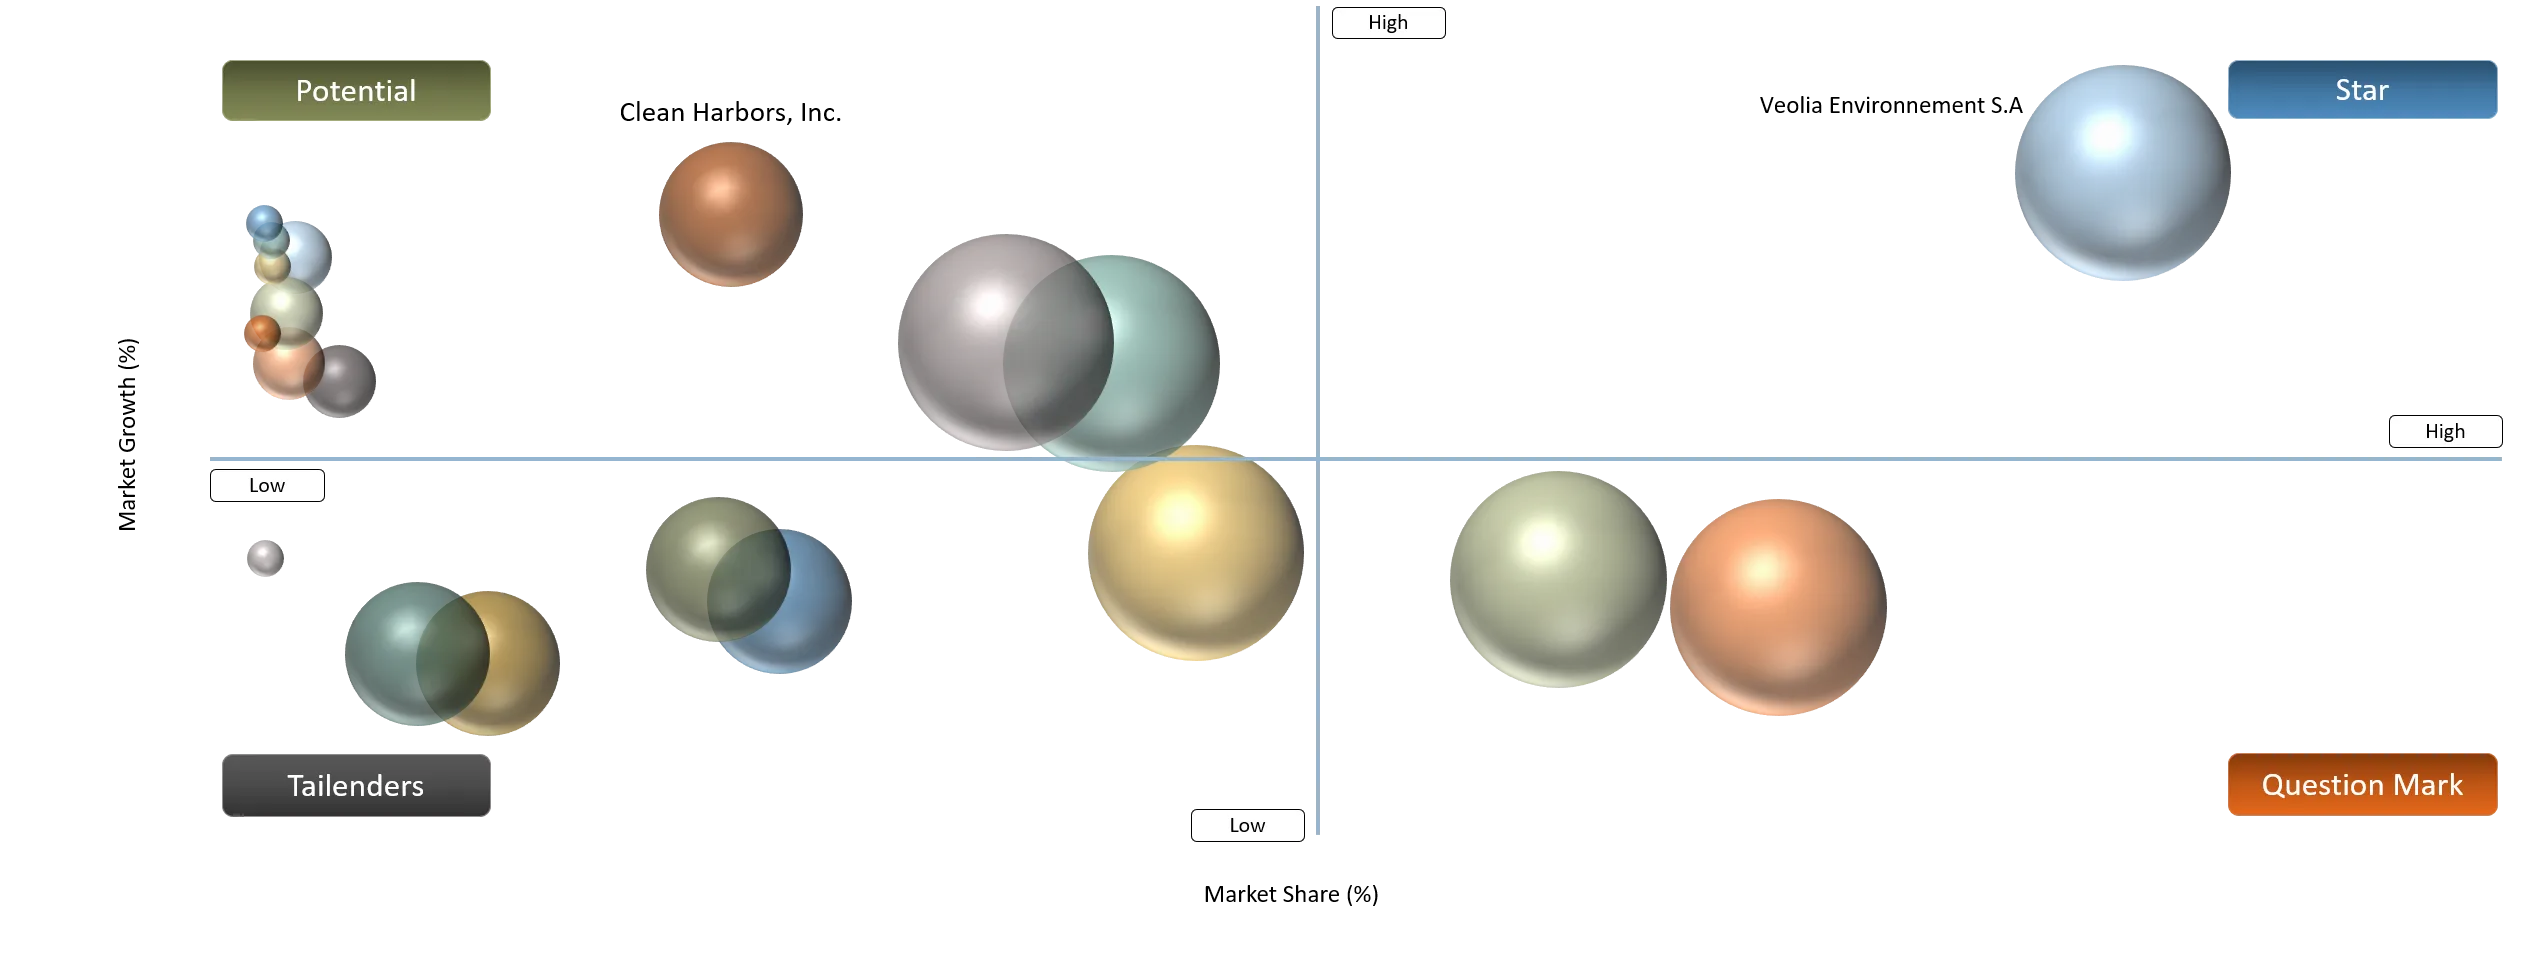
Veolia Environnement S.A., SUEZ S.A., Waste Management, Inc. (WM), and Republic Services are positioned as Stars, supported by broad industrial waste management portfolios, extensive collection and treatment networks, strong recycling and resource recovery capabilities, and established customer relationships. Waste Connections, Inc., Clean Harbors, Inc., and GFL Environmental Inc. are positioned as Potential Stars, reflecting strong waste treatment, hazardous-waste management, recycling, and regional service capabilities with opportunities for continued expansion.
Daiseki Co., Ltd., Sims Limited, and Biffa plc are positioned as Question Marks, supported by established recycling, resource recovery, and industrial waste management capabilities, while their geographic or service focus is more specialized. Casella Waste Systems, Inc. and Averda Holdings International Limited are positioned as Tailenders, reflecting more concentrated regional operations compared with larger diversified global waste management providers.
Industrial Waste Management Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Areas | Strategic Impact |
Rising Industrial Waste Generation from Manufacturing Expansion | 30% | Strong demand across Asia-Pacific, North America, and Europe, particularly in China, India, the U.S., Japan, and Germany, where manufacturing and processing activities generate large volumes of industrial waste. | Manufacturing plants, chemical facilities, metal processing, automotive, food processing, electronics, industrial parks | Increases demand for collection, transportation, storage, treatment, recycling, and disposal services as industrial waste volumes expand. |
Stricter Hazardous-Waste and Environmental Regulations | 25% | High demand across North America, Europe, and Asia-Pacific, where governments are strengthening hazardous-waste handling, tracking, treatment, disposal, and reporting requirements. | Hazardous-waste treatment, storage facilities, industrial compliance, waste transportation, environmental monitoring | Drives outsourcing to specialized providers with permitted facilities, regulatory expertise, compliant transportation, digital tracking, and documented treatment and disposal processes. |
Growing Adoption of Recycling and Resource Recovery | 20% | Strong demand across Europe, China, Japan, North America, and India, supported by circular economy policies and industrial resource-efficiency programs. | Material recovery, metal recycling, plastic recycling, chemical recovery, industrial by-product reuse, waste-to-energy | Shifts demand from disposal-focused services toward recycling, recovery, reuse, and conversion of industrial waste into secondary materials, fuels, and energy. |
Expansion of Specialized Waste Treatment Infrastructure | 15% | Demand is concentrated in industrial regions with large chemical, pharmaceutical, manufacturing, mining, and energy sectors, including China, India, the U.S., Germany, Japan, and Southeast Asia. | Hazardous waste, industrial sludge, chemical waste, contaminated materials, wastewater, thermal treatment | Encourages investment in treatment, storage, disposal, incineration, biological treatment, and advanced processing facilities capable of handling complex waste streams. |
Increasing Focus on Waste Minimization and Circular Economy | 10% | Strong demand across Europe, Japan, China, North America, and other markets adopting waste-reduction and circular production policies. | Industrial by-products, packaging waste, plastics, metals, process residues, production waste | Supports closed-loop material use, industrial symbiosis, waste reduction, resource recovery, and higher-value recycling models that reduce dependence on disposal. |
Growing Adoption of Pollution Prevention and Waste Reduction in Manufacturing Facilities
Manufacturers are increasingly adopting pollution prevention and source-reduction measures to minimize waste generation and improve resource efficiency. Programs such as the U.S. EPA's Toxics Release Inventory (TRI) Program support this shift by tracking pollution prevention activities at industrial facilities. According to 2024 TRI data released in 2025, 1,681 facilities, representing about 8% of TRI-reporting facilities, implemented 3,405 source-reduction activities during 2024, including process modifications, equipment improvements, material substitution, and better material management.
Manufacturers are also investing in solvent recovery and material reuse technologies to reduce hazardous waste generation and lower waste-management costs. For instance, GEOTEK, a coatings manufacturer, invested in solvent-recovery systems during 2022 to 2024 to recover and reuse acetone and lacquer thinner, resulting in a 71% reduction in hazardous coating waste between 2022 and 2023 and approximately 70% lower hazardous-waste disposal costs, while the company continued expanding its recovery systems in 2024.
Industrial Waste Management Market Segment Analysis
The global industrial waste management market is segmented based on waste type, waste treatment method, service type, application, disposal & recovery method,industry and region.
Recycling & Material Recovery Emerges as a Leading Industrial Waste Management Method
Recycling & material recovery is a leading industrial waste-management method, supported by the increasing emphasis on resource efficiency and recovery of valuable materials. The U.S. EPA TRI National Analysis reported that facilities managed 34.6 billion pounds of TRI-listed chemical waste in 2023, with recycling increasing by 7.0 billion pounds, or 49%, from 2014 to 2023.
Furthermore, advanced recycling technologies are gaining adoption to recover valuable materials from hard-to-recycle waste streams. These solutions support resource recovery and circular production. For instance, in March 2025, Resynergi and Lummus Technology commercially launched Resynergi Modules, modular 5-tonne-per-day pyrolysis systems designed to convert hard-to-recycle plastic waste into circular pyrolysis oil.
Industrial Waste Management Market Geographical Penetration
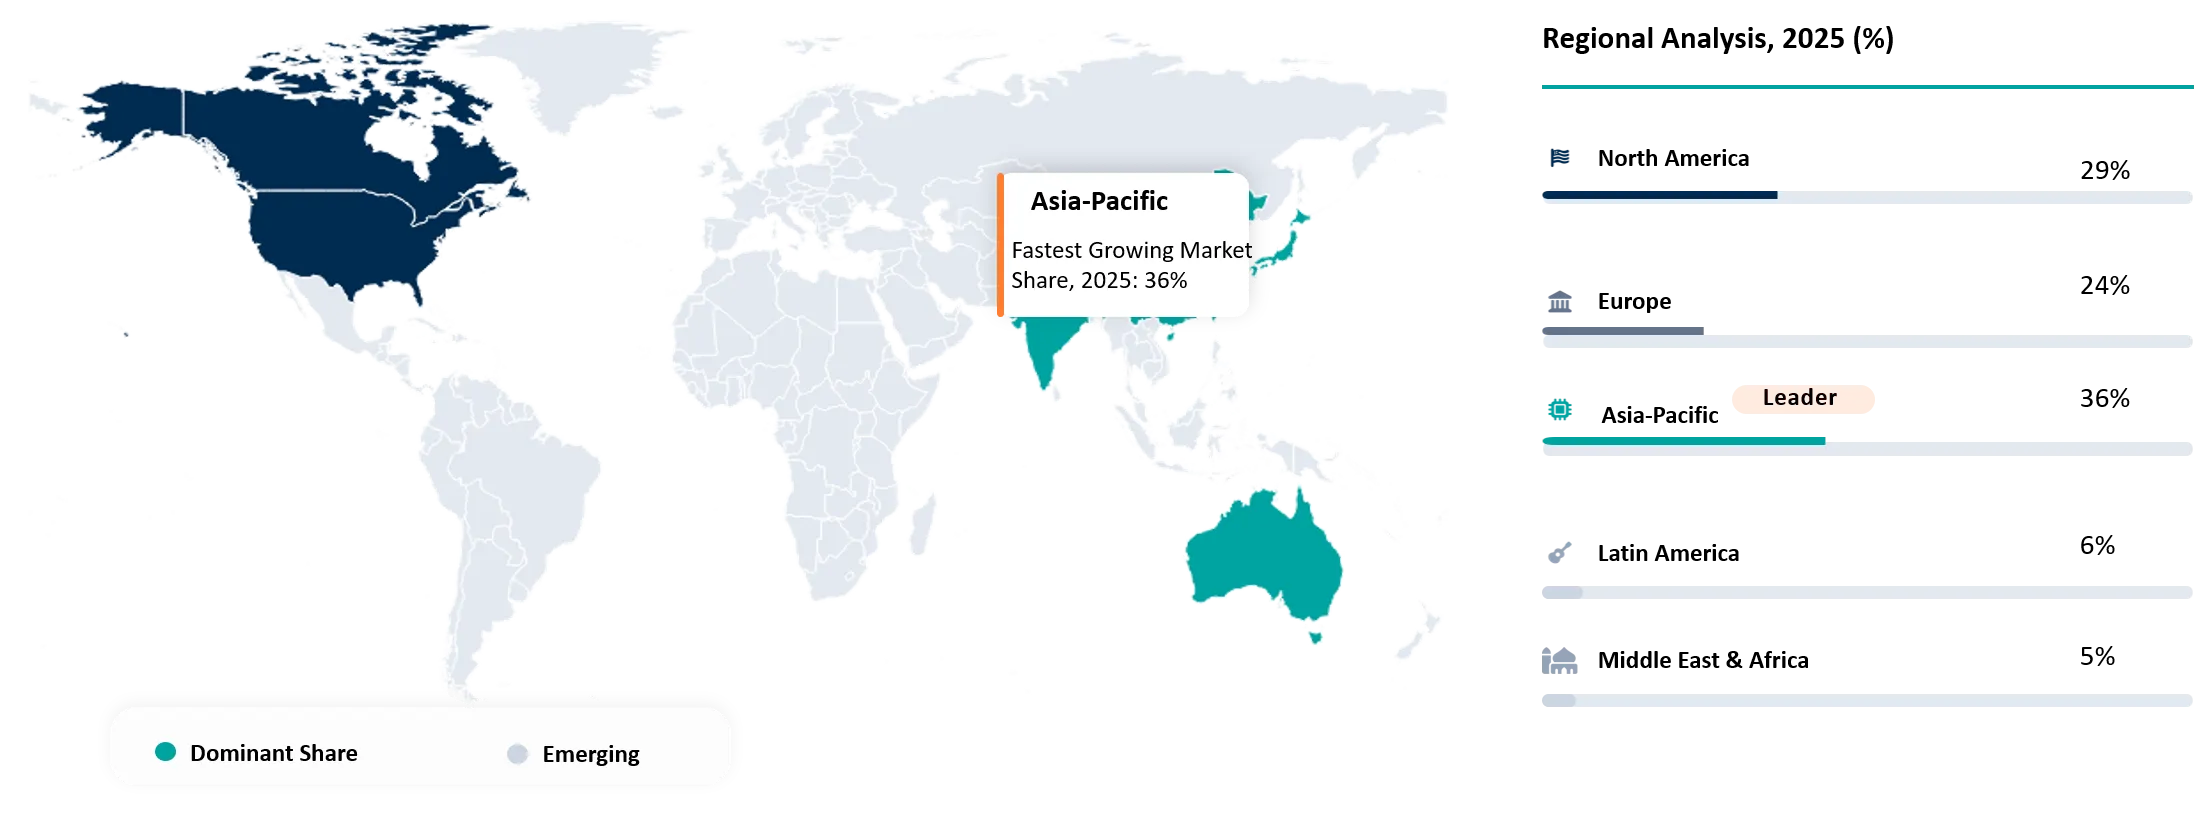
Strong Regulatory Framework and Growing Recycling Activities Drive the North American Market
North America’s industrial waste management market is driven by stringent environmental regulations, rising industrial waste generation, and growing adoption of recycling and resource recovery practices. Industries are increasingly investing in advanced treatment, waste minimization, and recovery technologies to improve compliance, reduce disposal volumes, and recover valuable materials.
Canada’s industrial waste management market is supported by substantial pollutant generation and increasing recycling and treatment activities. In 2024, facilities reported 5.47 million tonnes of substances to the NPRI, with approximately 2.15 million tonnes, or 67%, disposed of or transferred off-site for recycling and treatment. The Prairie region accounted for 42% of national pollutant releases, followed by Québec and Ontario at 39%.
U.S. Industrial Waste Management Market Trends
The U.S. industrial waste management market is driven by stringent environmental regulations, increasing industrial waste generation, and growing adoption of recycling and resource recovery practices. The U.S. generates 600 million tonnes of industrial waste annually from diverse sectors. Chemical manufacturing produces 200 million tonnes primarily organic chemicals and petrochemicals.
According to the U.S. Environmental Protection Agency (EPA), more than 21,000 industrial and federal facilities reported TRI data in 2024 covering chemical releases, waste management, and pollution prevention activities. In addition, 1,681 facilities implemented 3,405 new source-reduction activities during 2024 to reduce chemical waste generation.
Asia-Pacific Industrial Waste Management Market Driven by Industrial Expansion and Resource Recovery
Asia-Pacific is a major industrial waste management market, supported by rapid industrialization, manufacturing expansion, large-scale infrastructure development, and increasing government focus on waste recycling, resource recovery, and hazardous-waste control. China, India, Japan, South Korea, and Southeast Asian economies have large manufacturing and processing industries that generate substantial volumes of industrial solid waste, hazardous waste, sludge, and other industrial residues.
In countries like China waste-management policies target annual utilization of 4 billion tonnes of bulk solid waste by 2025 and annual use of 450 million tonnes of major renewable resources such as scrap steel, copper, aluminum, lead, zinc, paper, plastics, rubber, and glass.
India Industrial Waste Management Market Trends
India represents a significant industrial waste management market, supported by expanding manufacturing activity, a large base of hazardous-waste-generating industries, stricter environmental requirements, and investment in common treatment and disposal infrastructure. According to the Central Pollution Control Board (CPCB), during 2023–24, India generated approximately 18.51 million tonnes of hazardous waste from 89,301 authorized hazardous-waste-generating units. Of this volume, 38.50% was recyclable, 37.96% utilizable, 19.23% landfillable, and 4.31% incinerable, creating demand for specialized recycling, treatment, recovery, and disposal services.
Japan Industrial Waste Management Market Trends
Japan’s industrial waste management market is driven by strong recycling practices, stringent waste-management regulations, and increasing focus on resource recovery and waste reduction. Japan generates approx. 400 million tonnes of industrial waste annually from advanced manufacturing. Electronics industry produces 150 million tonnes from semiconductor and computer production. Automotive sector generates 100 million tonnes from vehicle manufacturing and parts production.
Companies across Japan are investing in large-scale recycling facilities to process waste plastics and recover valuable materials. For instance, in March 2025, J Circular System began preparations for the full-scale operation of one of Japan’s largest plastic recycling facilities in Kawasaki. The facility can process approximately 200 tonnes of used plastics per day, including industrial waste, using integrated sorting and recycling processes.
Industrial Waste Management Market Competitive Landscape
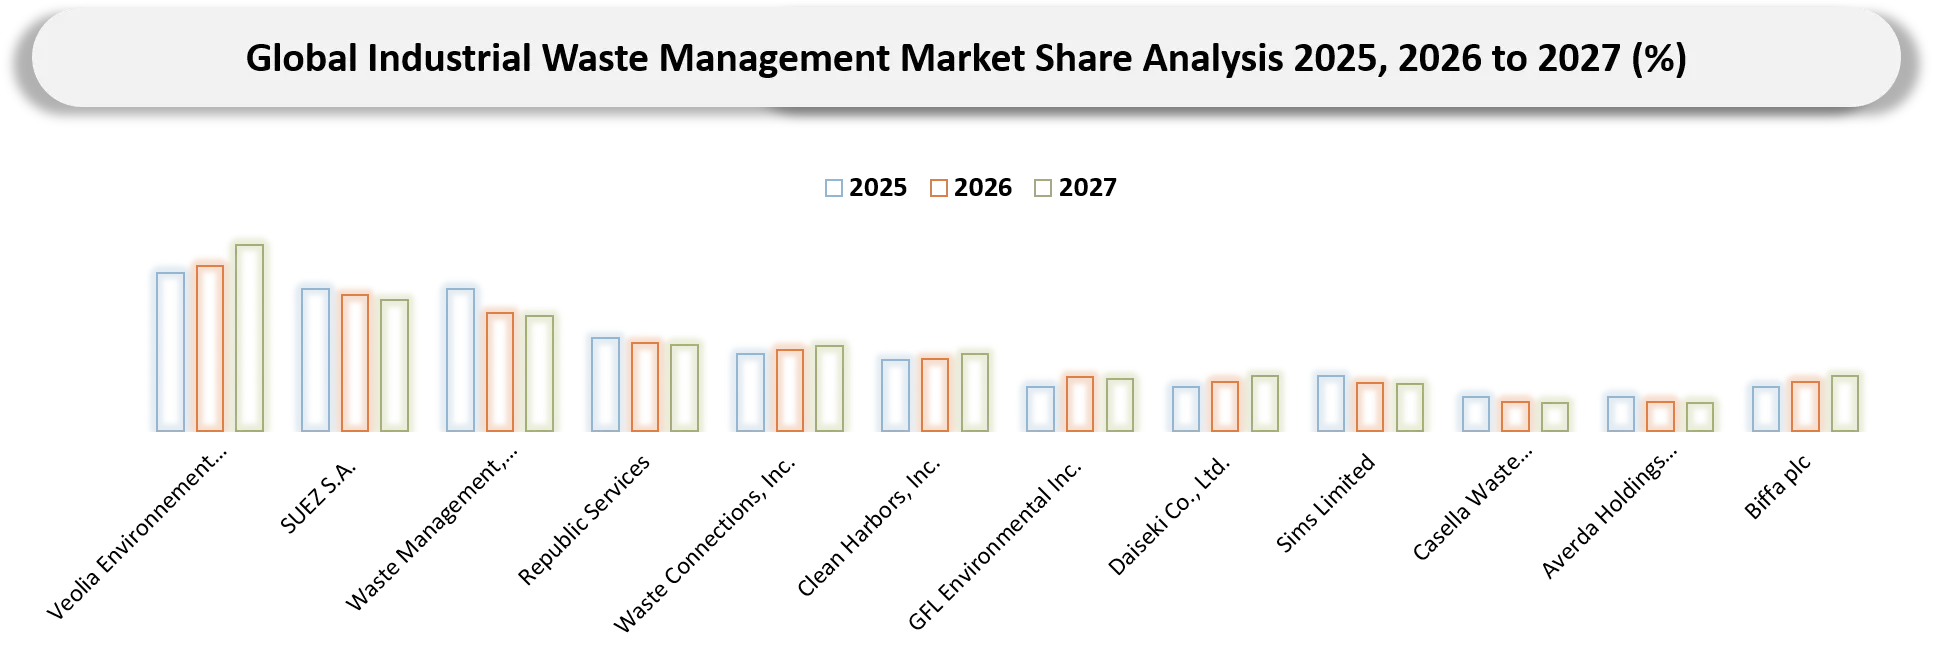
- The global industrial waste management market comprises service providers specializing in industrial waste collection, transportation, storage, hazardous waste management, waste treatment, recycling and resource recovery, waste disposal, wastewater and sludge management, and environmental remediation. Key participants include Veolia Environnement S.A., SUEZ S.A., Waste Management, Inc. (WM), Republic Services, Waste Connections, Inc., Clean Harbors, Inc., GFL Environmental Inc., Daiseki Co., Ltd., Sims Limited, Casella Waste Systems, Inc., Averda Holdings International Limited, and Biffa plc.
- Veolia Environnement S.A. (France), SUEZ S.A. (France), Waste Management, Inc. (WM) (United States), Republic Services (United States), Waste Connections, Inc. (United States/Canada), Clean Harbors, Inc. (United States), GFL Environmental Inc. (Canada), Daiseki Co., Ltd. (Japan), Sims Limited (Australia), Casella Waste Systems, Inc. (United States), Averda Holdings International Limited (United Arab Emirates), and Biffa plc (United Kingdom) represent key participants across the global Industrial Waste Management Market.
Key Developments
- September 2026: LJP Waste Solutions announced the opening of its new DePack Processing Facility in North Mankato, Minnesota. The facility expands the company’s waste-processing capacity for municipal, commercial, and industrial customers across southern Minnesota and surrounding areas.
- June 2026: Technip Energies, Alterra, and Neste launched Nerea™, a standardized modular solution for chemical recycling of plastic waste. The solution combines Alterra’s thermochemical liquefaction technology, Neste’s chemical recycling expertise, and Technip Energies’ engineering and modularization capabilities to convert difficult-to-recycle plastic waste into feedstock for the petrochemical industry.
- March 2026: Neste commissioned a EUR 111 million upgrading facility at its Porvoo refinery in Finland to process up to 150,000 tonnes of liquefied waste plastic annually. The facility, the world’s largest of its kind, upgrades pyrolysis oil and other liquefied waste plastics from difficult-to-recycle streams such as multilayer packaging, mixed plastics, and contaminated plastics into high-quality petrochemical feedstock. Production ramp-up began in 2026.
- March 2025: Resynergi and Lummus Technology commercially launched Resynergi Modules, modular 5-tonne-per-day pyrolysis systems designed to convert hard-to-recycle plastic waste into circular pyrolysis oil.
- March 2025: J Circular System began preparations for the full-scale operation of one of Japan’s largest plastic recycling facilities in Kawasaki. The facility can process approximately 200 tonnes of used plastics per day, including industrial waste, using integrated sorting and recycling processes.
Key Procurement Priorities and Buyer Evaluation Criteria
- Industrial waste management buyers prioritize regulatory compliance, waste handling capacity, treatment effectiveness, recycling and recovery capabilities, hazardous-waste expertise, environmental performance, traceability, and reliable service across manufacturing facilities, industrial plants, chemical facilities, and processing operations.
- Evaluation is based on criteria such as waste classification capabilities, collection and transportation infrastructure, storage capacity, treatment technologies, recycling and resource recovery rates, disposal options, environmental monitoring, digital waste tracking, regulatory compliance, emergency response, and integration with facility operations.
- Industrial companies, manufacturers, chemical producers, refineries, mining companies, food-processing facilities, and infrastructure operators consider factors including service cost, treatment and disposal charges, collection frequency, facility proximity, permitting requirements, waste volumes, customization, contract flexibility, vendor reliability, reporting capabilities, and total cost of waste management.
- Preference is given to providers with permitted treatment and disposal facilities, established hazardous and non-hazardous waste management capabilities, broad recycling and recovery networks, specialized treatment technologies, strong regulatory expertise, and experience managing complex industrial waste streams.
- Manufacturing plants, chemical and petrochemical facilities, pharmaceutical companies, automotive manufacturers, metal-processing facilities, food and beverage producers, and other industrial waste generators particularly prioritize solutions that reduce disposal volumes, increase material recovery, minimize environmental risks, improve regulatory compliance, and provide reliable end-to-end waste management.
Why Choose DataM?
- Waste Management & Treatment Analysis: Examines developments across industrial waste collection, transportation, storage, treatment, disposal, recycling, resource recovery, wastewater and sludge management, hazardous waste management, and environmental remediation. The analysis evaluates how treatment technologies and integrated services improve waste diversion, recovery, compliance, and operational efficiency.
- Industry & Waste Stream Analysis: Evaluates industrial waste management requirements across manufacturing, chemicals and petrochemicals, automotive, pharmaceuticals, food and beverage, metals and mining, energy and utilities, electronics, construction, and other industrial sectors. The analysis identifies service requirements according to waste type, generation volume, hazardous characteristics, treatment requirements, and regulatory conditions.
- Real-World Industry Evidence: Tracks waste treatment facility investments, recycling plant expansions, hazardous-waste infrastructure, waste-to-energy projects, depackaging facilities, resource recovery initiatives, technology deployments, service contracts, and strategic partnerships across major markets. The analysis incorporates developments from waste management companies, industrial manufacturers, recyclers, utilities, and environmental service providers.
- Competitive Landscape & Provider Strategies: Analyzes how leading providers strengthen their positions through treatment and disposal capacity expansion, recycling and resource recovery, hazardous-waste specialization, digital waste tracking, facility acquisitions, geographic expansion, strategic partnerships, and integrated waste management services.
- Pricing & Procurement Analysis: Evaluates industrial waste management pricing based on waste type, volume, hazardous characteristics, collection frequency, transportation distance, treatment method, disposal requirements, recycling value, facility location, regulatory requirements, and service scope. The analysis also considers storage, treatment, compliance, monitoring, reporting, and total service costs.
- Market Entry & Growth Opportunities: Identifies opportunities arising from rising industrial waste generation, stricter hazardous-waste regulations, circular economy initiatives, resource recovery, industrial recycling, waste minimization, expansion of treatment infrastructure, digital waste tracking, and increasing demand for specialized waste treatment and disposal services.
Target Audience
- Industrial Waste Management and Environmental Service Providers
- Manufacturing Companies and Industrial Facilities
- Chemical and Petrochemical Companies
- Pharmaceutical and Life Sciences Manufacturers
- Automotive and Automotive Component Manufacturers
- Metals, Mining and Mineral Processing Companies
- Food and Beverage Processing Companies
- Electronics and Semiconductor Manufacturers
- Energy and Utility Companies
- Engineering, Procurement and Construction (EPC) Companies
- Recycling and Resource Recovery Companies
- Waste Treatment, Disposal and Environmental Remediation Providers



























































