


Epilepsy Drug Market Size and Overview
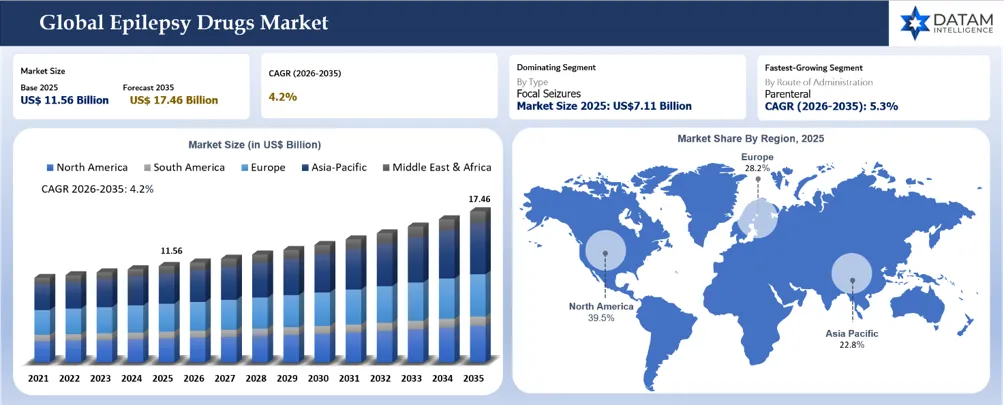
The global epilepsy drugs market reached US$11.56 billion in 2025 and is expected to reach US$17.46 billion by 2035, growing with a CAGR of 4.2% during the forecast period 2026-2035.
Market growth is being shaped by the persistent burden of epilepsy, improved neurological diagnosis, expanding access to specialist care and continued demand from patients with drug-resistant seizures. Focal seizures represent the market’s largest treatment category, supported by chronic therapy requirements and the extensive use of levetiracetam, lamotrigine, lacosamide, topiramate and newer differentiated medicines. However, treatment failure, adverse effects, polytherapy-related interactions and poor adherence continue to limit seizure control. These challenges create opportunities for therapies offering differentiated mechanisms, improved tolerability, convenient dosing and sustained seizure reduction.
Precision neurology represents an important growth vector. Wider genetic testing is improving the identification of Dravet syndrome, CDKL5 deficiency disorder, SCN2A-related epilepsy, KCNT1-related epilepsy and other developmental and epileptic encephalopathies. Competitive advantage will increasingly depend on genetically targeted treatment, pediatric indication expansion, durable clinical response, developmental outcomes and access to specialist epilepsy centers. Antisense oligonucleotides and gene-regulating therapies may gradually shift treatment from symptomatic seizure suppression toward disease modification.
The next value-creation cycle will center on Kv7 potassium-channel modulators, precision medicines for rare genetic epilepsies, non-invasive seizure-rescue formulations and therapies capable of reducing polytherapy dependence. Sustainable leadership will require clinically meaningful seizure freedom, manageable safety, scalable manufacturing and payer-supported access. Companies integrating drug development with genetic diagnostics, patient registries, real-world evidence and disciplined market-access strategies will be best positioned to influence treatment sequencing and capture premium market value.
Epilepsy Drugs Market Key Takeaways
- Steady Market Expansion Through 2035: The global epilepsy drugs market reached US$11.56 billion in 2025 and is projected to reach US$17.46 billion by 2035, registering a CAGR of 4.2% during 2026-2035.
- Focal Seizures Maintain Market Leadership: Focal seizures accounted for an estimated 61.5% of the global market in 2025, equivalent to approximately US$7.11 billion, supported by high diagnosis rates, chronic treatment requirements and extensive branded and generic drug availability.
- Parenteral Therapies Represent the Fastest-Growing Segment: Parenteral administration is expected to record an estimated 5.3% CAGR through 2035, driven by demand for rapid seizure control, status epilepticus management and intravenous therapy when oral administration is unsuitable.
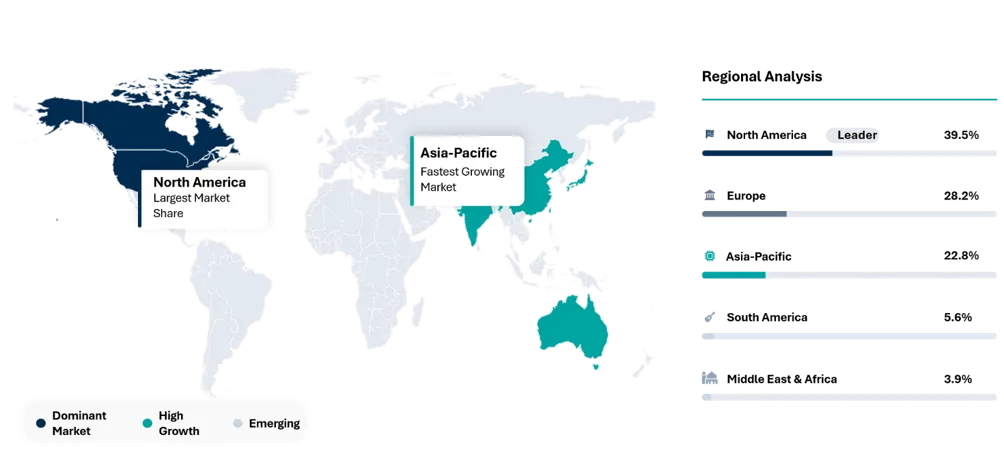
- North America Maintains Regional Dominance: North America accounted for an estimated 39.5% of the global market in 2025, equivalent to approximately US$4.57 billion, supported by strong reimbursement, specialist epilepsy centers and early adoption of differentiated therapies.
- Precision Neurology Reshapes Competitive Strategy: Future leadership will depend on genetically targeted therapies, differentiated mechanisms, pediatric indication expansion and convenient seizure-rescue formulations. Companies demonstrating durable seizure control, manageable safety and broad payer access will capture stronger commercial positions.
Epilepsy Drugs Market Scope
| Metrics | Details | |
| 2025 Market Size | US$11.56 Billion | |
| 2035 Projected Market Size | US$17.46 Billion | |
| CAGR (2026-2035) | 4.2% | |
| Largest Market | North America | |
| Fastest Growing Market | Asia-Pacific | |
| By Type | Generalized Seizures, Focal Seizures, Others | |
| By Treatment | Narrow-spectrum Antiepileptic Drugs, Broad-spectrum Antiepileptic Drugs | |
| By Route of Administration | Oral, Parenteral | |
| By Region | North America | U.S., Canada, Mexico |
| Europe | Germany, UK, France, Spain, Italy, Poland | |
| Asia-Pacific | China, India, Japan, Australia, South Korea, Indonesia, Malaysia, Singapore, Vietnam, Thailand, Philippines, Taiwan | |
| South America | Brazil, Argentina | |
| Middle East and Africa | Israel, Saudi Arabia, UAE, Turkiye, South Africa, Nigeria | |
| Report Insights Covered | Competitive Landscape Analysis, Company Profile Analysis, Market Size, Share, Growth | |
Epilepsy Drugs Market White Space & Investment Opportunities
- Earlier Diagnosis and Precision Risk Stratification: Invest in AI-assisted EEG interpretation, genomic testing, digital seizure detection and integrated clinical decision-support platforms. Earlier differentiation of epilepsy syndromes and seizure types can shorten diagnostic delays, improve initial drug selection and reduce exposure to ineffective therapies.
- Precision Therapies for Genetically Defined Epilepsies: Advance therapies targeting specific molecular causes of developmental and epileptic encephalopathies, including Dravet, Lennox–Gastaut and CDKL5 deficiency syndromes. Gene therapies, antisense oligonucleotides, RNA-based treatments and targeted small molecules represent high-value opportunities, particularly when paired with scalable genetic testing.
- Novel Mechanisms for Drug-Resistant Epilepsy: Develop differentiated antiseizure medicines for patients who remain uncontrolled after multiple treatments. Investment priorities include novel ion-channel modulators, selective receptor targets and disease-modifying approaches capable of improving seizure freedom without increasing cognitive, behavioral or systemic adverse effects.
- Rapid and User-Friendly Seizure-Rescue Therapies: Expand intranasal, buccal, transdermal and other non-invasive formulations for seizure clusters and prolonged seizures. Products offering faster administration, longer shelf life and simplified caregiver use can capture demand across home, school, workplace and emergency-care settings.
- Adherence-Focused Formulations and Integrated Care: Invest in once-daily medicines, extended-release formulations, pediatric-friendly dosage forms and combination products. Integration with connected medication systems, seizure diaries and remote monitoring can improve persistence, identify breakthrough seizures and generate real-world evidence supporting product differentiation.
- Geographic Access and Value-Based Reimbursement: Expand access to modern antiseizure medicines, specialist diagnosis and pharmacogenomic testing across underserved markets. Commercial models linking reimbursement to seizure reduction, treatment persistence, hospitalization avoidance and quality-of-life improvement could strengthen payer acceptance while addressing substantial treatment gaps.
Epilepsy Drugs Market Buyer Decision-Making Criteria
Major Buyer Decision-Making Criteria:
- Seizure-Freedom Rate and Sustained Seizure Control
- Percentage Reduction in Monthly Seizure Frequency
- Effectiveness by Seizure Type and Epilepsy Syndrome
- Clinical Benefit in Drug-Resistant and Refractory Epilepsy
- Suitability for Newly Diagnosed, Adjunctive and Later-Line Treatment
- Applicability Across Pediatric, Adult and Geriatric Populations
- Safety, Tolerability and Long-Term Clinical Evidence
- Cognitive, Behavioral and Psychiatric Adverse-Effect Profile
- Teratogenic Risk and Suitability for Women of Childbearing Potential
- Drug–Drug Interaction Profile and Compatibility with Polytherapy
- Route of Administration, Dosing Frequency and Treatment Burden
- Speed of Onset and Reliability of Seizure-Rescue Treatment
- Need for Therapeutic Drug Monitoring and Dose Titration
- Improvement in Daily Functioning, Independence and Quality of Life
- Treatment Adherence, Persistence and Caregiver Convenience
- Pricing, Reimbursement and Overall Cost of Epilepsy Management
- Guideline Positioning, Regulatory Approval and Neurologist Experience
- Availability of Pediatric-Friendly and Extended-Release Formulations
- Manufacturing Reliability, Geographic Availability and Supply Continuity
- Patient-Support, Adherence-Education and Access Programs
Epilepsy Drugs Market BCG Matrix: Company Evaluation
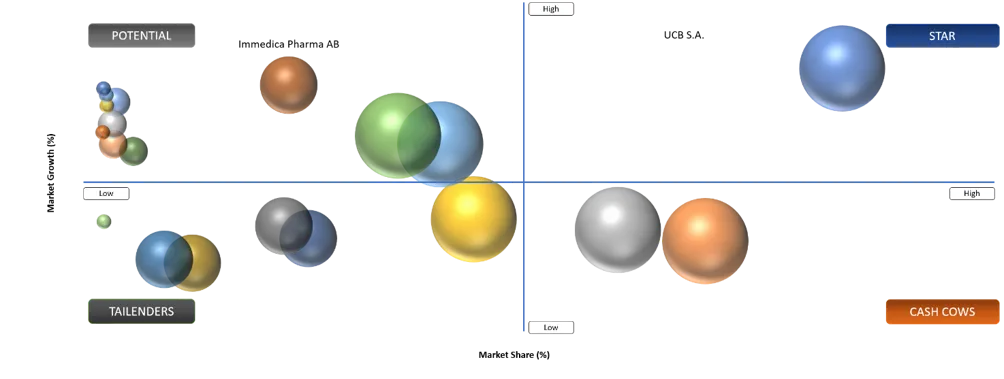
STAR
UCB S.A., Jazz Pharmaceuticals plc, SK Biopharmaceuticals Co., Ltd., Eisai Co., Ltd. and Supernus Pharmaceuticals, Inc. are positioned in the Star category based on their differentiated antiseizure medicines, established neurology commercialization capabilities and strong presence across epilepsy treatment pathways. UCB maintains a leading position through Briviact, Vimpat, Keppra, Fintepla and Nayzilam, covering chronic seizure management, developmental epileptic encephalopathies and seizure rescue. Jazz Pharmaceuticals competes through Epidiolex and Epidyolex for seizures associated with Lennox-Gastaut syndrome, Dravet syndrome and tuberous sclerosis complex.
SK Biopharmaceuticals strengthens focal-onset seizure treatment through Xcopri, while Eisai participates through Fycompa across selected international markets. Supernus Pharmaceuticals maintains a differentiated position through extended-release therapies Oxtellar XR and Trokendi XR. Future leadership will depend on indication expansion, pediatric approvals, geographic penetration, reimbursement coverage, patient-support programs and real-world evidence demonstrating sustained seizure reduction. Companies integrating differentiated formulations with specialist neurology networks should retain stronger commercial positioning.
POTENTIAL
Immedica Pharma AB, Neurelis, Inc., Aquestive Therapeutics, Inc., Angelini Pharma S.p.A., Catalyst Pharmaceuticals, Inc. and Sumitomo Pharma Co., Ltd. are positioned in the Potential category because of their involvement in rare epilepsies, seizure-rescue therapies, differentiated delivery formats and regional commercialization opportunities.
Immedica is strengthening its rare-neurology position through Ztalmy for seizures associated with CDKL5 deficiency disorder. Neurelis participates through Valtoco diazepam nasal spray, while Aquestive Therapeutics offers Libervant diazepam buccal film for seizure clusters. Angelini Pharma is expanding Ontozry across Europe, whereas BIAL and Sumitomo Pharma compete through eslicarbazepine-based therapies. Catalyst Pharmaceuticals markets Fycompa and Sabril in the United States. Progression toward the Star category will depend on broader indications, geographic expansion, improved reimbursement, physician adoption, differentiation from generic antiseizure medicines, scalable manufacturing and evidence demonstrating treatment convenience, safety and durable seizure control.
Epilepsy Drugs Market Dynamics
Driver Impact Analysis
| Driver | Market Growth Impact (%) | Demand Concentration | Impacted Use Case | Strategic Impact |
Expansion of Precision Therapies for Genetically Defined Epilepsy Syndromes | 17.5% | North America, Europe and developed Asia Pacific markets | Dravet syndrome, Lennox-Gastaut syndrome, CDKL5 deficiency disorder and other genetic epilepsies | Supports genotype-directed treatment, premium therapies, genetic testing and specialist-center commercialization |
Persistent Treatment Gap in Drug-Resistant Focal-Onset Epilepsy | 16.3% | United States, Europe, Japan and major Chinese urban markets | Patients remaining uncontrolled after two or more appropriate antiseizure medicines | Creates demand for differentiated mechanisms, combination regimens and later-line treatment options |
Increasing Adoption of Caregiver-Administered Seizure-Rescue Medicines | 14.2% | United States and Europe, with gradual expansion across Asia Pacific | Seizure clusters and prolonged seizures treated in homes, schools and community settings | Expands treatment beyond hospitals through intranasal sprays, buccal films and other non-invasive formulations |
Pediatric Indication Expansion and Branded Drug Lifecycle Management | 12.5% | Markets with established pediatric neurology and rare-disease reimbursement pathways | Infants, children and adolescents requiring maintenance or rescue therapy | Extends commercial lifecycles through younger-age approvals, new formulations and expanded indications |
Driver: Expansion of Precision Therapies for Genetically Defined Epilepsy Syndromes
The expansion of precision therapies for genetically defined epilepsy syndromes is accelerating demand for targeted antiseizure medicines. Wider access to genetic testing and next-generation sequencing is improving the identification of pathogenic variants associated with Dravet syndrome, CDKL5 deficiency disorder, SCN2A-related epilepsy, KCNT1-related epilepsy and other developmental and epileptic encephalopathies. Earlier molecular diagnosis enables clinicians to move beyond empirical treatment selection toward therapies aligned with specific disease mechanisms. Approved medicines such as fenfluramine, cannabidiol and ganaxolone have already established commercial pathways for rare epilepsy indications, while antisense oligonucleotides and gene-regulating therapies are advancing the disease-modifying treatment landscape.
This transition creates commercially attractive, clearly defined patient populations with substantial unmet needs and greater willingness among payers to evaluate premium therapies supported by strong clinical evidence. Pharmaceutical companies can strengthen positioning by integrating drug development with genetic-testing networks, specialist epilepsy centers, patient registries and companion diagnostic capabilities. However, commercial success will depend on demonstrating meaningful seizure reduction, developmental benefits, durable efficacy and manageable safety. Companies securing pediatric indications, accelerated regulatory pathways and international reimbursement will be better positioned to capture value across rare epilepsy populations and establish defensible leadership within precision neurology.
Restraint Impact Analysis
| Restraint | Drag on Market Growth (%) | Primary Impact Area | Impacted Use Case | Strategic Impact |
Persistent Trial-and-Error Prescribing Without Routine Biomarker-Guided Treatment Selection | 15.5% | Treatment selection, response predictability and therapy sequencing | Patients cycling through multiple antiseizure medicines before achieving adequate seizure control | Lengthens treatment optimization, increases discontinuation and limits rapid adoption of differentiated therapies without predictive biomarkers |
Patent Expiries and Accelerating Generic Substitution of Established Antiseizure Medicines | 14.0% | Branded revenue retention, pricing and portfolio lifecycle management | Long-term treatment with levetiracetam, lamotrigine, topiramate, pregabalin and lacosamide | Compresses branded-drug pricing, shifts prescription volumes toward generics and increases dependence on indication expansion and differentiated formulations |
Restricted Reimbursement for Premium Rare-Epilepsy and Precision Therapies | 12.5% | Patient access, payer approval and specialist prescribing | Dravet syndrome, Lennox-Gastaut syndrome, CDKL5 deficiency disorder and genetically defined developmental epilepsies | Prior authorization and evidence requirements delay treatment initiation and restrict commercial penetration beyond specialist epilepsy centers |
Safety, Tolerability and Drug-Interaction Burden Across Chronic Polytherapy | 11.0% | Treatment persistence, dose optimization and quality of life | Drug-resistant patients receiving multiple antiseizure medicines alongside treatments for psychiatric or neurological comorbidities | Cognitive impairment, sedation and interaction risks increase switching and non-adherence while raising the evidence threshold for new combination regimens |
Restraint: Persistent Trial-and-Error Prescribing Without Routine Biomarker-Guided Treatment Selection
Persistent reliance on trial-and-error prescribing remains a significant restraint on the global epilepsy drugs market. Treatment selection is frequently based on seizure type, clinical history, comorbidities and physician experience rather than validated biomarkers that predict individual response. Consequently, patients may cycle through several antiseizure medicines before achieving adequate seizure control, while experiencing cognitive impairment, sedation, behavioral effects or drug interactions. The challenge is particularly significant in drug-resistant epilepsy, where failure of two appropriately selected therapies indicates a lower probability of achieving seizure freedom through additional conventional medicines. Delayed optimization increases healthcare utilization, reduces adherence and weakens confidence in newly introduced therapies.
Limited routine genetic testing, inconsistent electroencephalographic interpretation and insufficient access to specialist epilepsy centers further constrain precision treatment selection, particularly across emerging markets and underserved communities. For pharmaceutical companies, this creates slower adoption curves and increases the evidence required to demonstrate meaningful differentiation from established generic therapies. Market participants must therefore invest in predictive biomarker research, pharmacogenomic evidence, patient registries and treatment-response algorithms. Partnerships with diagnostic laboratories and epilepsy centers could improve patient stratification, shorten treatment pathways and strengthen the commercial value of targeted antiseizure medicines.
Epilepsy Drugs Market Segment Analysis
The global epilepsy drugs market is segmented based on disease type, drug type, route of administration, and region.
Drug Type: The broad-spectrum antiepileptic drugs segment was valued at US$ 5.6 billion in 2024 and is estimated to reach US$ 8.5 billion by 2033, growing at a CAGR of 4.0%.
Broad-spectrum antiepileptic drugs (AEDs) are expected to maintain their lead in the epilepsy drugs market due to their ability to treat both focal and generalized seizures, making them suitable for a wide range of patients.
Recent developments further support the dominance of the segment. For instance, in July 2024, Glenmark Pharmaceuticals received final approval from the U.S. FDA for its generic version of Topiramate, a widely used broad-spectrum AED. Topiramate is a versatile medication known for its effectiveness in managing different types of seizures, including those related to epilepsy, as well as for preventing migraines.
Additionally, in May 2024, Eisai Co., Ltd. announced that it has received approval in China for the expanded indication of its in-house developed antiepileptic drug (AED), Fycompa (perampanel hydrate). The approval grants Fycompa authorization for use as an adjunctive therapy in treating primary generalized tonic-clonic seizures in epilepsy patients aged 12 and older.
These advancements demonstrate that the segment holds a dominant position in the epilepsy drugs market. Additionally, the demand for broad-spectrum drugs is expected to increase during the forecast period.
Epilepsy Drugs Market Geographical Penetration
U.S. Epilepsy Drugs Market Landscape
The U.S. epilepsy drugs market is characterized by high treatment intensity, broad generic availability and increasing adoption of differentiated therapies for drug-resistant and rare genetic epilepsies. The Epilepsy Foundation reports that more than 3.4 million people live with epilepsy nationwide, creating sustained demand across chronic maintenance, adjunctive and seizure-rescue treatment pathways. Established medicines such as levetiracetam, lamotrigine, topiramate and lacosamide remain widely prescribed, while branded products including Xcopri, Briviact, Fintepla, Epidiolex, Valtoco and Nayzilam compete through improved seizure control, specialized indications or convenient administration.
Market growth is increasingly concentrated in refractory focal-onset seizures, developmental epileptic encephalopathies and out-of-hospital seizure-cluster management. In the second quarter of 2026, Jazz Pharmaceuticals reported USD 292 million in Epidiolex and Epidyolex sales, representing 16% year-over-year growth, highlighting commercial demand for differentiated rare-epilepsy therapies. Competition is shifting toward precision medicines, Kv7 modulators, antisense oligonucleotides and non-invasive rescue formulations. However, generic substitution, prior authorization, specialist-access disparities and polytherapy-related safety burdens constrain adoption. Companies combining strong clinical differentiation with payer evidence, patient support and epilepsy-center engagement will achieve stronger commercial positioning.
Japan Epilepsy Drugs Market Outlook
Japan’s epilepsy drugs market is supported by a substantial treated population, universal health coverage and established neurology infrastructure. The Japan Epilepsy Society estimates prevalence at approximately 1%, representing nearly one million people affected by epilepsy. Demand remains concentrated in partial-onset seizures, generalized seizures, pediatric epileptic encephalopathies and drug-resistant cases requiring combination therapy. Established generic medicines continue to dominate prescription volumes, while differentiated branded products such as Fycompa, Briviact, Vimpat and Fintepla are expanding treatment options. Japan’s ageing population also increases the importance of therapies offering manageable cognitive, cardiovascular and drug-interaction profiles.
The market outlook is shifting toward newer mechanisms, specialized formulations and treatments for rare epilepsy syndromes. UCB reported in July 2025 that Briviact achieved double-digit growth, supported by its Japanese availability since June 2024, indicating demand for differentiated focal-seizure medicines. Commercial success will depend on securing National Health Insurance reimbursement, generating Japanese clinical evidence and building relationships with specialist centers. Growth opportunities remain strongest in pediatric indications, rare genetic epilepsies, injectable formulations and therapies addressing refractory seizures. Nevertheless, generic substitution, cautious treatment switching and strict pricing revisions will constrain premium-brand expansion.
Epilepsy Drugs Market Competitive Landscape
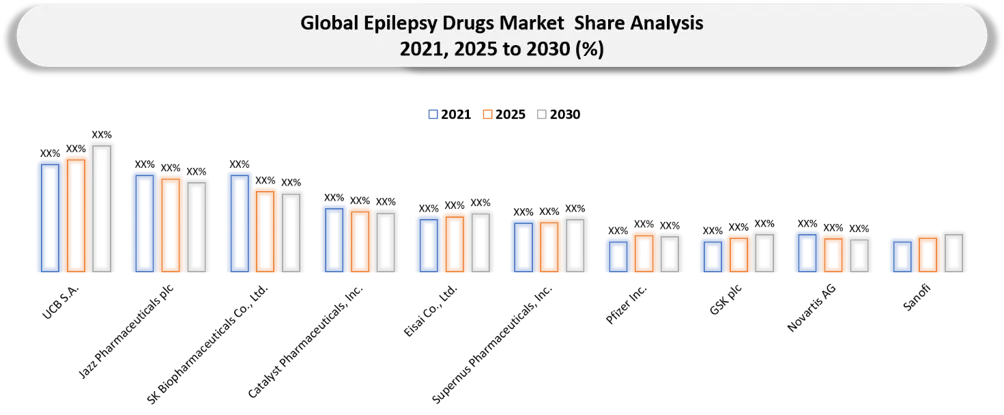
- The global epilepsy drugs market presents a moderately consolidated competitive landscape, led by research-based pharmaceutical companies with established antiseizure portfolios, extensive regulatory capabilities and strong neurologist relationships. UCB maintains a prominent position through Briviact, Vimpat, Keppra, Fintepla and Nayzilam, covering maintenance treatment and seizure rescue. Jazz Pharmaceuticals, SK Biopharmaceuticals, Catalyst Pharmaceuticals, Eisai and Supernus Pharmaceuticals compete through differentiated therapies addressing severe epilepsy syndromes, focal-onset seizures and treatment-resistant patients. Pfizer, GSK, Novartis and Sanofi retain market relevance through widely prescribed established medicines, extensive geographic distribution and longstanding clinical familiarity. Regional commercialization agreements also influence competition, as product rights may vary across the United States, Europe and Asia.
- Competitive differentiation increasingly depends on seizure reduction, tolerability, dosing convenience, pediatric eligibility, rapid administration and effectiveness in drug-resistant epilepsy. Companies are prioritizing novel mechanisms, extended-release formulations, intranasal rescue therapies, buccal films and treatments for rare developmental epileptic encephalopathies. Generic manufacturers, including Teva, Viatris, Sun Pharmaceutical Industries and Dr. Reddy’s Laboratories, strengthen price competition and treatment accessibility. Future market leadership will depend on lifecycle management, broader indications, clinical evidence, reimbursement access, patient-support programs and successful commercialization across underserved markets.
Key Companies in the Epilepsy Drug Market
- UCB S.A. (Belgium)
- Jazz Pharmaceuticals plc (Ireland)
- SK Biopharmaceuticals Co., Ltd. (South Korea)
- Catalyst Pharmaceuticals, Inc. (United States)
- Eisai Co., Ltd. (Japan)
- Supernus Pharmaceuticals, Inc. (United States)
- Pfizer Inc. (United States)
- GSK plc (United Kingdom)
- Novartis AG (Switzerland)
- Sanofi (France)
- Angelini Pharma S.p.A. (Italy)
- Sumitomo Pharma Co., Ltd. (Japan)
- Immedica Pharma AB (Sweden)
- Neurelis, Inc. (United States)
- Aquestive Therapeutics, Inc. (United States)
- Teva Pharmaceutical Industries Ltd. (Israel)
- Viatris Inc. (United States)
- Sun Pharmaceutical Industries Limited (India)
- Dr. Reddy’s Laboratories Limited (India)
Epilepsy Drugs Market Recent Developments
- September 2026: Jazz Pharmaceuticals completed its acquisition of Actio Biosciences, adding ABS-1230, a clinical-stage precision therapy being developed for KCNT1-related epilepsy, to its neuroscience pipeline. The transaction strengthens Jazz’s presence beyond Epidiolex and expands its capabilities in genetically defined developmental and epileptic encephalopathies.
- September 2026: The FDA placed a partial clinical hold on Biohaven’s opakalim or BHV-7000 epilepsy program following rodent findings involving a metabolite. New enrolment was paused, although more than 600 enrolled participants could continue treatment. The action introduces potential delays and additional safety-data requirements for the refractory focal epilepsy program.
- September 2026: Stoke Therapeutics and Biogen presented long-term clinical findings supporting the potential disease-modifying activity of zorevunersen in Dravet syndrome. The investigational antisense oligonucleotide is designed to increase functional SCN1A protein expression and address the underlying genetic cause of the disease.
- August 2026: SK Biopharmaceuticals secured worldwide rights to Biohaven’s BHV-7000 or opakalim and related Kv7-targeting compounds. The agreement expands SK Biopharmaceuticals’ epilepsy pipeline beyond Xcopri and supports its strategy of developing treatments for refractory focal-onset seizures.
- August 2026: Xenon Pharmaceuticals announced presentations of Phase III X-TOLE2 clinical data for azetukalner, a selective Kv7 potassium-channel opener under development for focal-onset seizures. The presentations examined seizure reduction, long-term seizure freedom and the candidate’s potential role in rational combination therapy.
What DATAM Uniquely Provides
- In-depth segmentation of the epilepsy drugs market by seizure type, epilepsy syndrome, treatment type, drug class, mechanism of action, route of administration, treatment line, patient age group, care setting, distribution channel and region.
- Competitive analysis of leading epilepsy drug companies covering seizure-freedom rates, seizure-frequency reduction, response durability, safety and tolerability, mechanism of action, syndrome-specific positioning, dosing convenience, clinical-pipeline maturity and commercialization strategy.
- Comprehensive assessment of diagnosed and treatment-eligible populations, including newly diagnosed patients, drug-resistant epilepsy patients, pediatric and adult populations, women of childbearing potential and patients with Dravet syndrome, Lennox–Gastaut syndrome, CDKL5 deficiency disorder and other developmental and epileptic encephalopathies.
- Actionable intelligence on pharmaceutical pricing, reimbursement, regulatory pathways, genetic testing, therapeutic drug monitoring, treatment-response assessment, therapy sequencing, patient-support programs, market-access barriers, licensing activity, strategic partnerships and investment opportunities.
- Analyst forecasts highlighting high-growth drug classes, commercially attractive patient populations, regional expansion opportunities and emerging competitive threats across narrow-spectrum and broad-spectrum antiseizure medicines, rescue therapies, precision medicines, extended-release formulations, gene therapies, antisense oligonucleotides and other disease-modifying treatment platforms.




























































